Figures, prices and terms were checked against the MHLW notice on the high-cost medical expense revision effective August 2026 on 6 August 2026, the two-system comparison against Kyokai Kenpo’s FY2026 rates on 13 September 2026, and the rules for leaving kokuho and for insurance cards against MHLW and city guides on 30 September 2026. They change – check the current terms yourself before you sign up or file anything.
In short
- Japan has two public health insurances, and you are in exactly one. Employees are enrolled by their company; everyone else joins National Health Insurance at the city office within 14 days.
- If you live in Japan for more than 3 months, joining is compulsory.
- You pay 30 percent of medical costs: a 10,000 yen bill becomes 3,000 yen.
- Premiums depend on your city and income. If money is tight, apply for a reduction – do not ignore the bills.
- Unpaid premiums can hurt your visa renewal (as of September 2026).
Once you know this, you can get the insurance that turns a 10,000 yen bill into 3,000 yen within 14 days, and stay off the side where unpaid premiums put your visa renewal at risk.
If you live in Japan for more than three months, you must be in one of Japan’s two public health insurances. If a company employs you, it enrols you in Employee Health Insurance and you do nothing. Everyone else joins National Health Insurance (国民健康保険 / kokumin kenkō hoken, shortened to kokuho) at the city office.
This is not optional. It is a legal requirement. But it is also one of the best things about living in Japan: it turns a ¥10,000 hospital bill into a ¥3,000 bill.
This guide first tells you which of the two you are in, then explains kokuho in full – how to join, what it costs, and the mistakes that cause real problems, including one that can affect your visa renewal.
- Which health insurance are you in? Japan has two
- Why this matters: you pay only 30%
- Join within 14 days – this is important
- Where to go and what to bring
- What it costs
- Changing jobs, moving or leaving Japan: kokuho does not stop by itself
- If you cannot afford it, do not ignore it
- What happens if you fall behind on payments
- Unpaid premiums reach your visa
- Using your insurance card
- If your bill is very large: the high-cost medical system
- Do you also need private insurance? Usually not – here is when it helps
- Things people get wrong
- Frequently asked questions
- What is the difference between Employee Health Insurance and National Health Insurance?
- Do I have to join National Health Insurance?
- How much of my medical bill does it cover?
- Can I use it at the dentist?
- Can I be in both company insurance and National Health Insurance?
- Do foreigners need private health insurance in Japan?
- Is public health insurance enough, or should I also buy private cover?
- Do I still pay premiums while I am back home for a while?
- What happens if I stop paying?
- Quick summary
- Related guides
Which health insurance are you in? Japan has two
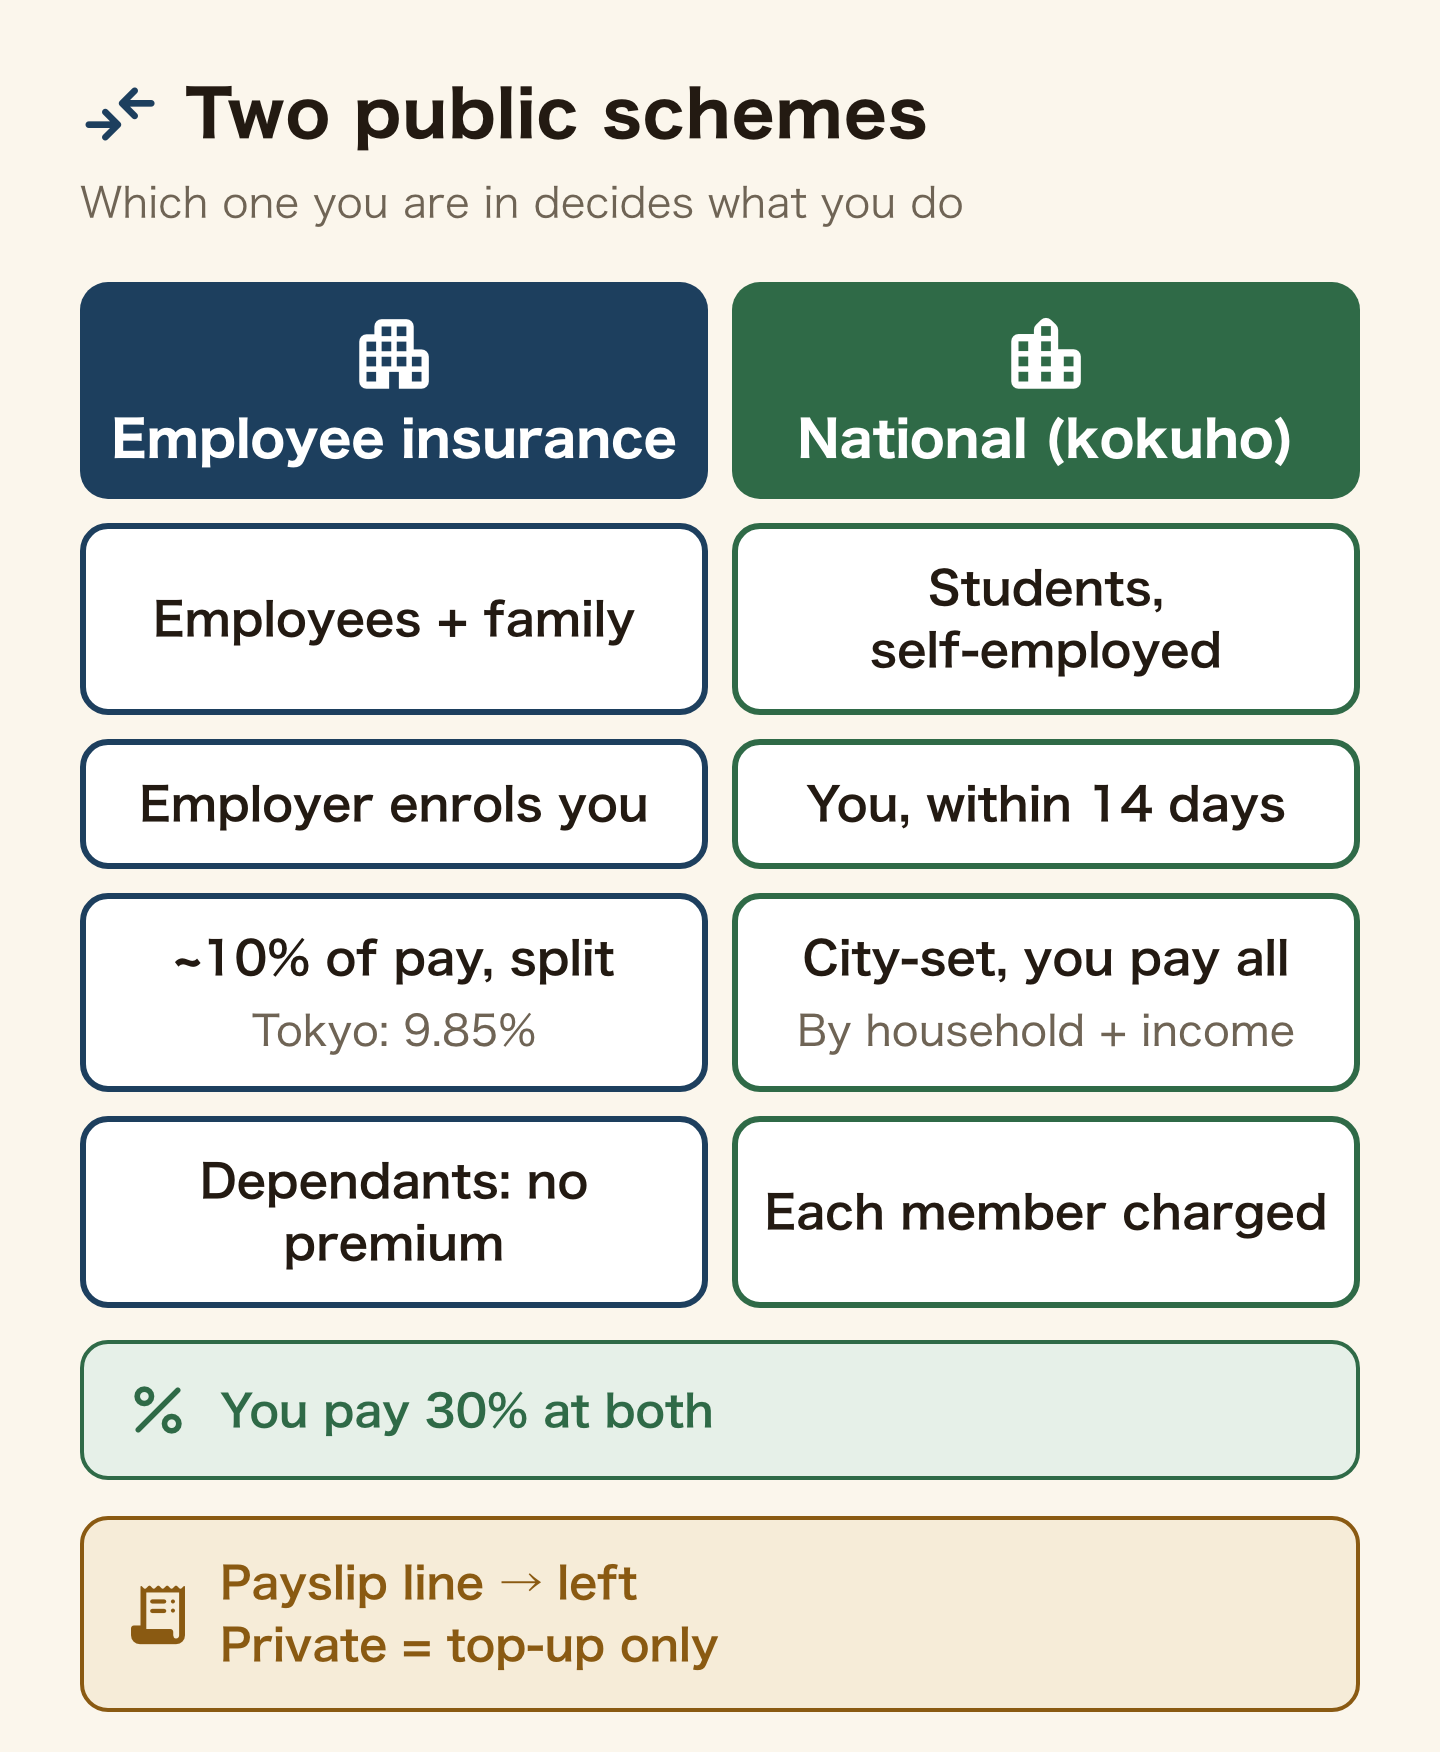
Employee Health Insurance (健康保険 / kenkō hoken, often called shakai hoken) is for people employed by a company. The company enrols you. The premium is roughly 10% of your salary, and the employer pays half of it – the law splits it evenly. The rate is set by prefecture each year: in Kyokai Kenpo’s fiscal 2026 rates by prefecture, Tokyo is 9.85%, Osaka 10.13%, Aichi 9.93%. Your spouse and children can join as dependants at no extra premium, as long as they live in Japan and earn under 1.3 million yen a year.
National Health Insurance (kokuho) is for everyone the first one does not cover: students, the self-employed, part-timers whose employer does not enrol them, and anyone between jobs. You enrol yourself at the city office. The premium is set by your municipality from your household size and last year’s income, and you pay all of it – there is no employer to share it. Each family member is charged, though children and low-income households get reductions. Members aged 40-64 also pay a long-term care part, set by your city, which covers care before 65 only for specified diseases.
Not sure which you are in? Look at your payslip. A line deducting health insurance (健康保険) means you are in Employee Health Insurance. No such line means you must be in kokuho – and if you are not, you need to go to the city office. You are never in both.
Most international students are on kokuho. Part-time workers whose hours are too short for their employer to enrol them are on kokuho too. If you are a university student, Gakkensai also pays a separate amount for injuries in class or on the way to school.
One more thing, because the top search results are mostly insurance companies: private and international health insurance is a top-up, not a replacement. Public insurance is compulsory for anyone staying more than three months. A private policy can add English-speaking support or cover abroad, but it does not free you from the public system. Relatives visiting you on a short stay are the opposite case: they cannot join public insurance at all, so private cover is all they have (what a family visit means for medical bills). Before buying any top-up, see which gaps public cover really leaves, and when life insurance makes sense — National Health Insurance, for example, may not pay sick pay.
The rest of this guide is about kokuho, because that is the one you have to handle yourself.
Why this matters: you pay only 30%
National Health Insurance is a public system: everyone pays in, and it helps whoever falls ill or gets injured. With kokuho, the government pays 70% of your medical costs. You pay the remaining 30% (20% for children before primary school, per the MHLW table of co-payment rates). On a ¥10,000 bill, insurance pays ¥7,000 and you pay ¥3,000. For a child, your city’s children’s medical subsidy then cuts that share further, often to nothing.
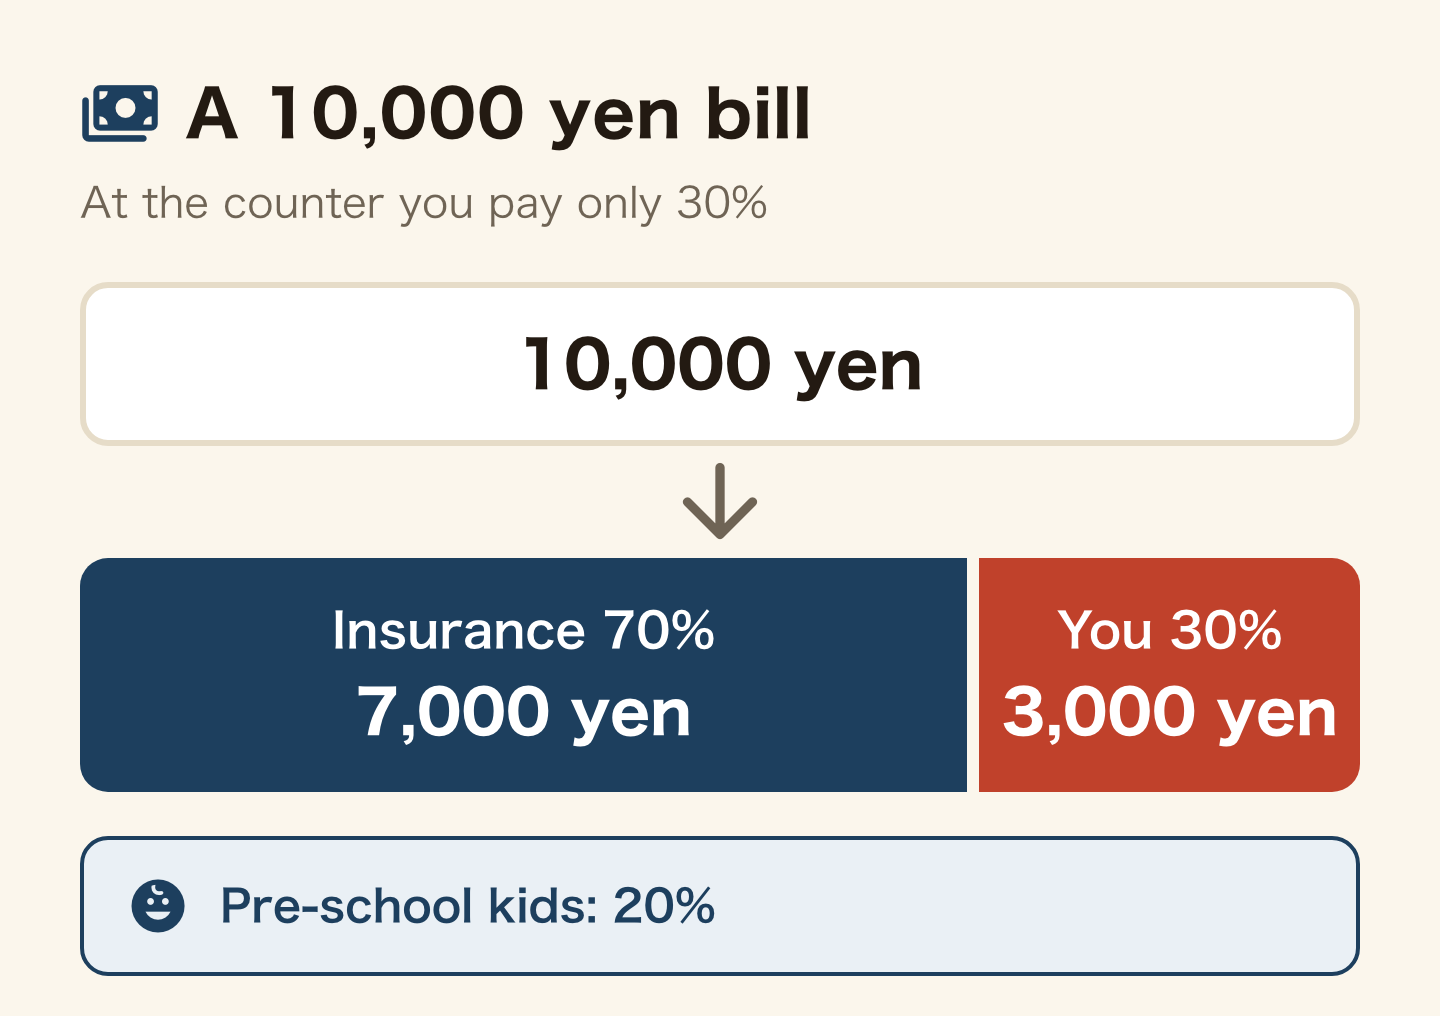
The same 30% rate applies to a ¥50,000 surgery – you would pay ¥15,000. It works at hospitals, clinics, pharmacies, and dentists (the one exception: an injury at work or on the commute goes through rosai insurance instead). (Cosmetic treatment such as teeth whitening is not covered.)
Join within 14 days – this is important
You have just arrived, you feel fine, and you plan to sort out insurance the first time you need a doctor. Where you come from, that may be normal. In Japan, National Health Insurance is not something you get to start on a day of your choosing.
You must apply within 14 days of registering your address at the city office. The 14 days is set in the National Health Insurance Enforcement Regulations (Article 2).
Why this matters: coverage does not start from the day you apply. It starts from the day you became a resident. So if you delay:
- You will be charged the back premiums for all the months you skipped
- Any hospital visit before you join is paid 100% at the counter. If you join within 14 days, you can claim the 70% back afterwards (as a ryōyōhi refund)
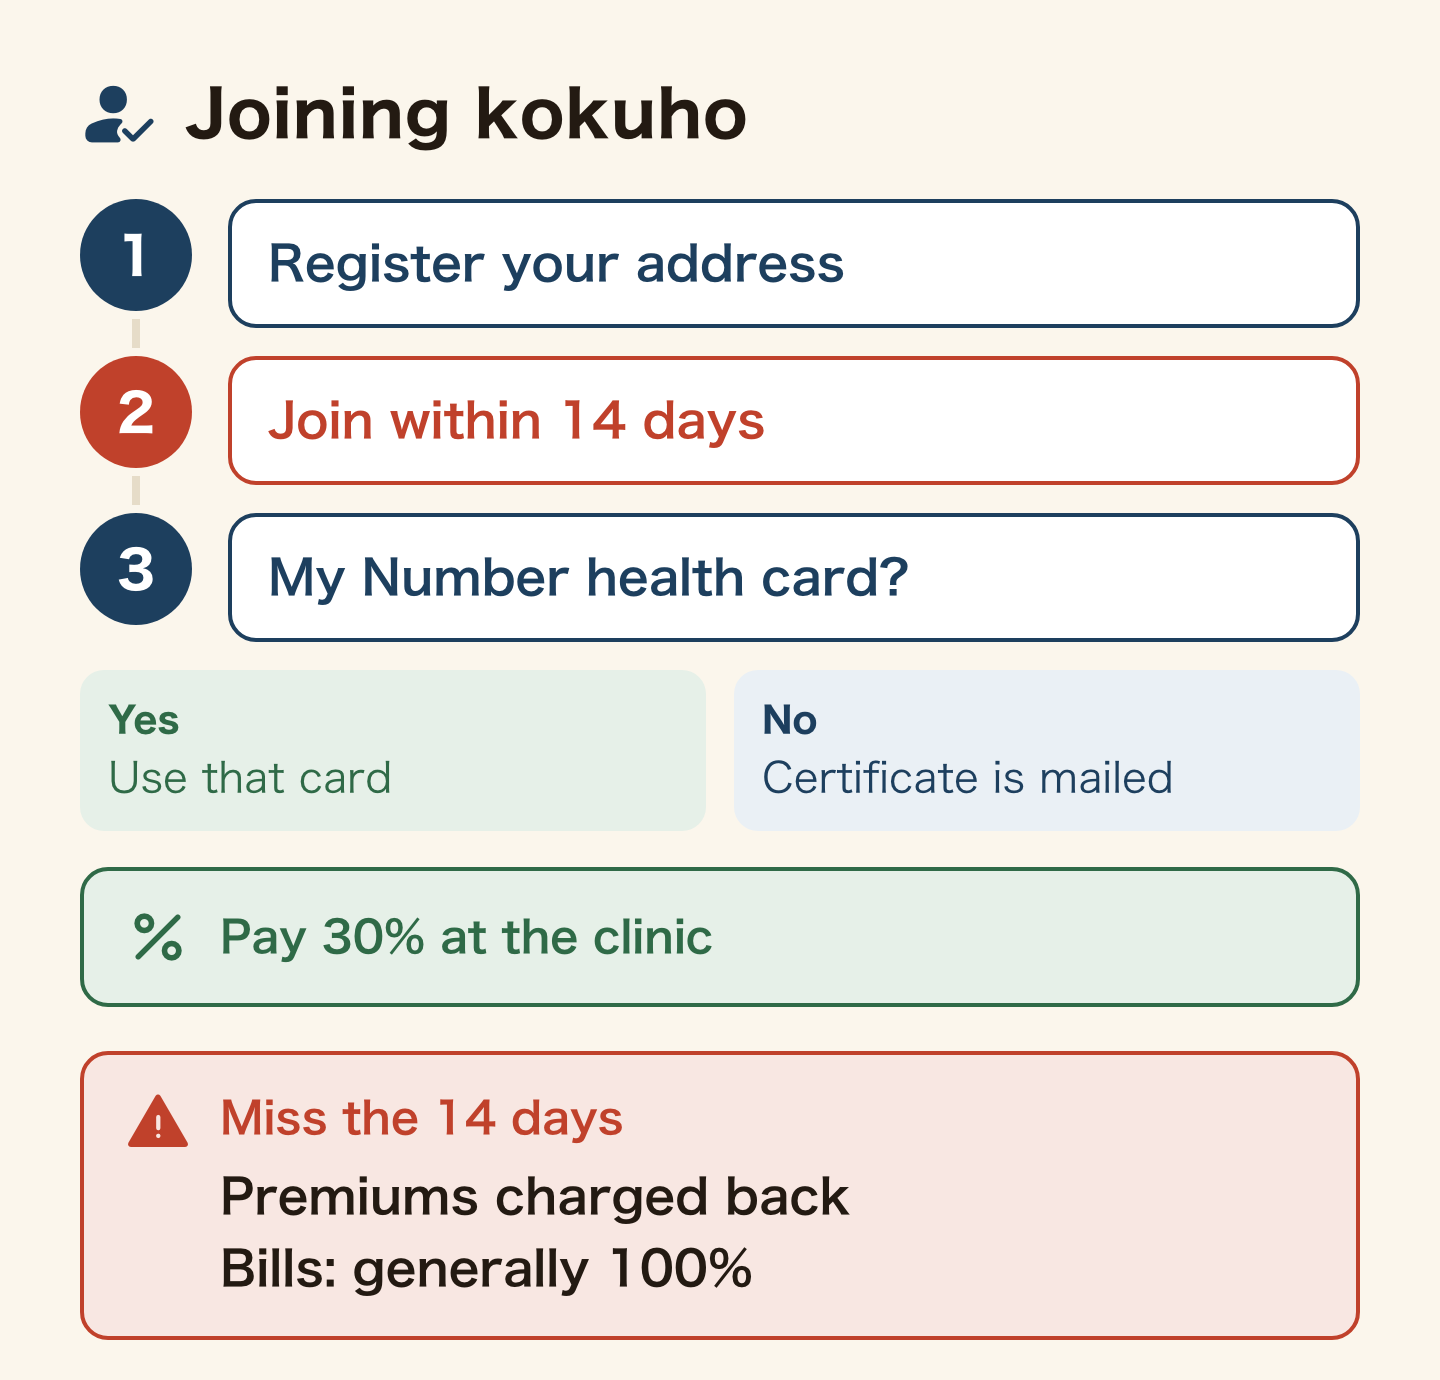
Miss the 14 days and, unless there were unavoidable circumstances, the bills from the gap generally stay 100% yours. Nagoya City’s enrolment page says the same: after the deadline, benefits are in principle paid only from the day you file, while premiums are charged back to the month you moved in. Example: you arrive on 1 April but join in May. Your April hospital bill is likely to stay 100% yours – and you still owe April’s premium.
Where to go and what to bring
Go to the city, ward, or town office (市役所・区役所・町役場) for the address where you actually live. You cannot do this at a different municipality’s office.
At the office, look for one of these counters:
- 国民健康保険課 (kokumin kenkō hoken ka) – National Health Insurance Division
- 保険年金課 (hoken nenkin ka) – Insurance and Pension Division
You can show that text on your phone at the information desk.
Bring these
- Residence card (在留カード / zairyū kādo) – essential
- Passport
- My Number card or notification slip (マイナンバーカード / 通知カード)
- Personal seal (印鑑 / inkan) – many offices now accept a signature instead
- Student ID (学生証) – sometimes requested
Show this at the counter
Show this to the staff at the National Health Insurance counter of your city or ward office (often called kokumin kenkou hoken-ka or hoken nenkin-ka).
What to say (with reading aids)
「国民健康保険に入る手続きをしたいです」
“I want to join National Health Insurance.”
For the staff member(職員の方へ)
国民健康保険の加入手続きをお願いします。住民登録は済んでいます。在留カード・パスポート・マイナンバーが分かるものを持ってきました。前年の所得の申告が必要な場合は、あわせて教えていただけますか。
Counter names and documents differ a little by municipality. Calling ahead is the safest.
Requirements vary slightly by municipality, so check your city’s website first if you can. If you have not registered your address yet, read our guide to the residence certificate (juminhyo).
What it costs
Premiums are not the same everywhere. Each municipality sets its own rate, and the amount is based on last year’s income.
Because most students earned little or nothing in Japan last year, their premiums are usually low:
- Example for a student with little income: in Tokyo’s 23 wards for fiscal 2026 (Reiwa 8), a person under 40 with zero income last year has a per-person flat fee of ¥65,200 (¥47,600 medical + ¥17,600 support portion; Shinjuku Ward’s premium page). With the 70% reduction, ¥65,200 × 0.3 = ¥19,560 a year, about ¥1,630 a month (conditions on Itabashi Ward’s page)
- Zero income does not mean a zero premium, because kokuho has a flat per-person part (均等割 / kintōwari). Low-income households get 70%, 50% or 20% off it
- Those working more part-time hours: an income-based charge is added on top of the flat fee, so it costs more than the example above. Rates differ by city, so search your city name plus “国保 保険料 試算” and check your own city’s calculator
Your city office can tell you your exact amount. Members aged 40-64 also pay the long-term care part described above. If you work part-time, our guide on tax for part-time workers explains how income is counted.
How to pay
- Payment slip (納付書 / nōfusho) at a convenience store or bank
- Automatic bank transfer (口座振替 / kōza furikae) – easiest, set it up once
In Toshima City, for example, the payment slips arrive together once a year in June if your premium has not changed, and each one is due by the end of its month; bank transfer is taken on the last day of each month (Toshima City’s English guide). Timing and the number of payments differ by city.
Changing jobs, moving or leaving Japan: kokuho does not stop by itself
You have to file to leave kokuho, just as you filed to join. Toshima City’s English guide puts joining, changes and leaving under the same rule: file within 14 days.
- You join a company’s insurance: file to leave kokuho yourself. If you are late, kokuho premiums keep coming and you get payment reminders (Toshima City, in Japanese)
- You move to another city: join kokuho again at the new city office within 14 days, and hand your eligibility certificate back to the old one if you have it (Nagoya City, in Japanese)
- You leave Japan: file before you go. If you do not, premiums continue to be charged for as long as your resident record is kept (Toshima City)
From the day your company insurance starts, your kokuho certificate can no longer be used. If you use it anyway, the city may ask you to repay what kokuho paid (Nagoya City). To file, bring the company insurance eligibility certificate or “qualification information notice” for everyone who is leaving kokuho (Toshima City).
If you cannot afford it, do not ignore it
This is the most important paragraph in this article.
If you stop paying:
- Your insurance card can stop working – you pay 100% at the hospital
- Late fees (延滞金 / entaikin) are added
- It can affect your visa renewal. Immigration may check whether you have paid. Unpaid premiums can be treated as a sign that you are not meeting your obligations as a resident.
That last point surprises many people, and it is the reason ignoring the bills is dangerous.
Go to the city office and say you cannot pay. Reduction programmes (減免 / genmen) and instalment plans exist, and low-income residents often qualify. Staff will not report you or cancel your visa – their job is to arrange payment. Asking early is always cheaper than staying silent.
This amount can also come down. Households with low income last year get 70, 50 or 20 percent off the flat part, but the reduction never arrives unless the city office knows your income. Zero income still has to be declared. See the National Health Insurance reduction.
What happens if you fall behind on payments
Ignore it rather than talk to them, and it gets heavier in stages. First come reminders, then late charges. So far, the same as any unpaid tax.
The next stage is the problem. Prolonged non-payment switches you to something called “special medical expenses”. What you are issued then is a “qualification confirmation document (special medical treatment)”, and walking into a hospital with that means paying the full 100% at the counter. Not 30%. A 10,000 yen treatment costs you 10,000 yen instead of 3,000.
You can claim the difference back afterwards, but if you cannot produce the full amount on the day, that is the same as not being able to go.
The names are confusingly close, so read this part carefully. It is not the ordinary “qualification confirmation document”. That one, issued to people without a My Number health card, still gets you treated at 30%. The one that non-payment switches you to has “(special medical treatment)” attached.
Note also that the short-term insurance card and the qualification certificate were abolished on 2 December 2024. Articles written before that date explain this using those two old names; the system now works as described above.
Unpaid premiums reach your visa
Insurance bills come from the city office; your visa is handled by immigration. Different counters, so surely they have nothing to do with each other. Where you come from, that may be how it works. In Japan, the two are connected.
Asking for help also protects permanent residence (August 2026 draft)
Draft operational guidelines were published for the revocation system starting in April 2027. The ground “wilfully failing to pay public dues” includes public health insurance and pension premiums.
The draft also spells out what does not count: “illness, disaster, unemployment and other unavoidable circumstances”, and “responding to demands, showing willingness to pay, and being granted instalments or a deferral”. Being unable to pay is not itself the problem. A record of going to the counter and arranging instalments is what protects your status. (Public comment runs to 4 September 2026; this is still a draft.)
This is the part that weighs most on foreign residents.
When you apply to extend your period of stay, the counter asks to see your health insurance card. Since 2 December 2024, anyone without a card shows the qualification screen in Mynaportal, the “qualification information notice”, or a qualification confirmation document instead. Whether you have been paying is visible on the spot.
The Immigration Services Agency’s guideline on changing status and extending your period of stay puts it this way: where premiums that the law requires you to pay, national health insurance among them, involve large unpaid sums or long periods of non-payment, the serious cases are weighed as a negative factor.
For permanent residence it is more explicit still. Under the permanent residence guidelines, properly fulfilling public obligations, meaning tax, public pension, and public health insurance premiums, is one of the requirements itself. If you are working toward permanent residence, unpaid premiums land directly on that.
Which is why the previous section bears repeating. When you cannot pay, the move is to talk to them, not to ignore it. The city office does not report you, and asking for help does not touch your visa. Ignoring it is what touches your visa.
Using your insurance card
After you join, you receive proof of insurance (保険証 / hokenshō). The old insurance cards have not been newly issued since 2 December 2024, so if you have not registered your My Number Card as a health card, you are sent a Health Insurance Eligibility Certificate without applying (MHLW page on the My Number health card). Which of the two you show at reception depends on whether you registered. Carry it in your wallet at all times.
- Show the card at the hospital reception
- Give your name and date of birth
- Pay only your 30% at the end
- At the pharmacy, show the card again to get medicine at 30%
If you forget your card
You pay 100% that day. Keep the receipt, take it to the city office, and you can claim the 70% back. You do not lose the money – it just takes extra work.
Card rules
- Update your address immediately if you move
- Check the expiry date. When your period of stay runs out, your kokuho membership ends too. In Toshima City, for example, a new eligibility certificate is sent to you automatically once you renew your period of stay at immigration (Toshima City’s English guide). Ask your own city office how it works there.
- Never lend your card to anyone. This is a crime in Japan, and it can end your stay.
If your bill is very large: the high-cost medical system
If you need surgery or a hospital stay, costs can be high even at 30%. Japan has a safety net called the High-Cost Medical Expense Benefit (高額療養費制度 / kōgaku ryōyōhi seido).
It sets a monthly maximum based on your age and income. Anything above that limit is refunded. From treatment in August 2026, the monthly ceiling for under-70s is 36,900 yen for a resident-tax-exempt household (it was 35,400), 61,500 yen for income up to roughly 3.7 million (it was 57,600), and 85,800 yen + 1% for roughly 3.7-7.7 million (it was 80,100 + 1%). A yearly cap was added at the same time – 290,000 yen for a tax-exempt household, 530,000 for the bands above (MHLW notice on the August 2026 revision). If a hospital stay is planned, get a “limit certificate” (限度額適用認定証) from your city office first so you only ever pay up to the ceiling at the counter.
At the hospital counter, say: 「高額療養費制度について教えてください」 (“Please tell me about the high-cost medical expense system”). Ask before a planned hospital stay if possible – it is easier to apply in advance than to claim back later. With a My Number health card you do not need the certificate at all; the full band table and the two-year claim deadline are in the high-cost medical expense guide.
Do you also need private insurance? Usually not – here is when it helps
Search this question and most of the top answers come from companies that sell insurance. Their answer is yes. For most people living here, the plain answer is no.
A simple rule decides it: insure only what you could not pay from your own savings. Medical bills are rarely in that group. The public scheme already pays 70% of ordinary treatment, and your 30% share is capped each month by the high-cost medical system above. For the treatment itself, a long hospital stay does not become a bill without an end. What is left over is a cost savings can carry.
So put the money a private medical plan would cost into savings first. Keep enough to live on for several months – rent, food and bills – in an account you do not touch. That money pays for the gaps below, and if you never get ill, it is still yours.
The public scheme does leave four gaps. Here is what each one means for you.
1. Lost pay when you are too ill to work
Employee Health Insurance pays a sickness and injury allowance (傷病手当金 / shōbyō teatekin) when illness or injury outside work keeps you off. After 3 days off in a row, it is paid from day 4, at about two-thirds of a daily amount worked out from your standard monthly pay over the last 12 months, for up to 1 year 6 months in total (Kyokai Kenpo’s page on the allowance).
National Health Insurance is different. The law says cities “may” provide it in their bylaws, so it exists only where your city has chosen to (National Health Insurance Act, Article 58(2)). If you are self-employed or freelance on kokuho, a month in bed can mean a month with no income. Your savings are the first cover for this. Only if you could not live for months without work, and have no savings yet, is cheap income cover (a plan that pays you while you cannot work, with no savings element) worth a look. Before you buy anything, read who gets the sickness allowance and how much it pays – on company insurance you may already have what such a policy sells.
2. Having a baby
A normal pregnancy and birth is not treated as an illness, so it is not paid at 30% (Minato City’s list of what National Health Insurance does not cover). Each facility sets its own price for it (MHLW on childbirth costs).
Instead, either public plan pays a childbirth lump sum (出産育児一時金 / shussan ikuji ichijikin). Since April 2023 it is 500,000 yen per baby, or 488,000 yen if the birth is outside the obstetric compensation scheme (産科医療補償制度) (MHLW, changes from April 2023). A caesarean or similar delivery is covered by health insurance, and the high-cost cap applies to it (Kyokai Kenpo, childbirth lump sum).
3. Treatment abroad
If you fall suddenly ill on a trip, you pay the foreign hospital in full and claim part of it back after you return. This is the overseas medical expense refund (海外療養費 / kaigai ryōyōhi). The refund is based on what the same treatment would cost in Japan, or what you actually paid if that is lower, minus your usual share. Kyokai Kenpo warns it can be much less than you paid (Kyokai Kenpo, overseas medical expenses).
Kokuho works the same way: you apply after coming back, within 2 years of the day after the treatment, and a trip made in order to get treatment is not covered (Minato City, overseas medical expenses). If you go home often, or to a country with expensive hospitals, travel cover is what fills this gap.
4. Care that public insurance does not cover
Some things are not treated as illness at all: health checkups, vaccinations, orthodontics and cosmetic surgery, among others (Minato City’s list above). Treatment outside insurance is full price too. These are costs to plan for from savings, not reasons to buy a policy.
A quick check
You do not need private medical insurance if:
- You are in one of the two public schemes, and
- You have, or are building, savings for several months of living costs
Think about something extra only if:
- You are on kokuho, have no savings yet, and could not live for months without work: cheap income cover, until your savings are big enough
- You are travelling abroad: travel cover for that trip (first check whether something you already have, such as a credit card, includes it)
- Your stay is three months or less, which in most cases keeps you out of the public scheme (Toshima City): travel or international cover for your stay
Whichever you choose, private cover sits on top of public insurance. It never replaces it.
The insurance worth paying for is a different kind: cover for losses no savings could pay. That means fire insurance for your apartment, personal liability cover (often a rider on that same fire insurance), car insurance if you drive, and plain term life insurance if your family depends on your income. If you are a student, the student insurance guide shows what your school’s insurance covers and where the personal liability rider fits in.
Premiums vary by city and income. This guide reflects information as of September 2026.
Either public plan also pays a 500,000 yen lump sum when a baby is born. During pregnancy, the boshi techo, checkup vouchers and pregnancy support payment come from your city, whichever plan you are on. On National Health Insurance at 40 to 74, you also get a yearly city health checkup (tokutei kenshin), free in Osaka and Yokohama.
Things people get wrong
Going home for the holidays
Your Japanese insurance card does not work overseas. If you get treated back home, you pay in full there. In some cases you can claim part of it back after returning to Japan – keep every receipt and ask your city office.
Also note: you still owe premiums while you are away, because you are still a registered resident of Japan.
Being sent to the wrong kind of hospital
For everyday problems – a cold, a fever, an injury – go to a small local clinic (クリニック / 医院), not a large hospital. Clinics have shorter waits. If you need more, they will refer you to a hospital.
Accepting treatment that insurance does not cover
Some treatment is “free treatment” (自由診療 / jiyū shinryō) and is not covered at all. If you do not understand what is being proposed, ask: 「これは保険が使えますか?」 (“Is this covered by insurance?”) before agreeing.
Frequently asked questions
What is the difference between Employee Health Insurance and National Health Insurance?
Employee Health Insurance (shakai hoken) is arranged by your company, costs about 10% of salary with the employer paying half, and covers your dependants at no extra premium. National Health Insurance (kokuho) is for everyone else – students, the self-employed, people between jobs – you enrol yourself at the city office and pay the whole premium, and each family member is charged. Both leave you paying 30% at the clinic. If you are a university student, Gakkensai also pays a separate amount for injuries in class or on the way to school.
Do I have to join National Health Insurance?
Yes. If you stay in Japan more than 3 months and have no employer insurance, joining is required by law. Register at your city office within 14 days of moving in.
How much of my medical bill does it cover?
You pay 30 percent. A 10,000 yen hospital bill becomes 3,000 yen, and it covers clinics, hospitals and prescribed medicine (as of September 2026).
Can I use it at the dentist?
Yes. Cosmetic treatment such as teeth whitening is not covered, though.
Can I be in both company insurance and National Health Insurance?
No. You are only ever in one. When you join company insurance, file to leave National Health Insurance.
Do foreigners need private health insurance in Japan?
Not instead of public insurance. Anyone staying more than three months must be in one of the two public schemes. Private or international policies are optional top-ups for English-speaking support or coverage abroad.
Is public health insurance enough, or should I also buy private cover?
For most people it is enough: you pay 30%, and that is capped each month by the high-cost medical system. Instead of a private medical plan, keep savings for several months of living costs. Think about something extra only in a few cases: you are on National Health Insurance, which pays sick pay only if your city’s bylaws provide it, and have no savings to live on; you are travelling abroad, where the refund is limited to Japanese prices; or you stay three months or less and cannot join the public scheme.
Do I still pay premiums while I am back home for a while?
Yes. As long as you are registered as a resident in Japan, premiums continue while you are away. Your Japanese card cannot be used for treatment in your home country (under some conditions part of the cost can be refunded).
What happens if I stop paying?
Your card can stop working, so you pay the full cost at the hospital, and late fees are added. Unpaid premiums are also checked when you renew your visa and can count against you. If money is tight, go to the city office and ask about a reduction instead of ignoring the bills.
Quick summary
- Staying over 3 months and not on company insurance → you must join
- Apply at your city office within 14 days
- Bring your residence card, passport, and My Number
- You then pay only 30% of medical costs
- Cannot pay? Ask about genmen – never just ignore it
- Unpaid premiums can affect your visa renewal
- You usually do not need private medical insurance: build savings for several months of living costs instead
Official sources: MHLW, co-payment rates by age / National Health Insurance Enforcement Regulations (e-Gov) / Nagoya City, joining and leaving NHI / Toshima City, National Health Insurance (English) / Toshima City, joining and leaving NHI (Japanese) / MHLW, My Number health card and eligibility certificate / Immigration Services Agency, guideline on extending your period of stay / Immigration Services Agency, permanent residence guidelines / MHLW, high-cost medical expense revision from August 2026 / Kyokai Kenpo, FY2026 rates by prefecture / MHLW, National Health Insurance (checked 30 September 2026) / Kyokai Kenpo, sickness and injury allowance / National Health Insurance Act (e-Gov) / MHLW, changes from April 2023 (childbirth lump sum) / MHLW, childbirth costs / Kyokai Kenpo, childbirth lump sum / Kyokai Kenpo, overseas medical expenses / Minato City, overseas medical expenses / Minato City, what NHI does not cover (checked 18 October 2026) Check premiums and procedures on your own city’s official website.
Related guides
If this helped, please share it with a friend who has just arrived. Most people learn these rules only after they have already lost money.
Found this useful? Share it
Send it to a friend who lives in Japan.
WHO WROTE THIS
mori
Japanese. I read the ministries’ own notices, orders and Q&As in the original, and I start from what my Nepalese and Sri Lankan friends in Japan actually ran into. I do not write about what I have not checked or been told.
What this site can and cannot do →Looking for something else?
You may use the figures in this article, including commercially, if you credit this site with a link. How to use our figures