Checked on 24 September 2026 against the Fire Liability Act, the Civil Code and the Act on Land and Building Leases (e-Gov), the Ministry of Land, Infrastructure, Transport and Tourism’s tenancy casebook and standard lease, the Supreme Court’s judgment of 15 July 2011 (courts.go.jp), and official pages from UR and the Ministry of Finance.
The short answer
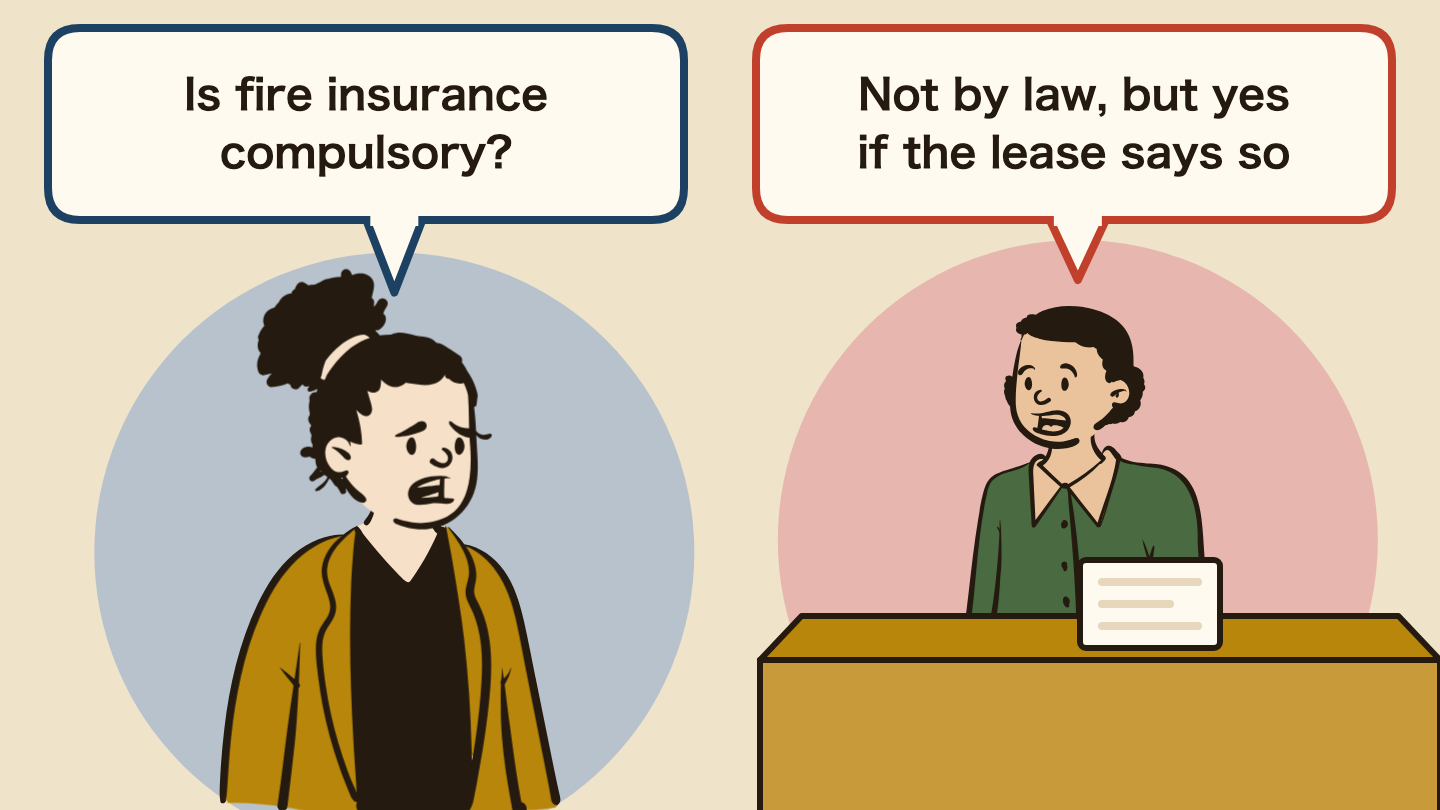
- You are asked for fire insurance because, if a fire starts in your flat, you still owe the landlord for the damage. If you heat with kerosene in winter, learn the safe refuelling routine first. Japan’s Fire Liability Act usually spares you from paying the neighbours, but not the landlord. Tenant’s liability cover is what pays that bill.
- The reverse is also true: if fire spreads from next door and burns your things, you cannot claim from the neighbour unless they were grossly negligent. Only your own contents insurance pays for your belongings.
- No law makes renters insurance compulsory. But if the lease makes it a condition, you sign on the basis that you will take it out (Ministry of Land, Infrastructure, Transport and Tourism). If a policy you already hold covers it, raise that with the agency before you sign.
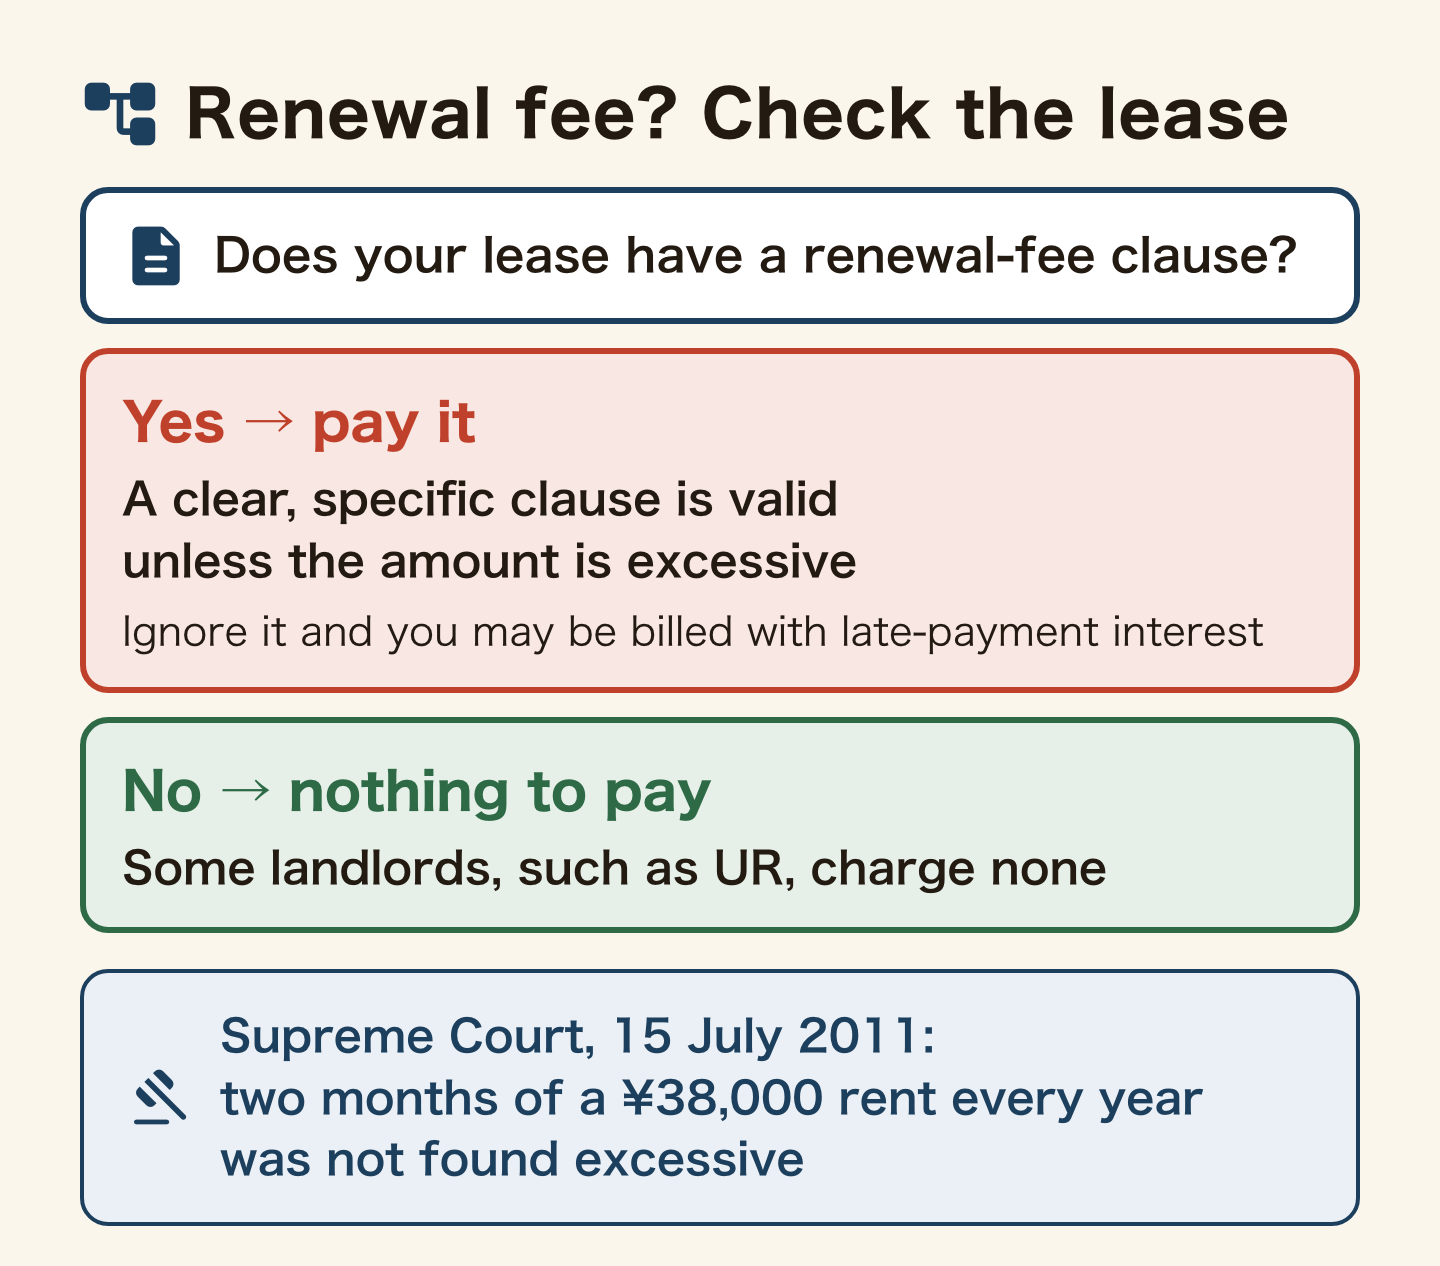
- The renewal fee (kōshinryō) is money you pay the landlord when the lease is renewed. No law creates it; you owe it only if your contract says so. In 2011 the Supreme Court held that a clearly written renewal fee is valid unless it is excessive.
- A fixed-term lease has no renewal at all. To stay on, you and the landlord sign a new lease.
Knowing this, you can read the insurance form on move-in day and the renewal bill two years later and know exactly what to check and what to ask. Once you know why each charge exists, you can tell which ones are optional and which ones will come back to bite you.
The day before you get the keys, the agency lays out the paperwork: the lease, the guarantor company form, and a fire insurance application. You ask a Japanese friend why a tenant needs fire insurance on a flat they do not own. “Everyone just gets it,” they say. Two years later a bill arrives for something called a renewal fee — money for simply staying where you are. In many countries there is no such thing.
- Why do renters in Japan need fire insurance?
- What does renters insurance in Japan cover?
- Do I have to take the insurance the agency chooses?
- What if I don’t get renters insurance?
- What is the renewal fee in Japan, and do I have to pay it?
- What else do you pay at renewal?
- Can my landlord refuse to renew?
- Fixed-term lease vs standard lease in Japan
- What if you cannot pay the renewal fee, or think it is too high?
- Which one are you?
- FAQ
- Summary
- Related reading
Why do renters in Japan need fire insurance?
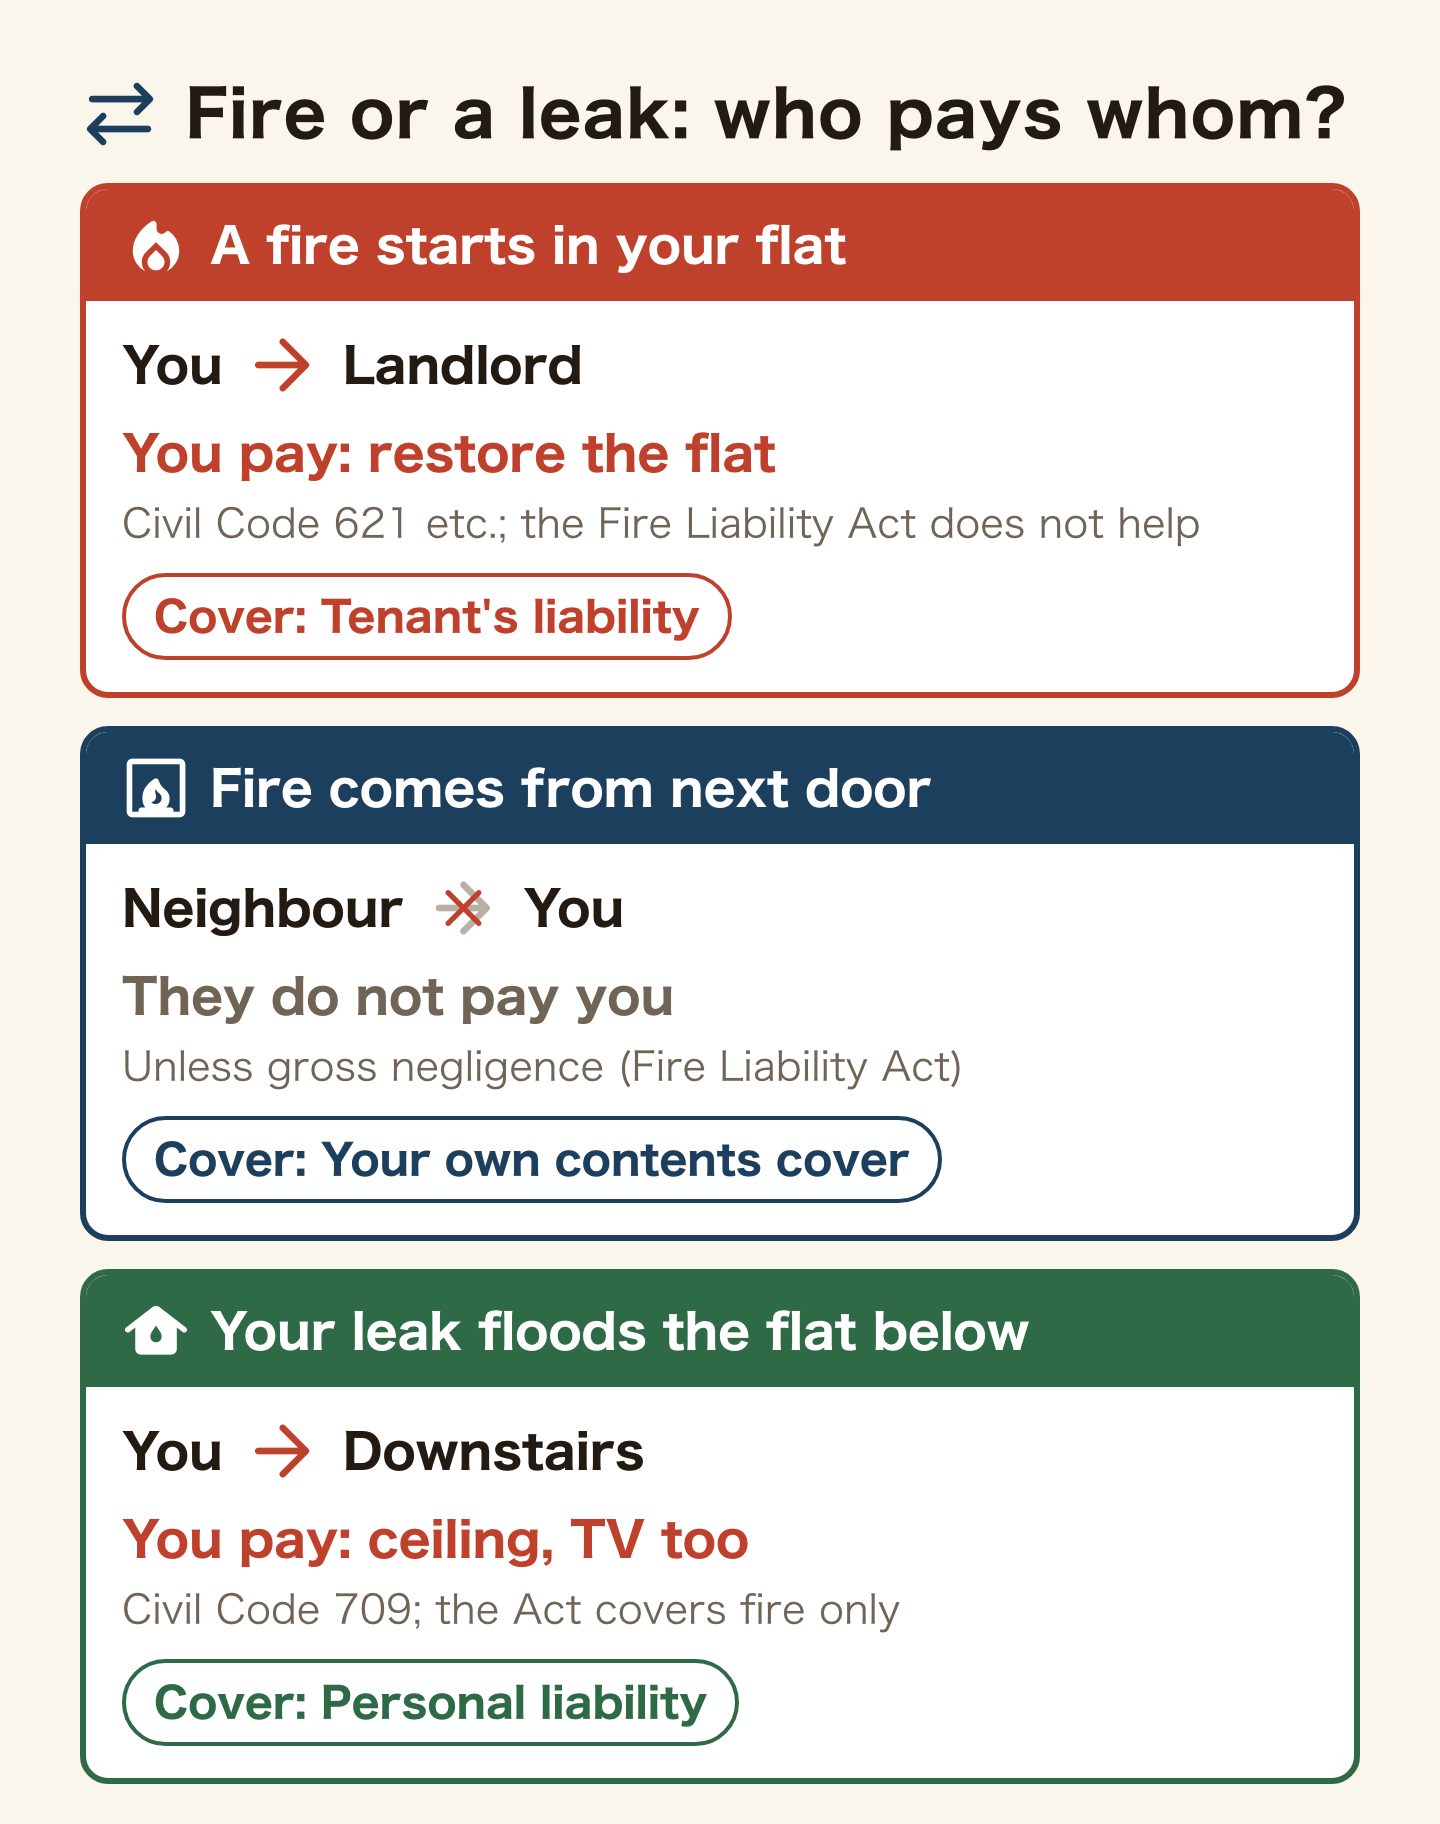
Japan has a one-sentence law from 1899, the Act on Liability for Fire Caused by Negligence, usually called the Fire Liability Act. It says that the Civil Code’s general rule on compensation for wrongful acts (Article 709) does not apply to accidental fires, unless the person who started the fire was grossly negligent. In practice, someone who accidentally starts a fire does not normally have to compensate the neighbours.
But that law only switches off Article 709. Between you and your landlord there is a separate thing: the lease. Under the Civil Code, a tenant promises to give the property back when the lease ends (Article 601), must look after it with due care until then (Article 400), and must restore damage that is the tenant’s fault (Article 621). Break those promises and you pay damages under the contract (Article 415).
So if a fire starts in your flat, you may owe the neighbours nothing, but you still owe your landlord for the damaged flat. UR, the public housing agency, explains it the same way: a tenant who starts a fire is liable to the landlord through the duty to restore the property. That is the risk the insurance at move-in is there to cover.
What does renters insurance in Japan cover?
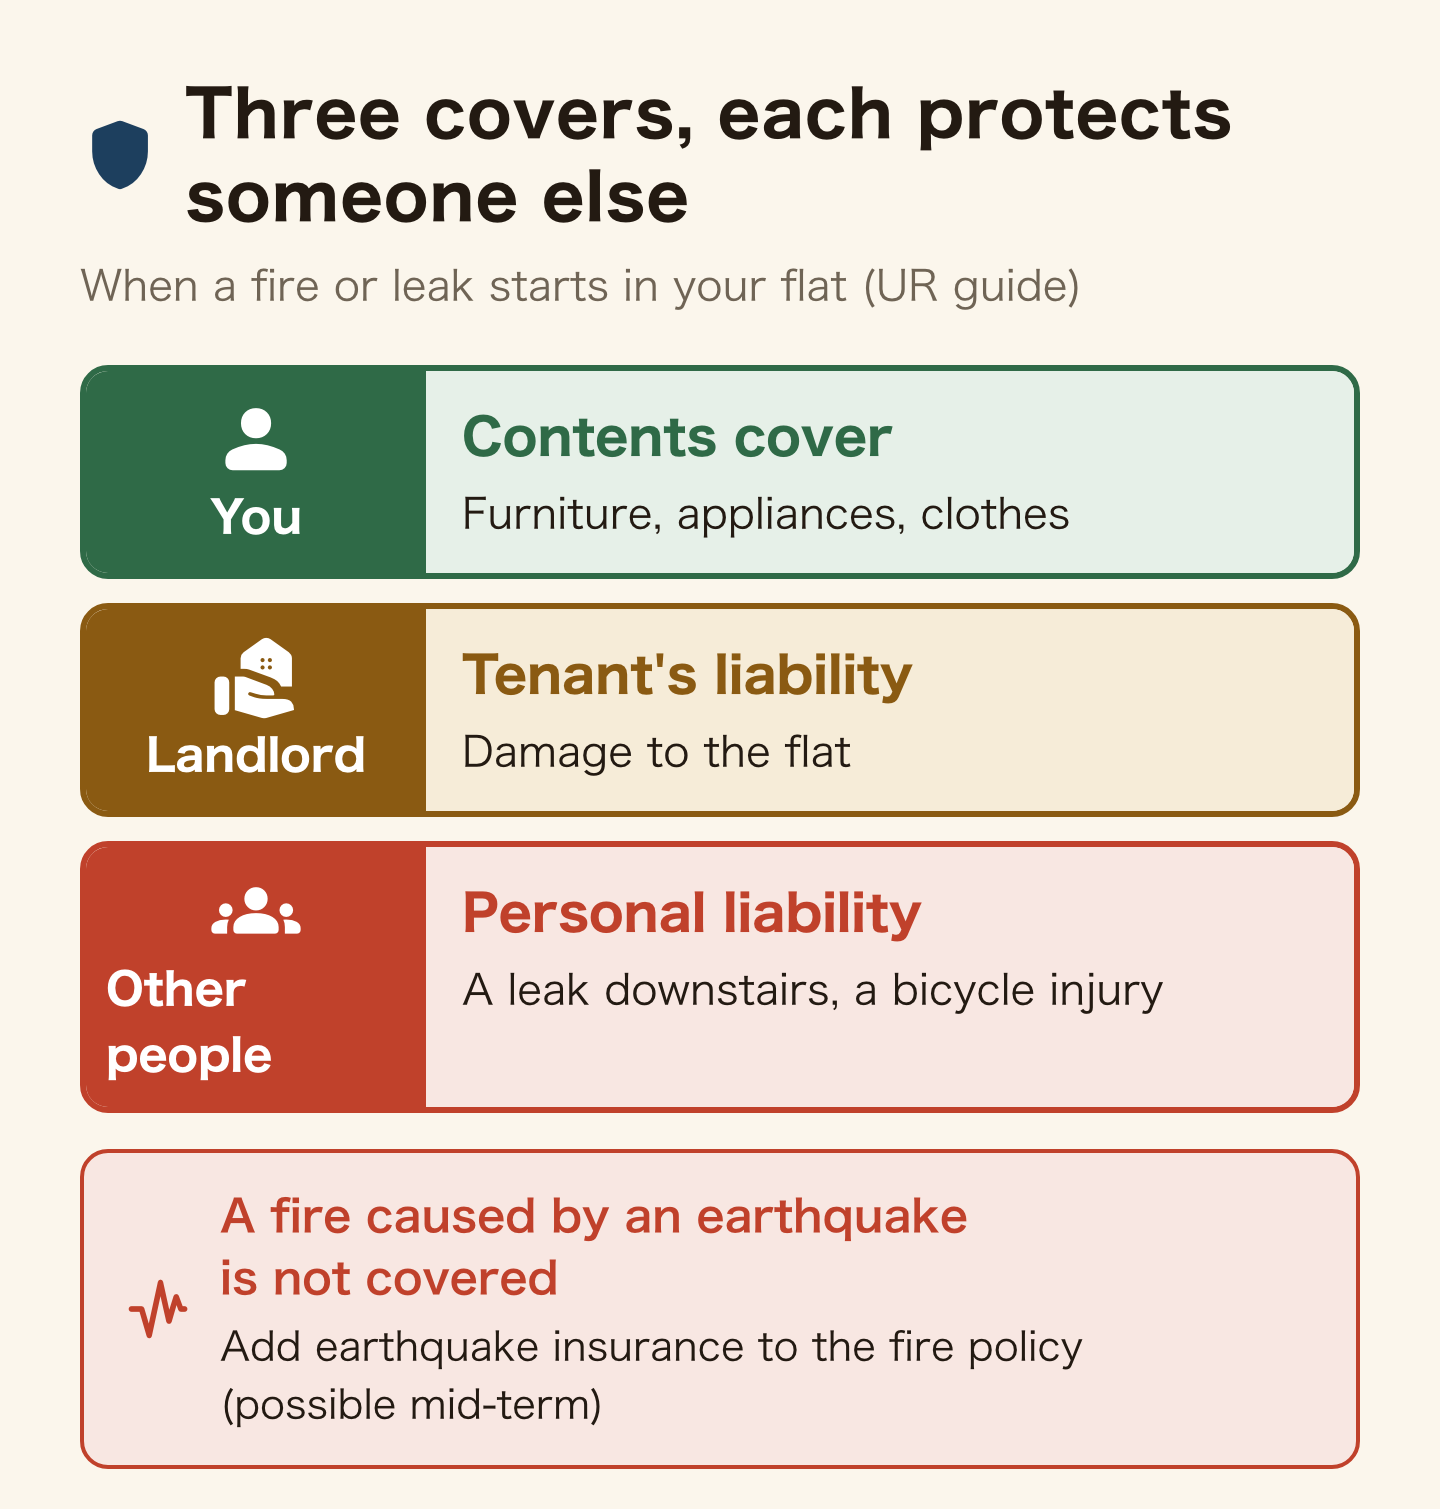
What the agency calls “fire insurance” is really a bundle. UR describes the standard set for tenants as three parts.
- Contents cover (kazai hoken): your furniture, appliances and clothes. Fire, and on some policies water damage and theft
- Tenant’s liability cover (shakuyanin baishō sekinin): what you owe the landlord if fire or a leak damages the flat. It is a rider on fire insurance and cannot be bought on its own
- Personal liability cover (kojin baishō sekinin): damage you cause to other people, such as water leaking into the flat below or injuring someone on your bicycle. A university’s Gakkensai liability add-on only pays on the way to class, so this rider is what covers everyday bike accidents
Contents cover exists because of the other side of the Fire Liability Act. If fire from next door destroys your laptop and clothes, you cannot make the neighbour pay unless they were grossly negligent. The only way to get your own belongings back is your own policy.
Leaks are different. The Fire Liability Act is about fire only. The ministry’s tenancy casebook describes a tenant who left the bath running and flooded the flat below: they had to pay for the new ceiling downstairs and for the neighbour’s water-damaged TV, valued at the price of an equivalent used set.
If you find a leak, close the stop valve first, then call the management company. The longer you wait to report it, the harder it is to show whether age or use caused it.
One more gap: according to the Ministry of Finance, fire insurance does not cover a fire caused by an earthquake. For that you need earthquake insurance, which is attached to a fire insurance policy and can be added part-way through. What to do when the ground actually shakes is in our earthquake preparedness guide.
Water damage from typhoons and heavy rain depends on your own policy. What to do at each alert level is in our guide to typhoon alert levels.
Do I have to take the insurance the agency chooses?
The ministry’s casebook answers in two steps. First, taking out insurance “is not compulsory under any law”. Second, if the lease makes insurance a condition, you in principle sign on the understanding that you accept it.
What about the specific policy the agency hands you? The casebook covers someone who already had a mutual-aid policy covering fire and personal liability, but was told to join the agency’s chosen insurer. The answer: compare what your existing policy covers with the one specified, then discuss with the agency whether you really need the specified one. In the end, the contract is whatever the landlord and you agree.
UR’s guide says that as long as you meet the landlord’s conditions, the choice of insurer is yours. Those conditions are set in your lease, though. If you want to use your own policy, go in this order:
- Before signing, ask: “Can I use fire insurance I arrange myself?” (自分で入った火災保険でもいいですか)
- Get the required cover — especially the tenant’s liability amount — in writing or by email
- Hand over a copy of a policy that meets it
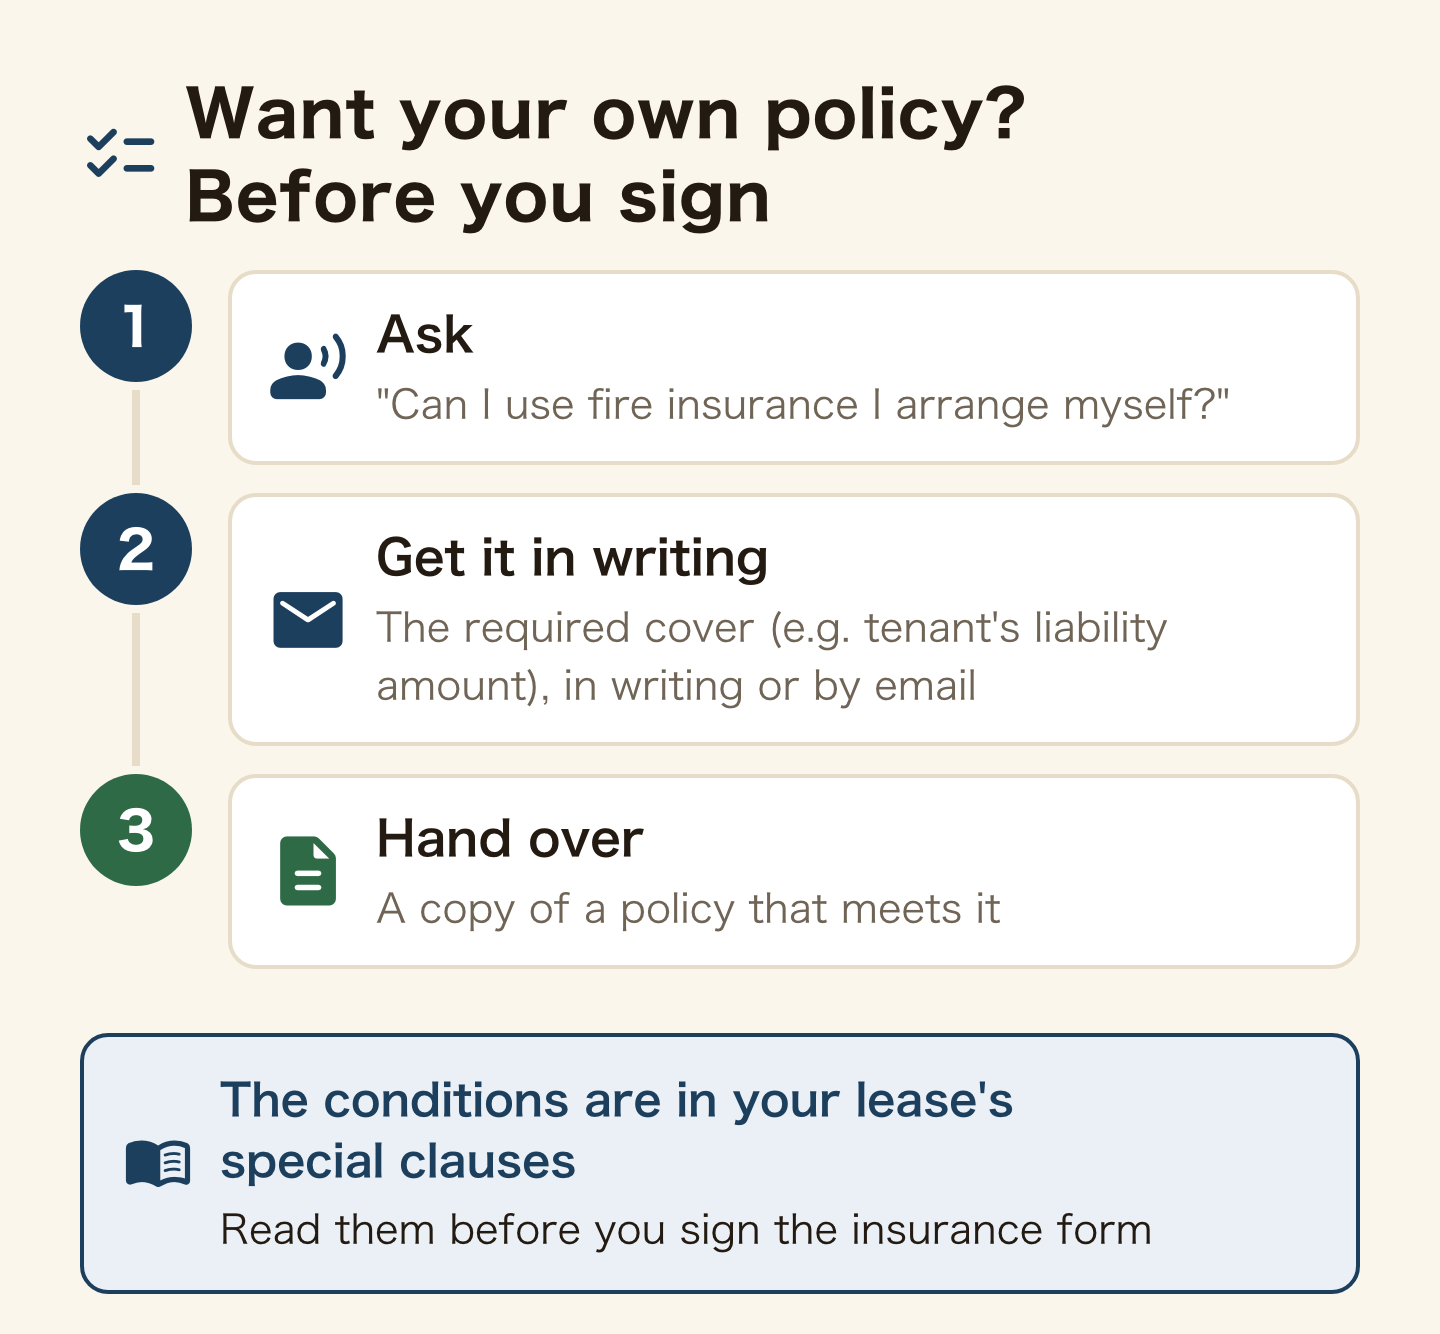
In the ministry’s model lease, insurance is not in the main clauses at all; it appears as an example of a special clause (tokuyaku). Whatever you are required to carry is written in the special-clauses section of your own lease. Read that part before you sign the insurance form.
What if I don’t get renters insurance?
If insurance is a condition of the lease, not having it means you are not meeting that condition. What a landlord or management company does about it depends on the contract and the situation; there is no single official answer.
The money side is clear, though. Insurance or no insurance, if a fire starts in your flat you still owe the landlord. Without a policy, that comes out of your own savings. The same goes for flooding the flat below.
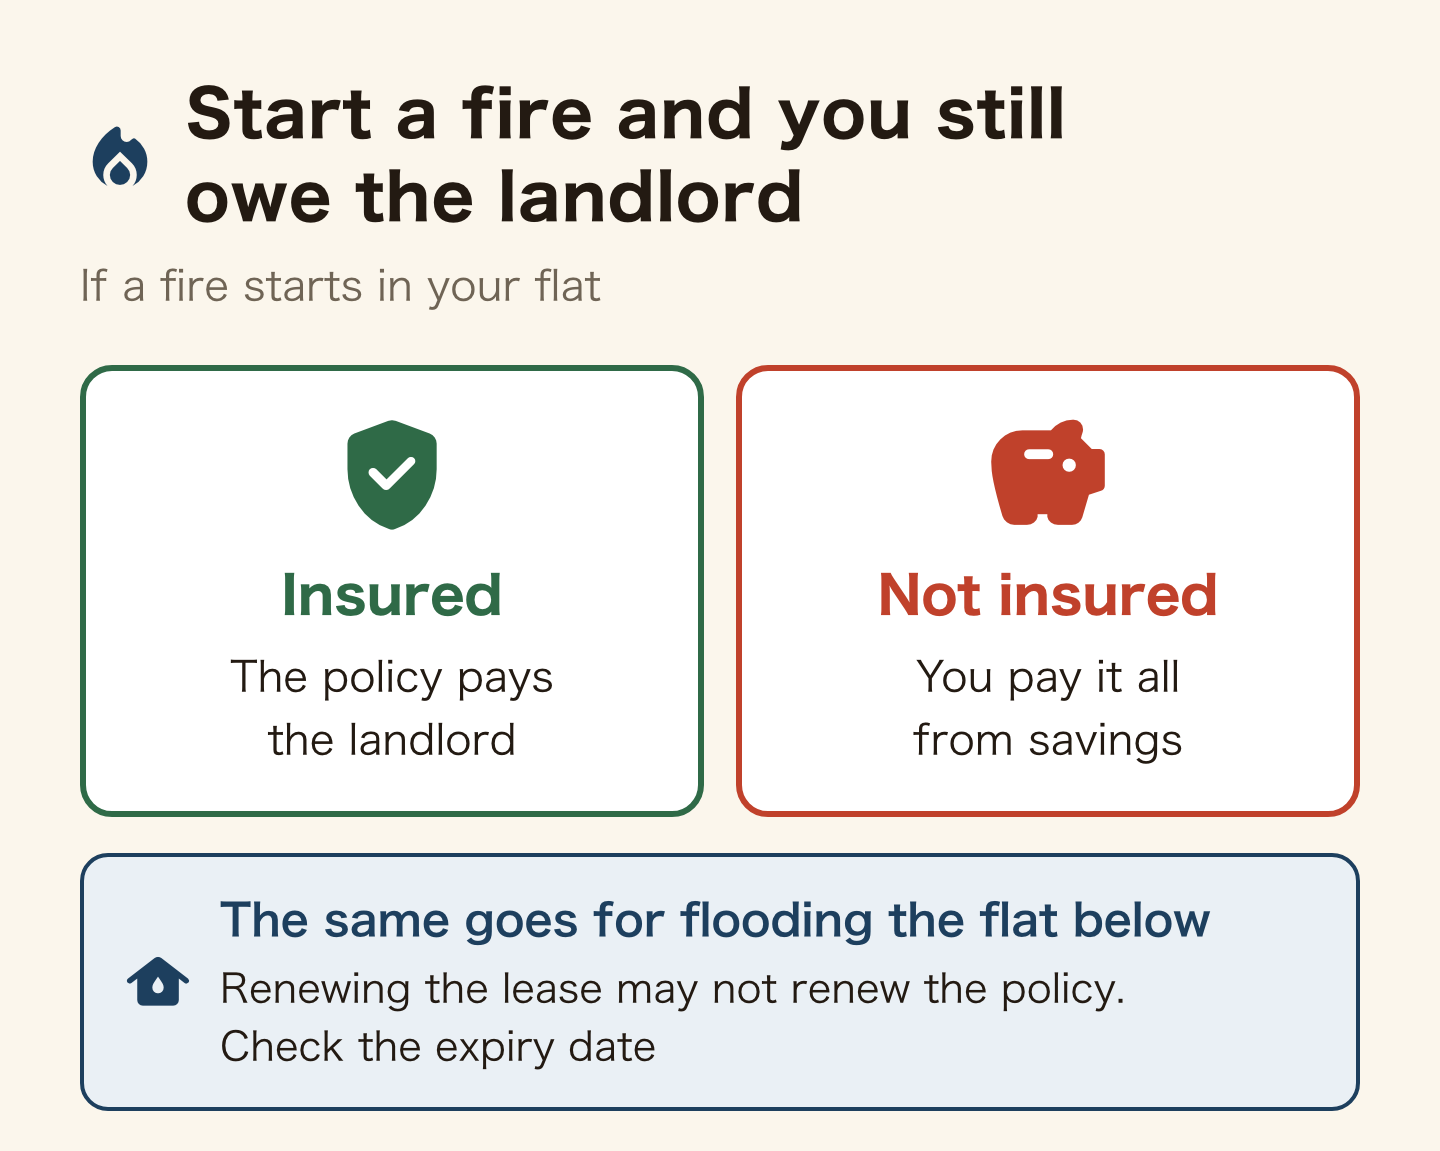
Watch the renewal date. UR’s guide points out that even when the insurance period matches the lease, the two contracts are not linked. Renewing the lease does not necessarily extend the insurance, so check the expiry date on your policy. When you move, cancel the old policy or move it to the new address, or you will pay twice.
What is the renewal fee in Japan, and do I have to pay it?
Two years in, you decide to stay in the same flat. Where you come from, extending a lease may cost nothing. In Japan, if your contract lists a renewal fee, you pay it to the landlord when the lease is renewed. Leave it unpaid because you are “only staying on”, and you may later be billed for it, plus interest for the delay.
The renewal fee is money the tenant pays the landlord when a lease reaches the end of its term and is renewed. The ministry’s casebook states that it has no basis in any statute and is not even a nationwide custom, which is why the government’s model lease contains no renewal-fee clause.
You pay it because your contract says so. Whether such clauses were valid was argued for years until the Supreme Court ruled on 15 July 2011.
The case involved a flat in Kyoto rented for ¥38,000 a month, with a clause requiring two months’ rent as a renewal fee every year. The court held that a renewal fee clause written clearly and specifically in the lease is valid, unless the amount is excessive in light of the rent and the renewal period. Even two months’ rent every year was not found excessive. The argument that it broke the tenant-protection rules of the Act on Land and Building Leases also failed.
That lease also said the fee was due “whether the lease is renewed by agreement or automatically”. The tenant had not paid the ¥76,000 fee for an automatic renewal; the court ordered payment plus late-payment interest. A fee written into your lease does not disappear if you simply ignore it.
If your lease has no renewal-fee clause, there is nothing to pay. Some landlords, UR among them, officially charge no renewal fee at all.
What else do you pay at renewal?
Renewal month can bring several bills at once. Separate them by who is asking and where the amount comes from.
| What | Paid to | Where the amount is written |
|---|---|---|
| Renewal fee | Landlord | Your lease (no legal cap) |
| Guarantor company renewal | Guarantor company | Your guarantee contract |
| Fire insurance renewal | Insurer | Your policy (expiry date and premium) |
The guarantee contract is separate from the lease. The ministry’s Q&A for registered rent-guarantee companies gives, as an example of a false explanation, telling a tenant “you are guaranteed for life” when the contract in fact needs a renewal fee. In other words, guarantee contracts can carry their own renewal fee. Registered guarantor companies must give you a written explanation before you sign, so the renewal timing and amount should be in that document. How guarantor companies work is covered in our guide to renting without a guarantor.
None of these has an official going rate. On renewal fees, the casebook says only that you should talk with the landlord, bearing in mind whether the amount is far out of line with local custom and local levels.
Can my landlord refuse to renew?
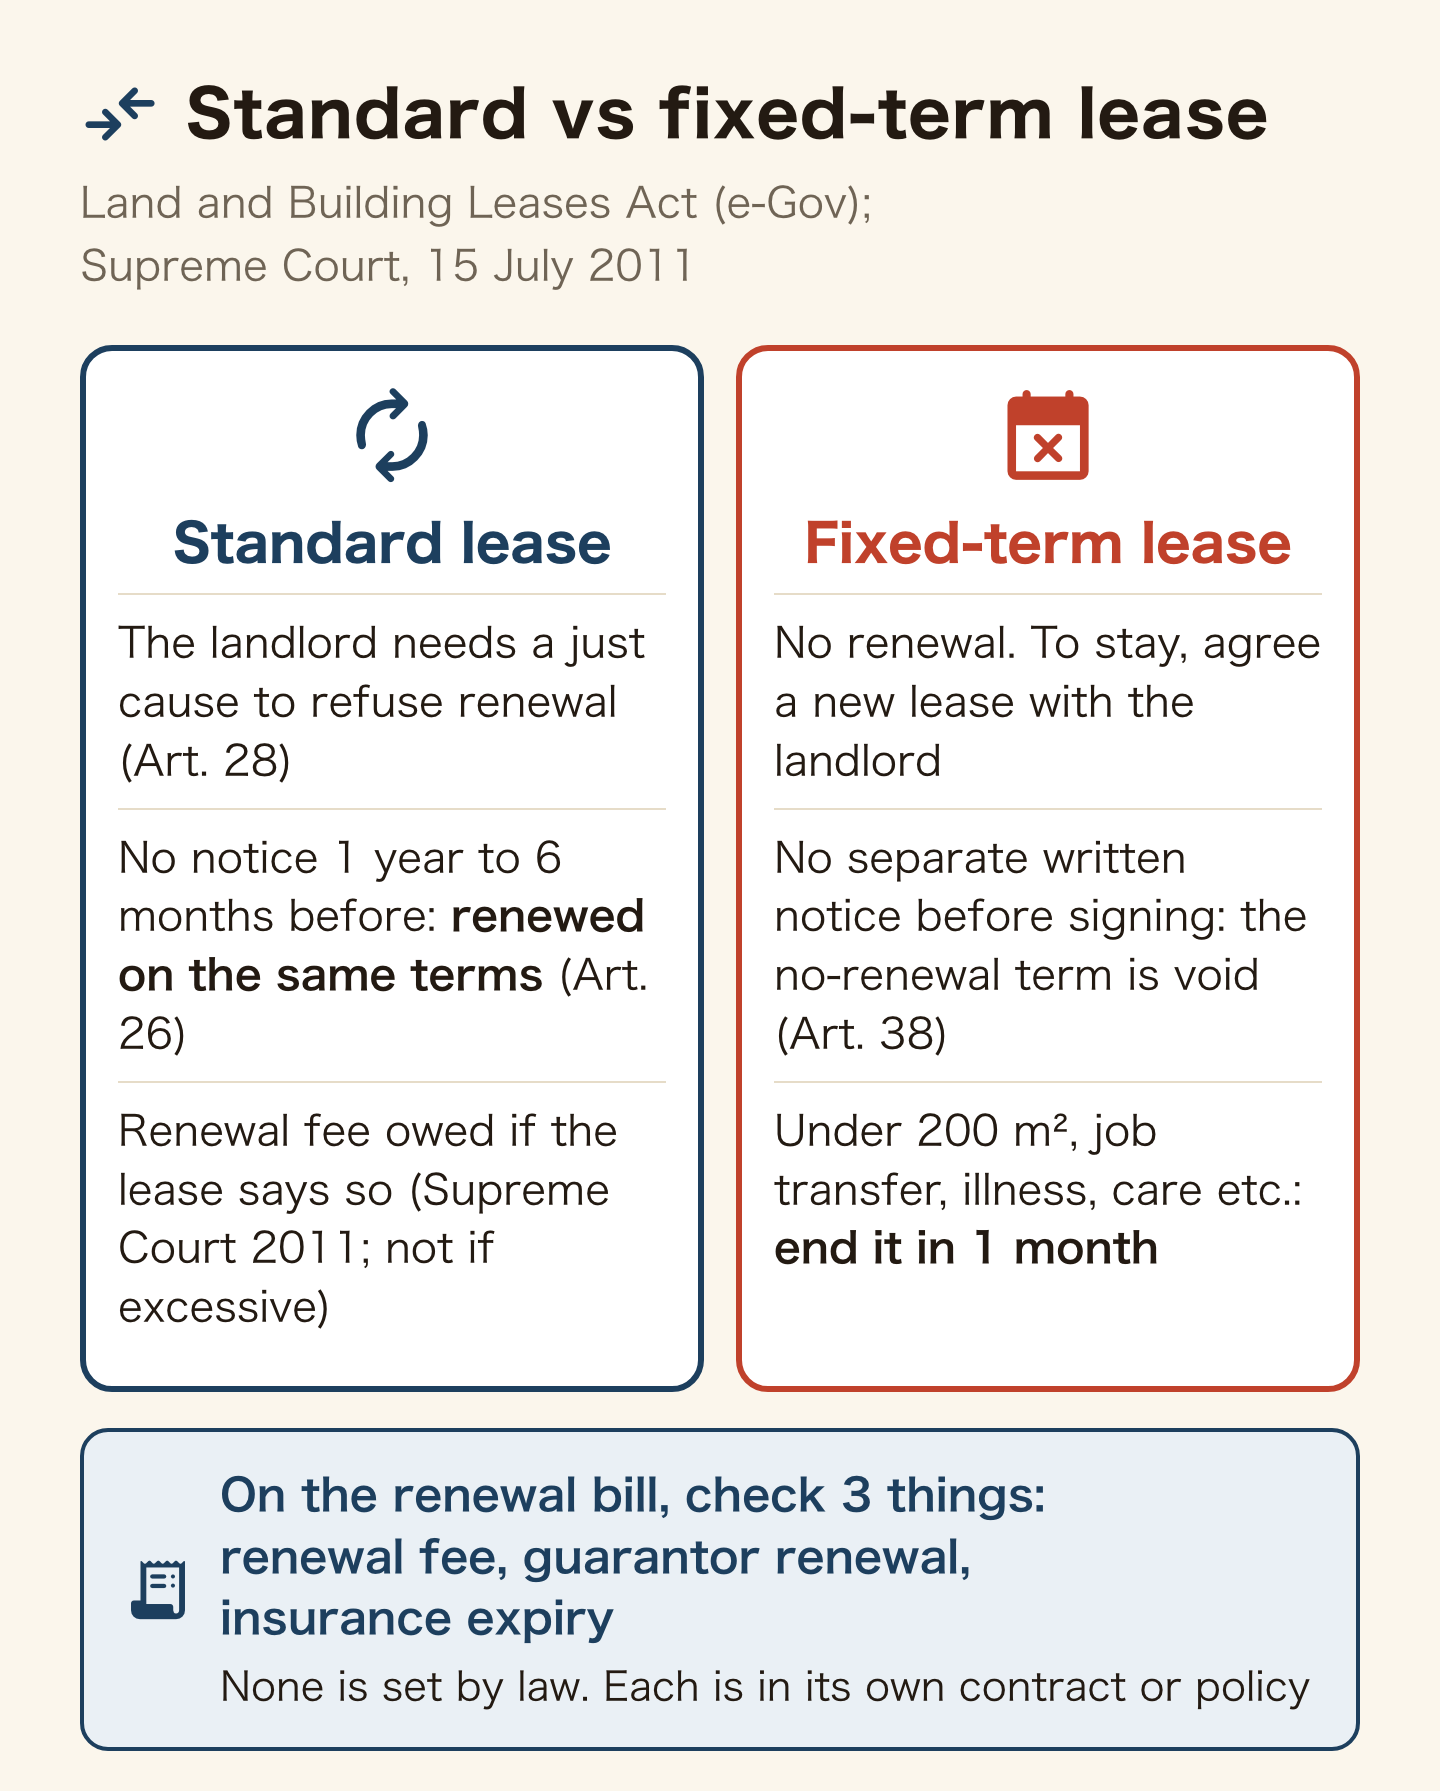
Under a standard lease (futsū shakka), which is what most tenants have, the landlord needs a “just cause” to refuse renewal (Act on Land and Building Leases, Article 28). That is weighed from both sides’ need for the property, the history of the tenancy, the state of the building and any offer of moving-out compensation.
If renewal talks go nowhere, you do not have to leave. Unless the landlord told you between one year and six months before the end of the term that the lease would not be renewed, it is treated as renewed on the same terms as before (Article 26). This is called statutory renewal, and the lease then has no fixed end date.
Sometimes the renewal paperwork quietly adds a condition that was not there before. The ministry’s casebook says renewal by agreement needs both sides to agree, so ask for an explanation of anything new and talk it through. If the change is a higher rent, see what to do about a rent increase.
Fixed-term lease vs standard lease in Japan
A fixed-term lease (teiki shakka) simply ends when its term is up, with no renewal (Article 38). To stay, you and the landlord must agree to a new lease, and the rent and other terms are set afresh.
In exchange, the landlord has rules to follow:
- The lease must be made in writing
- Before signing, the landlord must give you a written notice explaining that there is no renewal and the lease ends at the end of the term. That notice must be a separate document from the lease itself (Supreme Court, 13 September 2012, as cited in the ministry’s casebook)
- Without that explanation, the “no renewal” term is void
- For a term of one year or more, the landlord must tell you between one year and six months before the end that the lease is ending
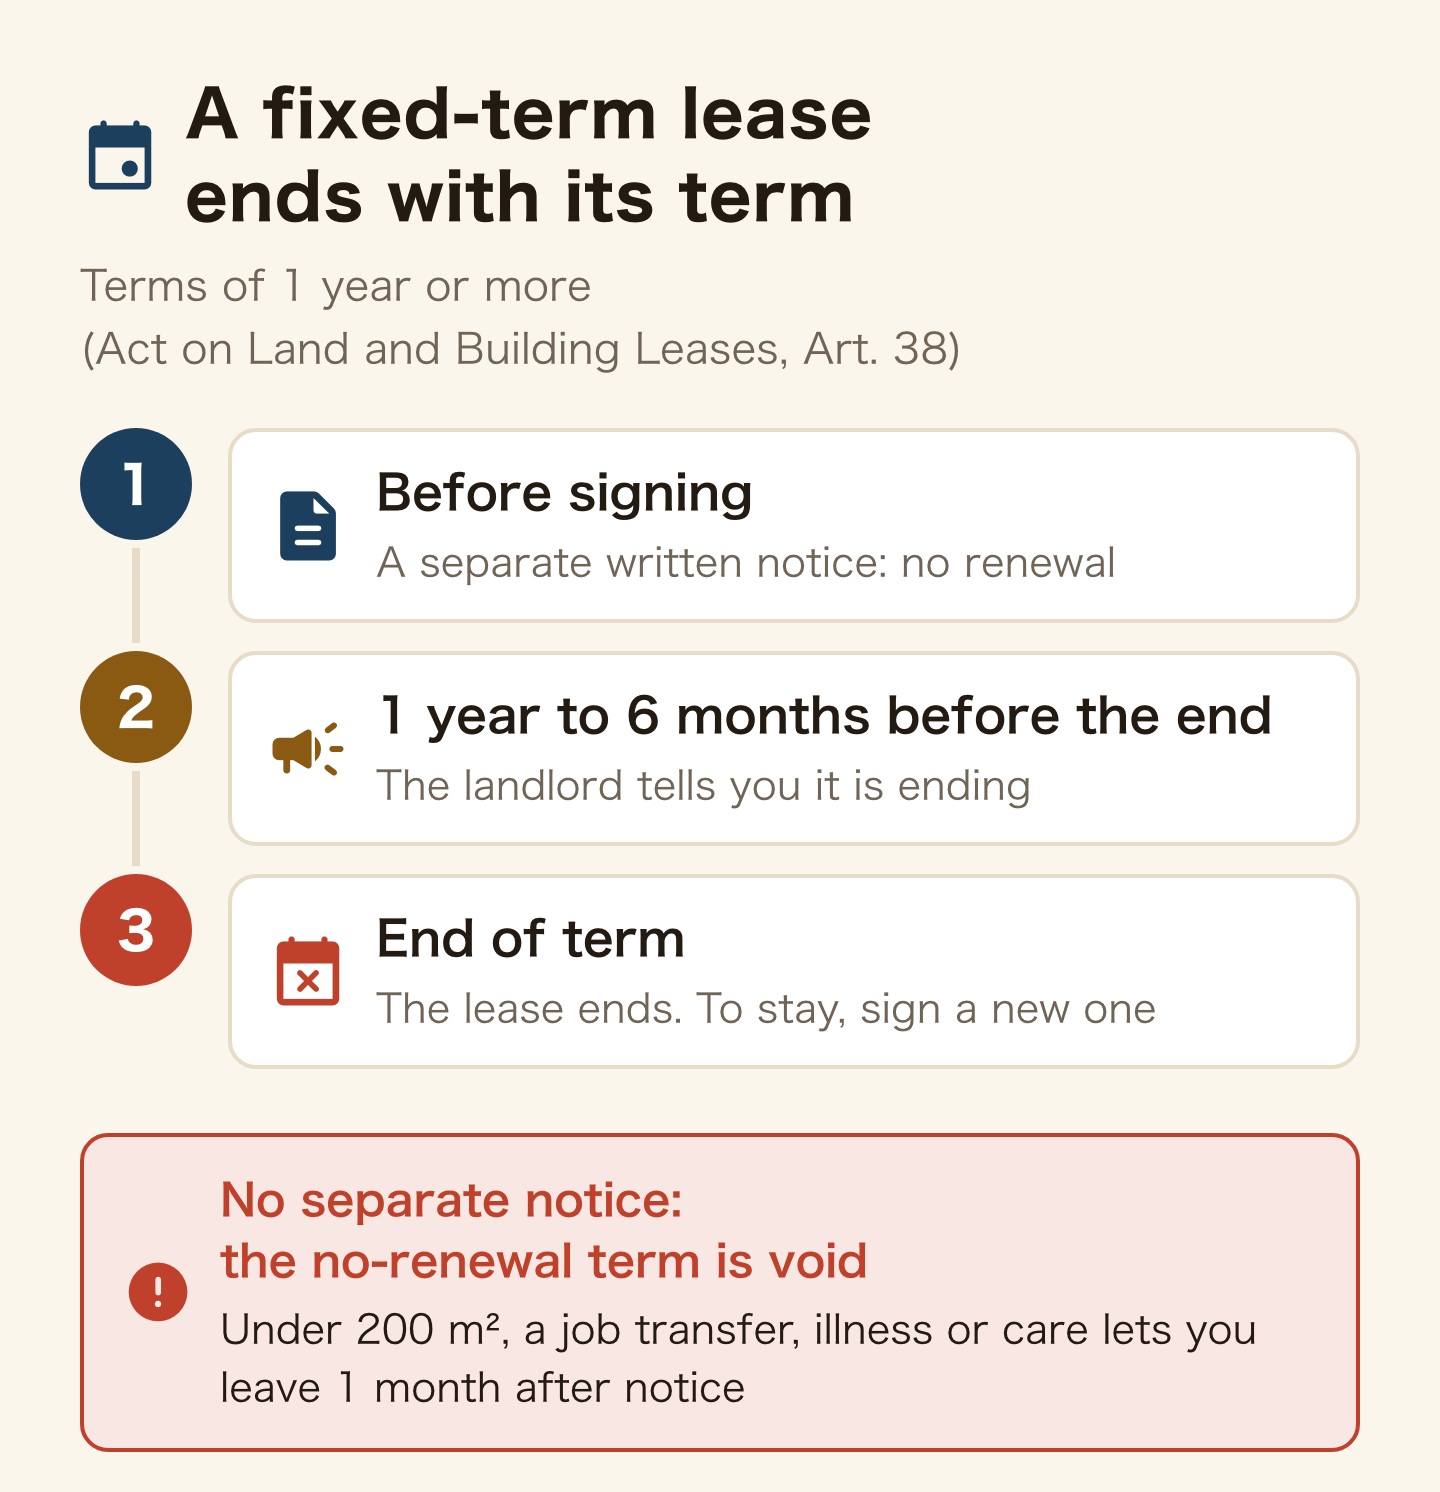
Leaving early has a rule too. For a home under 200 square metres, if a job transfer, medical treatment, caring for a relative or another unavoidable reason makes it hard to keep living there, you can give notice and the lease ends one month later. Any clause that is worse for you than this is void, so even a lease that says “no early termination” cannot stop you in those situations. The title of your lease and the separate notice you were given tell you which type you have.
What if you cannot pay the renewal fee, or think it is too high?
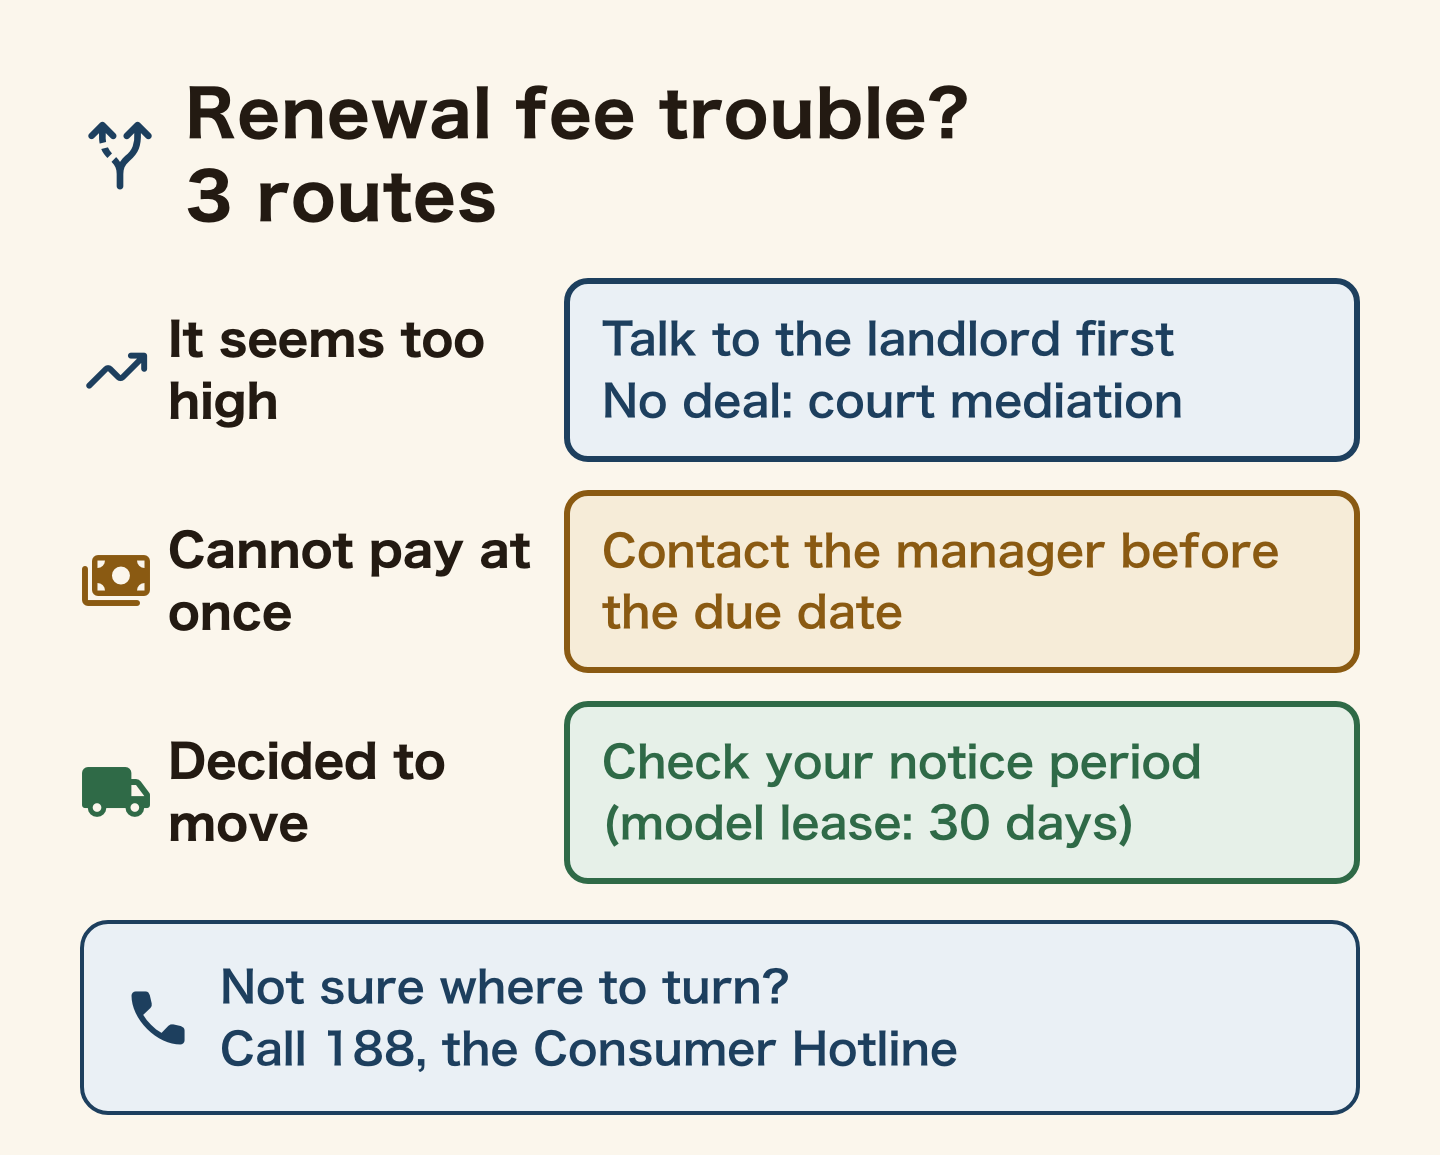
If the renewal fee seems excessive, the ministry’s casebook advises talking to the landlord first. If you cannot agree, court mediation (chōtei) is an option.
If you cannot pay it all at once, contact the management company before the due date. Leaving it unpaid can end the way the Supreme Court case did: a demand for the fee plus late-payment interest. If you do not know where to turn, dial 188, the Consumer Hotline, which connects you to your local consumer affairs centre.
Deciding to move out instead of renewing is also a valid answer. Under the government’s model lease, a tenant ends the lease with 30 days’ notice. Check the notice period in your own lease, then read what you really owe when you move out so the final bill does not cost you more than it should.
Which one are you?
- About to rent a flat — read the special clauses for whether insurance is required and what the renewal fee is. If you want your own policy, ask before you sign whether you can use it.
- Already living there, renewal coming up — take out the lease, the guarantee contract and the insurance policy, and write down each one’s renewal fee and expiry date.
- The renewal fee is too high, or you cannot pay it — contact the landlord or management company before the due date. If that goes nowhere, call 188 to find out where to get advice.
- On a fixed-term lease and need to leave early — check whether you have a job transfer, illness, care duties or a similar reason. If so, give notice and note the date one month later.
FAQ
Q. Is renters insurance mandatory in Japan?
No law requires it. But if your lease makes it a condition, you sign on the basis that you will take it out (Ministry of Land, Infrastructure, Transport and Tourism). Check the special-clauses section of your lease.
Q. If a fire next door burns my belongings, will the neighbour pay?
Not unless they were grossly negligent. Under the Fire Liability Act, you cannot claim compensation otherwise. Your own contents insurance is what covers your belongings.
Q. What is tenant’s liability insurance in Japan?
It covers what you owe the landlord if fire or a leak damages the flat you rent. The Fire Liability Act does not remove that duty to the landlord, which is why leases ask for it. It is a rider on fire insurance and cannot be bought on its own.
Q. Do I have to take the fire insurance the agency recommends?
If it is a condition of the lease, you basically need to, according to the ministry’s casebook. If you already have a policy, compare the cover and discuss with the agency before signing whether you still need the one they specify.
Q. Do I have to pay the renewal fee in Japan?
Yes, if your lease clearly says so. In its judgment of 15 July 2011, the Supreme Court held such fees valid unless the amount is excessive. If your lease has no renewal-fee clause, there is nothing to pay.
Q. What is the difference between a fixed-term lease and a standard lease?
Under a standard lease, the landlord cannot refuse renewal without a just cause. A fixed-term lease has no renewal and ends when its term is up; to stay you need a new lease. The landlord must also explain this in a separate written notice before you sign.
Summary
Renters insurance in Japan combines contents cover for your own things with liability cover for what you might owe the landlord or the people downstairs. The Fire Liability Act does not remove your duty to the landlord, which is why leases ask for tenant’s liability cover. No law makes insurance compulsory, but if your lease requires it you sign on that basis, and if you want your own policy you raise it before signing.
The renewal fee comes from the contract, not from any law. If it is clearly written in your lease and not excessive, you pay it. At renewal time, check three things separately: the landlord’s renewal fee, the guarantor company’s renewal and your insurance expiry date. On a fixed-term lease, there is no renewal — only a new lease.
Official sources: e-Gov, Act on Liability for Fire Caused by Negligence (Japanese) / e-Gov, Civil Code (Japanese) / e-Gov, Act on Land and Building Leases (Japanese) / MLIT, casebook on private rental housing consultations (Japanese) / MLIT, model rental housing lease (Japanese) / MLIT, rent-guarantor registration Q&A (Japanese) / Supreme Court judgment of 15 July 2011 (Japanese) / UR FAQ (Japanese) / UR, why tenants need fire insurance (Japanese) / Ministry of Finance, earthquake insurance (Japanese). Checked on 24 September 2026. Always confirm the insurance and renewal terms in your own lease and policy.
Related reading
Found this useful? Share it
Send it to a friend who lives in Japan.
WHO WROTE THIS
mori
Japanese. I read the ministries’ own notices, orders and Q&As in the original, and I start from what my Nepalese and Sri Lankan friends in Japan actually ran into. I do not write about what I have not checked or been told.
What this site can and cannot do →Looking for something else?
You may use the figures in this article, including commercially, if you credit this site with a link. How to use our figures