Last updated: October 2026 (based on the National Tax Agency Q&A, August 2026 revision) / This article contains affiliate links.
Figures, prices and terms were checked against the National Tax Agency’s Q&A on overseas dependents and Taxanswer No.1180 on 5 August 2026. The income limit, the specified relative special deduction and the resident tax amounts were checked on 8 October 2026 against Taxanswer No.1180 and No.1177, the Q&A (August 2026 revision) and Yokohama City’s page. They change — check the current terms yourself before you sign up or file anything.
Summary
- If you send money home, you can claim those family members as dependents and pay less Japanese tax. ¥380,000 per person is deducted from your income — ¥630,000 in some cases.
- The rules tightened in January 2023. Relatives aged 30 to 69 are now excluded by default.
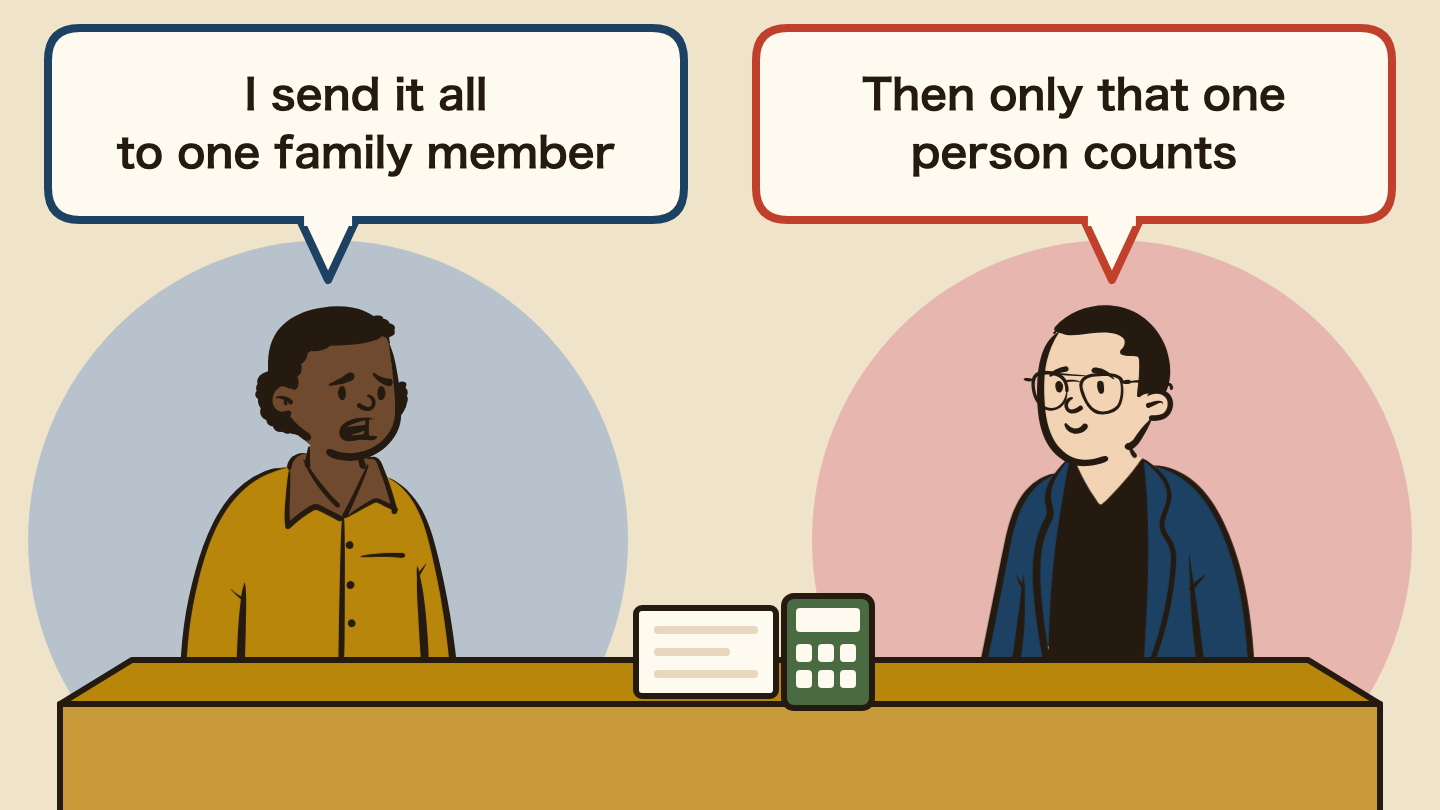
- The most common mistake is sending one lump sum to one person. If you do that, only that one person counts. You have to send separately to each family member.
- You need two things: proof of the family relationship and proof of the remittances. Documents in another language need a Japanese translation.
- Children under 16 do not qualify for the income tax deduction.
Knowing this, one change – sending to each family member separately – stops you losing a 380,000 yen deduction per person.
The dependent deduction (扶養控除 fuyō kōjo) reduces the income your Japanese tax is calculated on, when you are supporting family members. It works even when they live abroad. Company health insurance is a different system: since April 2020, family living abroad cannot, as a rule, be added (see dependent health insurance in Japan).
A lot of people send money home every month and never claim this. They simply do not know it exists, and they pay tax they did not have to pay.
How much it is worth
Per family member, this much comes off your income (amounts from National Tax Agency Taxanswer No.1180, in Japanese):
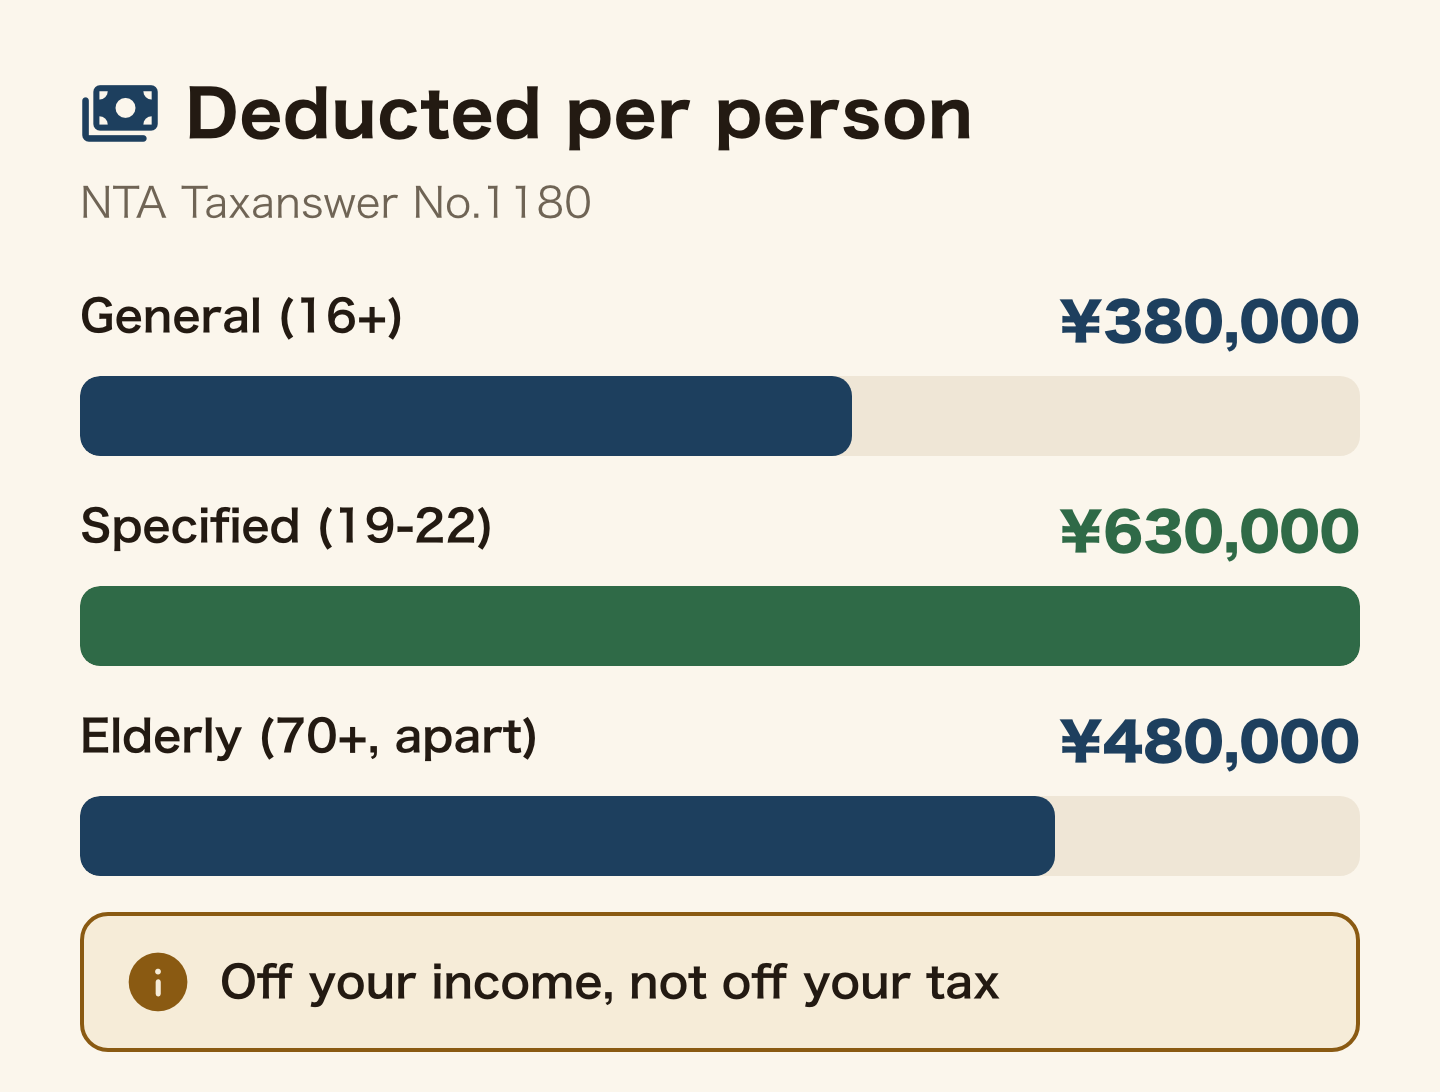
This does not mean your tax bill drops by ¥380,000. It means the amount your tax is calculated on drops by that much. See how income tax and resident tax work.
Your resident tax falls too, but by smaller amounts: resident tax deducts ¥330,000 for a general dependent, ¥450,000 for a specified dependent aged 19 to 22 and ¥380,000 for an elderly dependent aged 70 or over (Yokohama City: income deductions from FY2026, in Japanese). Still, with two or three family members the effect is not small.
The relative must share your household budget and have a total income of ¥580,000 or less for the year (¥620,000 or less from the 2026 tax year; Taxanswer No.1180). For the 2026 tax year, a relative aged 19 to 22 whose total income is above ¥620,000 but no more than ¥1,230,000 gets the specified relative special deduction (up to ¥630,000) instead (Taxanswer No.1177, in Japanese). Relatives living abroad can get it too, with relationship and remittance documents (Q1 and Q2 of the National Tax Agency Q&A on relatives living abroad, PDF in Japanese).
Since January 2023, age decides it
People are still filing based on the old rules.
A relative living abroad now qualifies only if one of these applies (same Taxanswer No.1180, rules from the 2023 tax year):
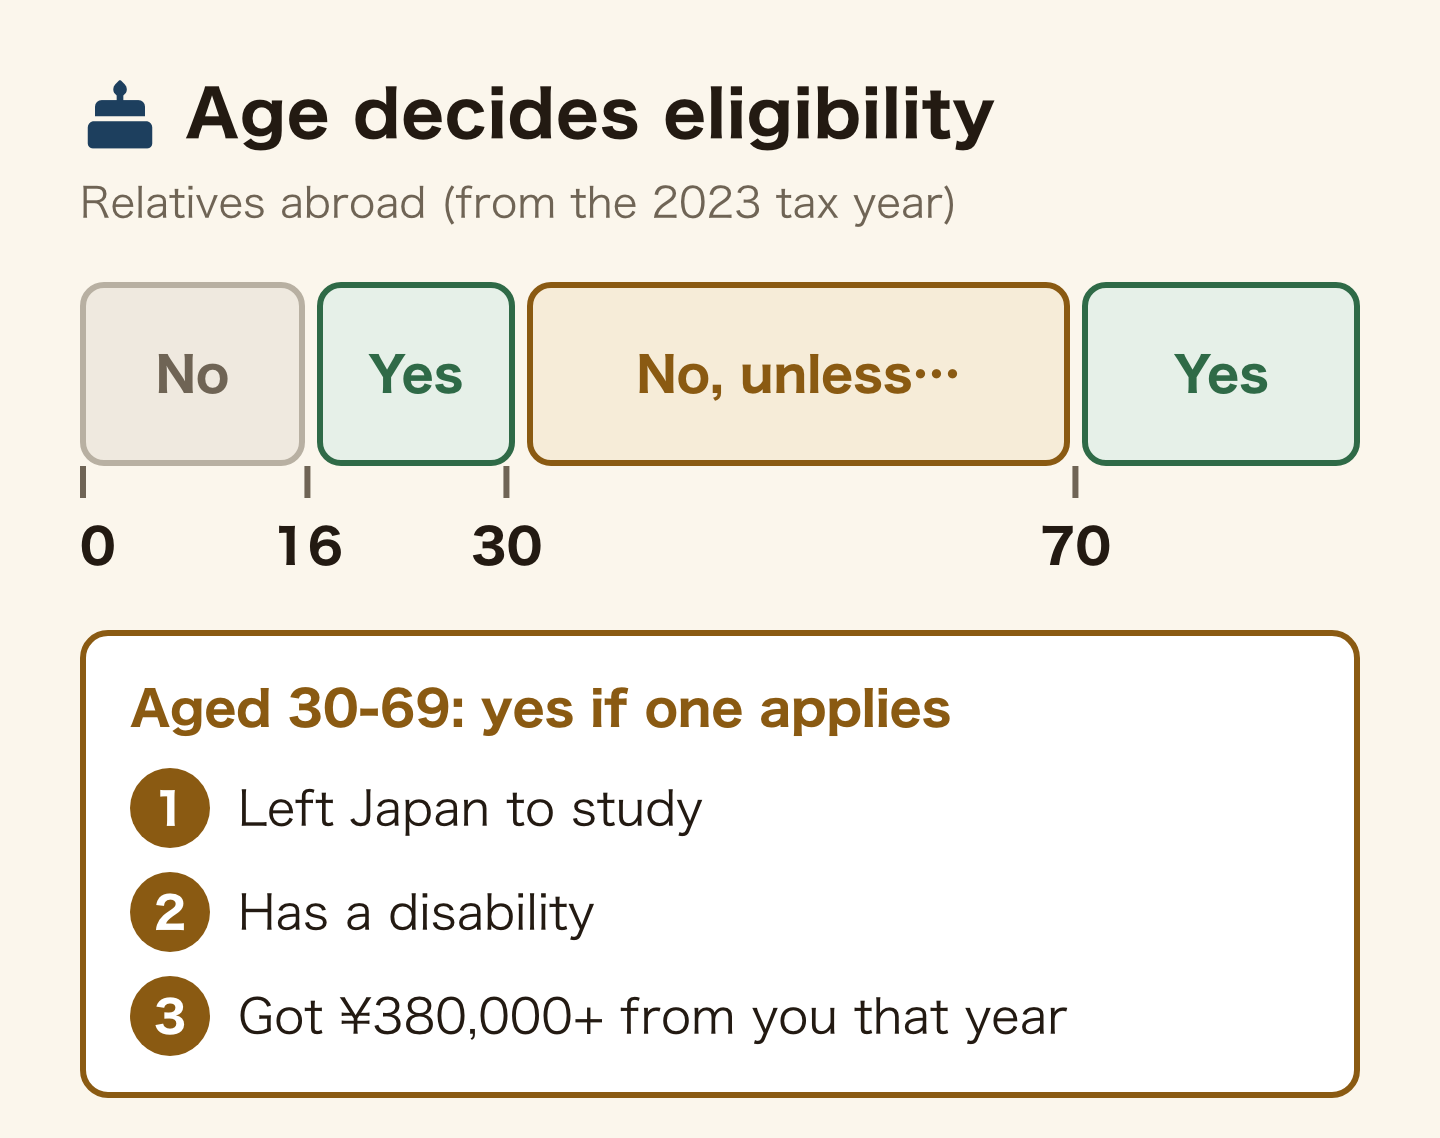
Age is counted as of 31 December of that year (Q4 of the National Tax Agency Q&A).
If you were claiming a brother or sister in their thirties or forties, that stops here. But option 3 keeps them in — send that person ¥380,000 or more during the year and they still qualify.
And a parent aged 70 or over needs none of the three extra conditions. The deduction rises to ¥480,000. A shared household budget, the income limit (¥580,000 or less for the year; ¥620,000 or less from 2026) and the documents still apply, as for any age.
The definition of “relative” is wide: blood relatives within six degrees, your spouse, and relatives by marriage within three degrees. Parents, children and siblings obviously — but also uncles, aunts, nephews and nieces. If you pay for a supported relative’s treatment, the same idea of sharing a household budget decides whether it goes into the medical expense deduction.
The mistake that costs the most: one lump sum
You send the money to one person at home, and the family shares it out from there. Where you come from, that may be the natural way family money moves. Japan’s dependent deduction does not look at how it was shared inside the house, only at whose name each transfer went to.
This is where people lose the deduction without realising it.
Say you want to claim three family members. Transfer fees are expensive, so you send everything to your father in one go. Reasonable. Very common.
Only your father counts.
The National Tax Agency puts it plainly: the remittance documents must show that you made payments for living or education expenses “as needed, to each person.” A transfer to one representative is a remittance document for that representative only — not for anyone else. This is Q10 and Q34 of its Q&A on deductions for relatives living abroad (PDF, in Japanese).
This page is about money you send out. If money comes the other way, from your family to you, gift tax can apply to the receiver. See our gift tax guide.
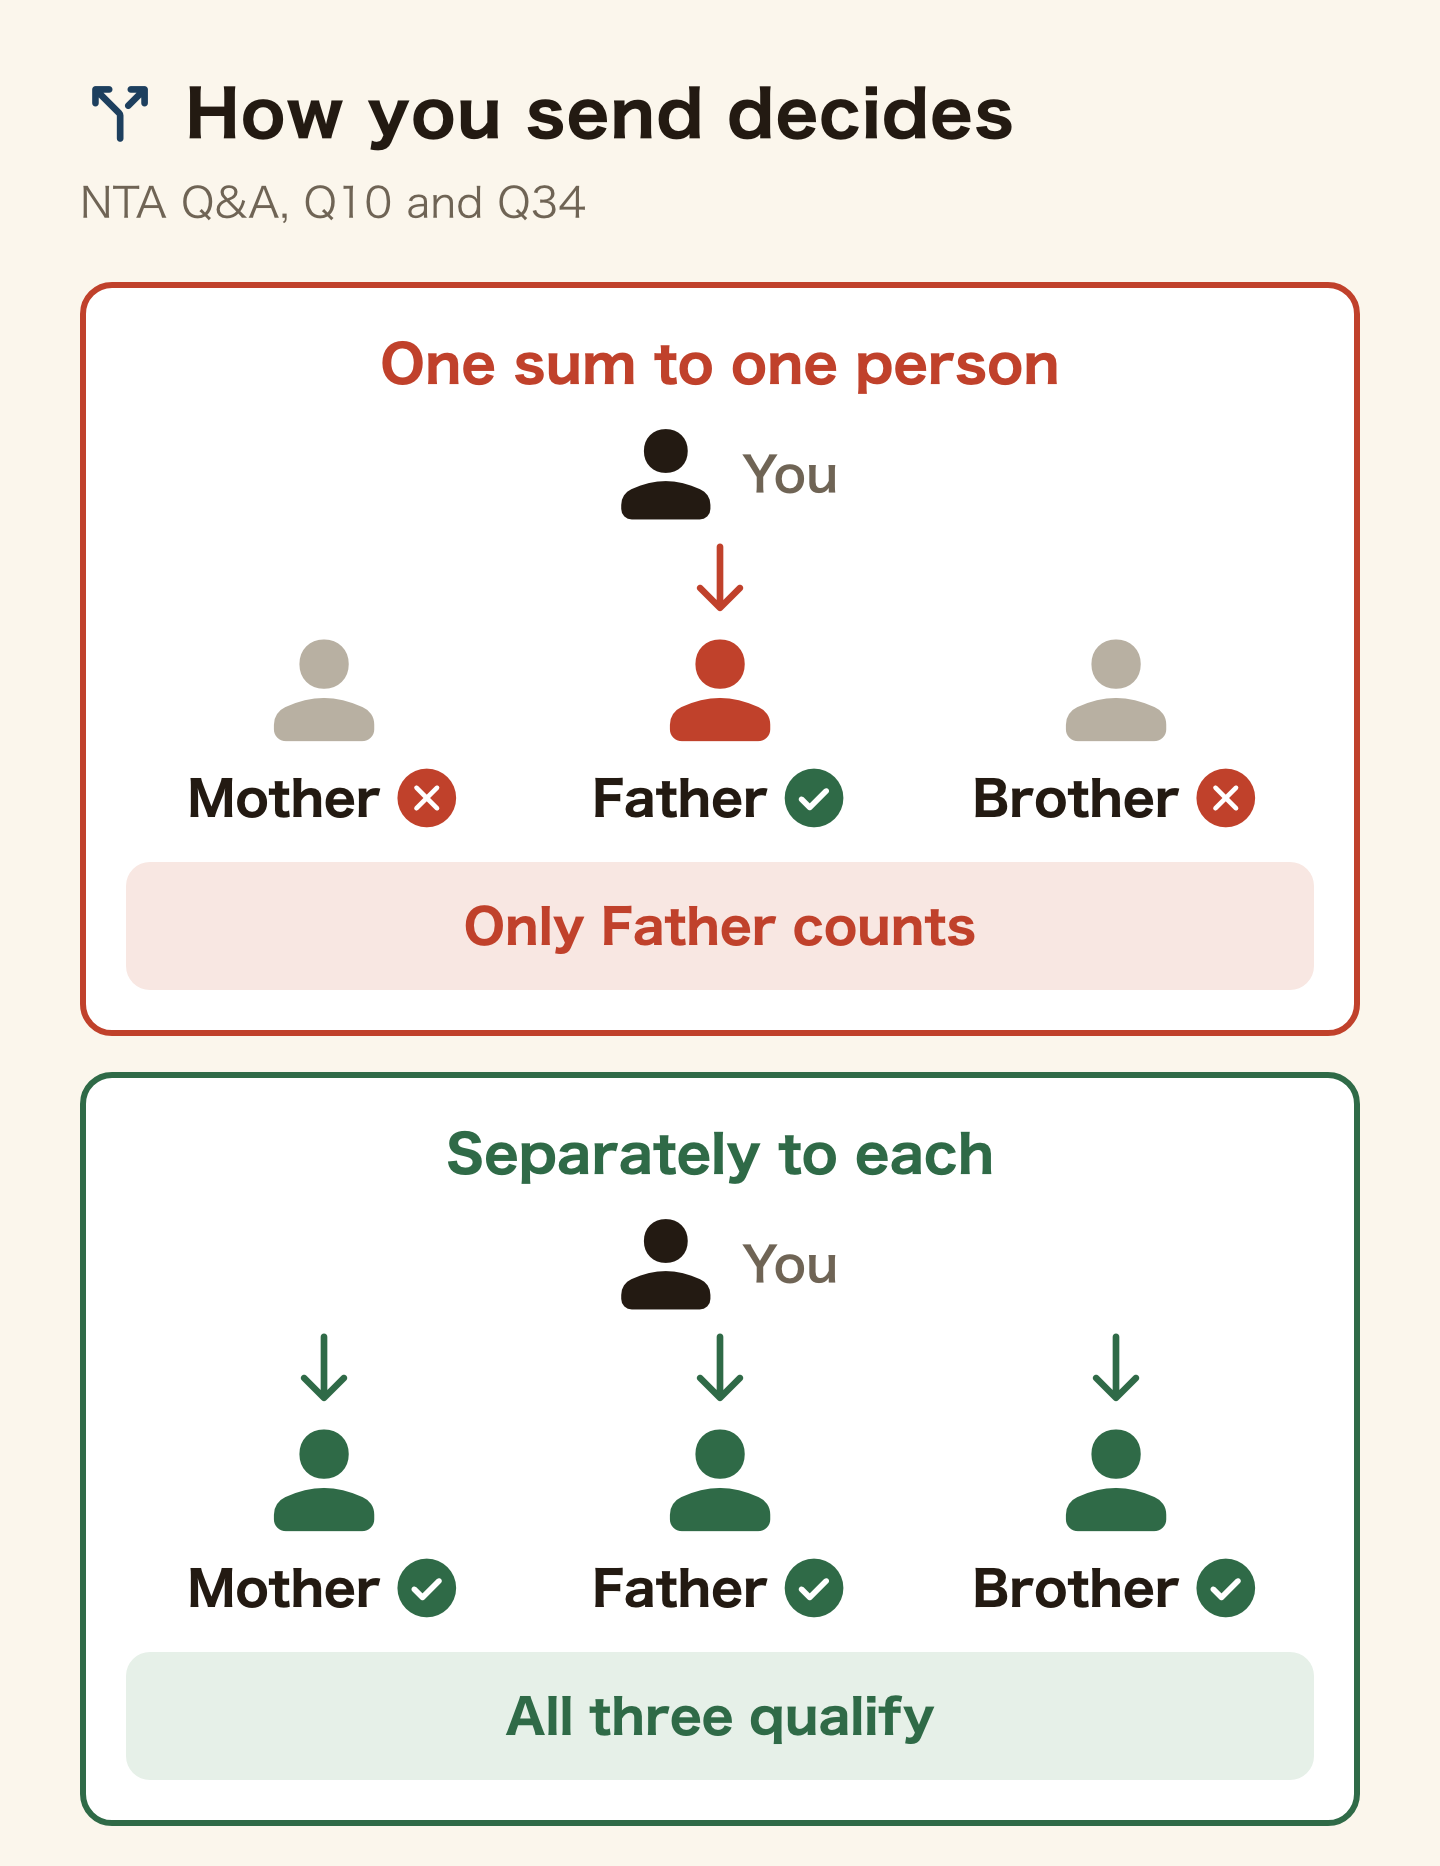
So split the transfers — one per person you want to claim. If your remittance service charges a lot per transfer, you will hesitate to do that. Cheap transfers are what make this deduction possible in practice.
Sending separately without losing money to fees
A bank counter transfer can cost several thousand yen each time, and splitting that across three people hurts. Wise is far cheaper and keeps a clear history of who received how much and when, which is exactly what you hand in at year-end. Full comparison in Sending money home from Japan.
You need exactly two kinds of document
Relationship documents and remittance documents. If you are an employee, you give them to your employer (National Tax Agency: deductions for relatives living abroad, in Japanese).
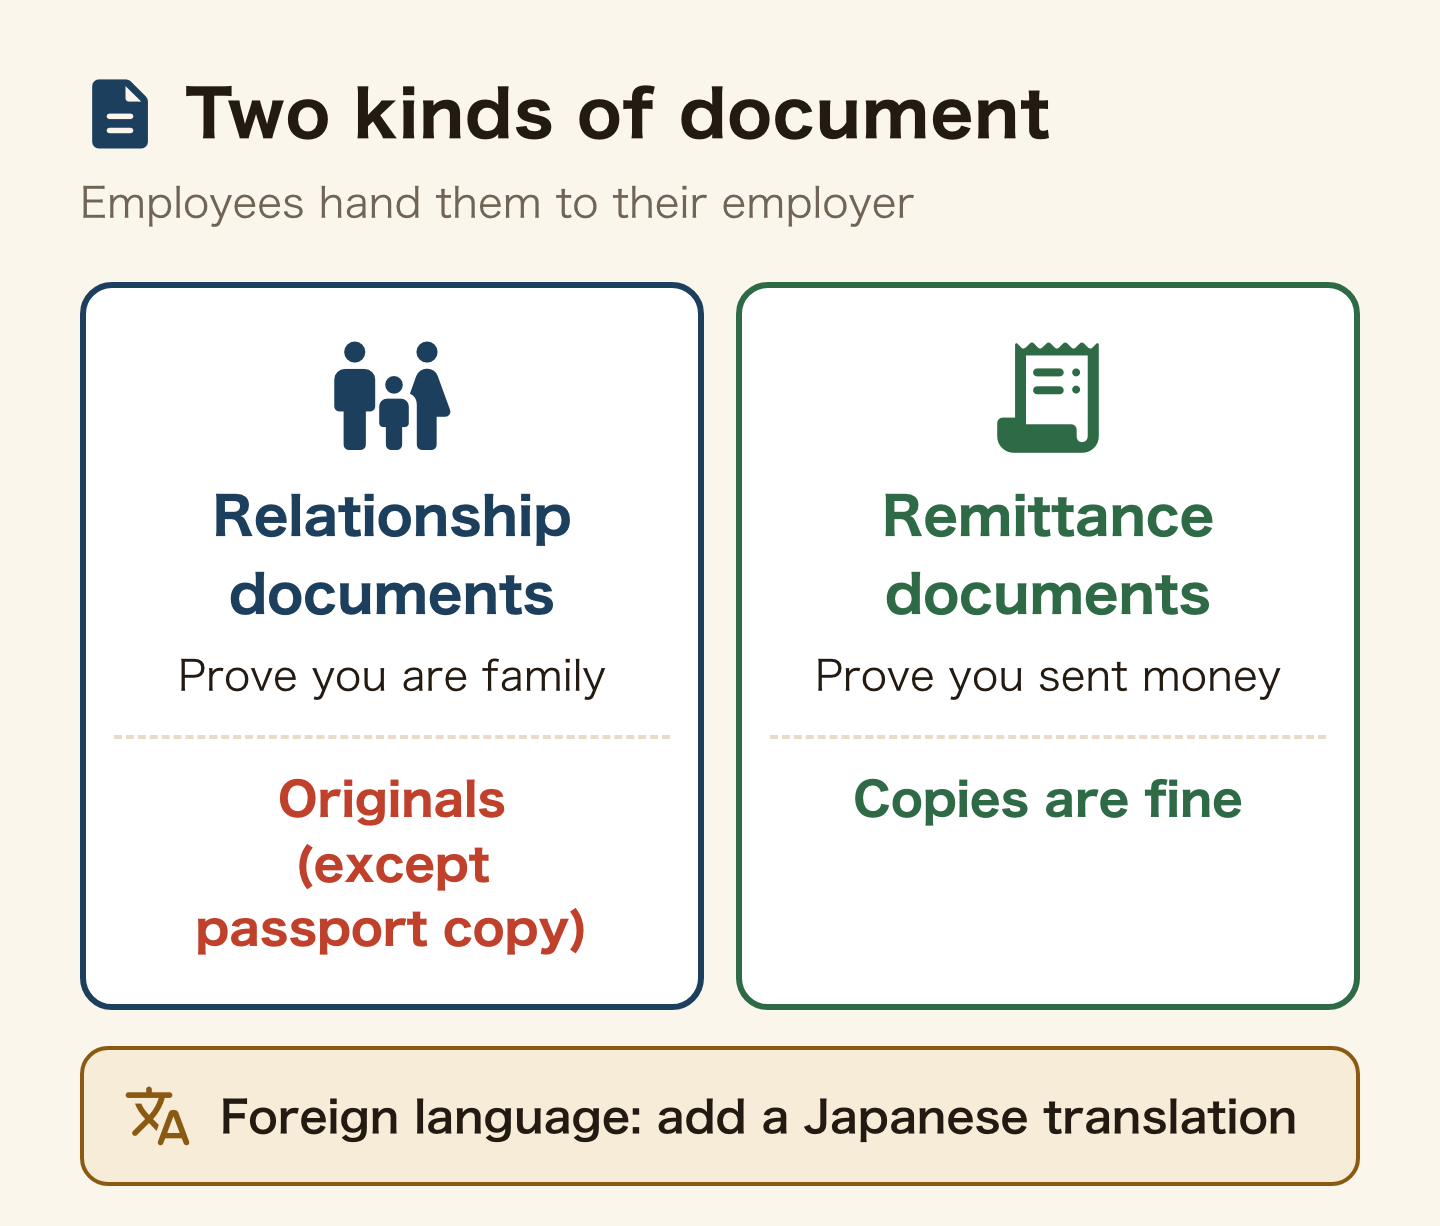
Relationship documents are either a document issued by a Japanese national or local government (such as a copy of the family register attachment) together with a copy of the relative’s passport, or a document issued by a foreign government or local authority showing the relative’s name, date of birth and address or residence. Originals are required, except for the passport copy. Remittance documents are records from a financial institution, a credit card company or an electronic payment provider, and copies are fine (Q8, Q10 and Q12 of the National Tax Agency Q&A).
The translation is what people forget. Handing over a birth certificate from your home country as-is will not work. Attach a Japanese translation. The National Tax Agency Q&A (Q14) says a translation is required but does not say who has to make it. Before you hand in your own translation, check with your employer or the tax office that it will be accepted.
If you are claiming someone aged 30 to 69 on the “¥380,000 or more” ground, what you need instead is a “¥380,000 remittance document” — records showing that that one person received at least ¥380,000 from you over the year. Again, per person.
When and where to submit
If you work for a company, you give everything to your employer, in two stages (National Tax Agency leaflet for employees, PDF in Japanese):
- When you submit the dependent declaration form (on joining, or at the start of the year) — relationship documents
- At year-end adjustment (around November–December) — remittance documents
Because the remittance records are handed in at the end of the year, you need a full year of them saved up. Realising this in January is too late. If you are sending money now, start keeping this year’s records today.
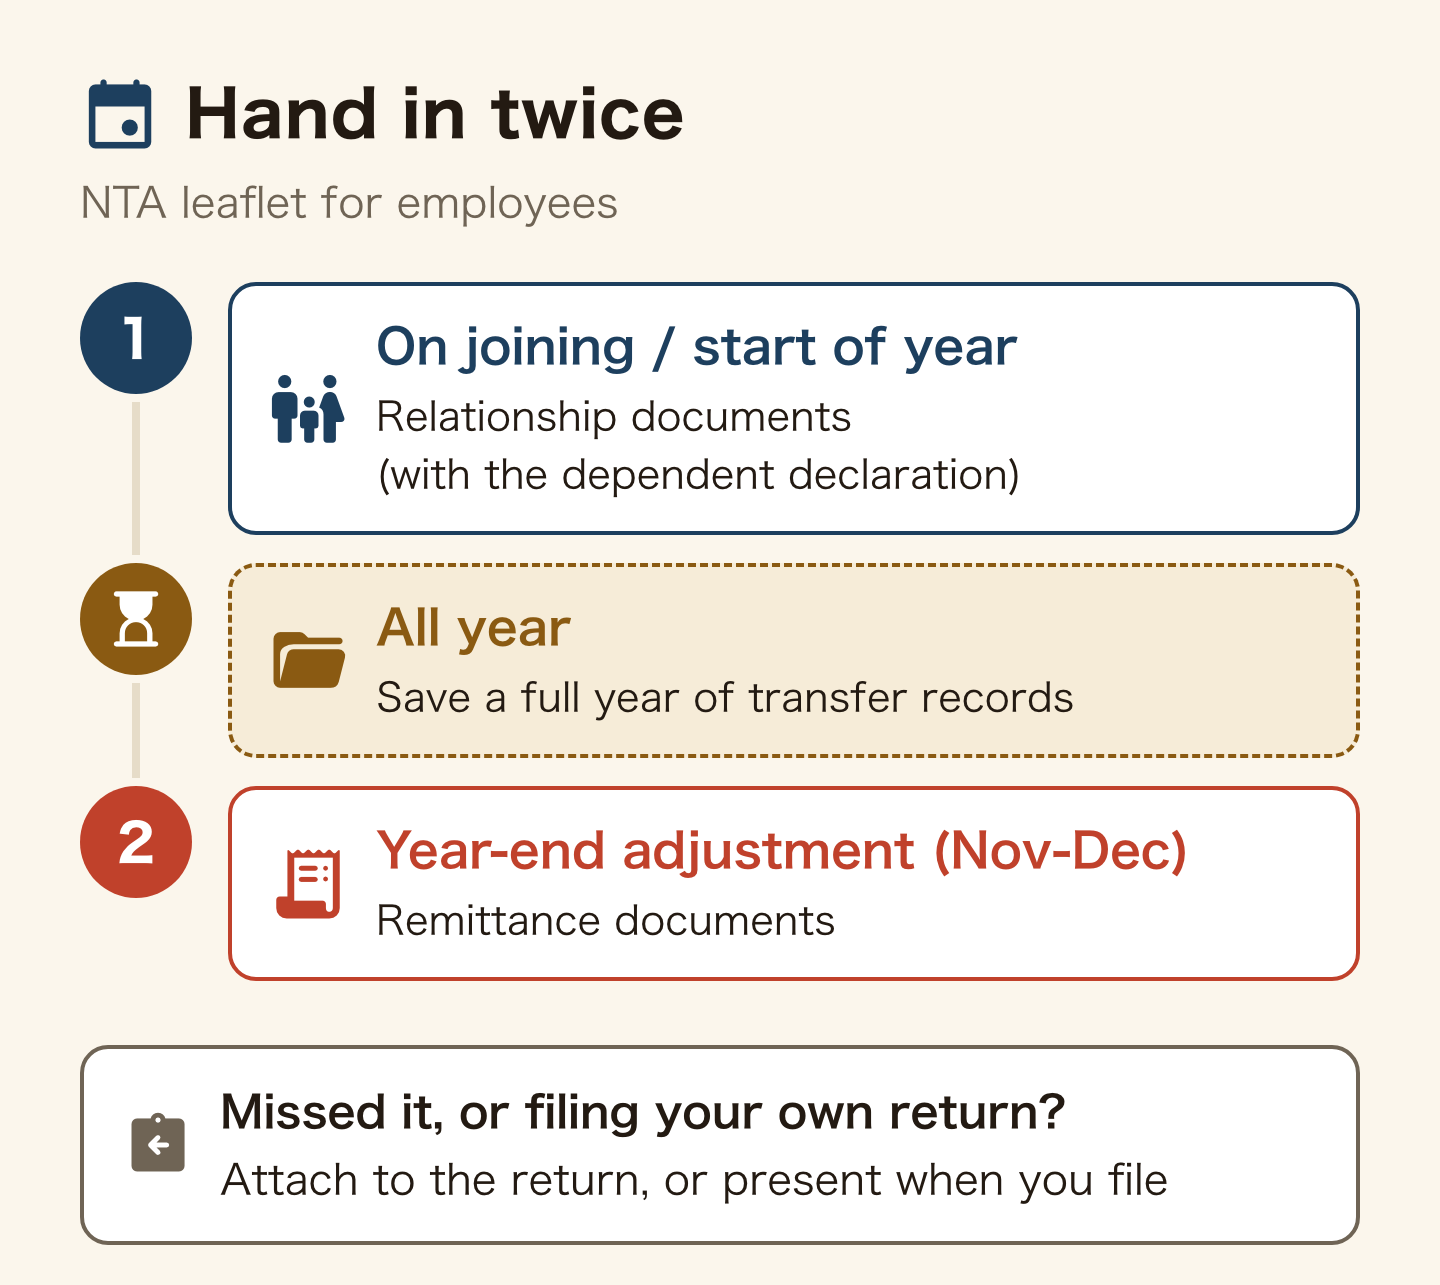
If you miss the year-end adjustment, or you file your own return, attach the documents to your tax return or present them when you file.
FAQ
Q. Is there a minimum amount I have to send?
A. Only for the “¥380,000 or more” route used for relatives aged 30 to 69. Otherwise no fixed threshold is set. But if the yearly total is very small, you will be asked what the money was for. You must genuinely be covering their living or education costs.
Q. Can I claim a child under 16?
A. Not for income tax. That is true for children living in Japan too. However, for resident tax, documents for under-16 dependents must be submitted to your city office in certain cases. Ask your municipality.
Q. What if my spouse is back home?
A. Then it is the spouse deduction, not the dependent deduction. The documents required are the same: relationship documents and remittance documents.
Q. How distant a relative can I claim?
A. Blood relatives within six degrees, your spouse, and in-laws within three degrees. Uncles, aunts, nephews and nieces are inside that range. But you must actually be supporting them.
Q. Can I claim for last year?
A. Possibly, by filing a tax return — if you met the conditions and still have the documents. You need the remittance records and relationship documents from that year. Without records it is difficult, so start by making sure this year is covered.
Q. I hand over cash when I visit. Does that count?
A. No. Only records from a financial institution, a credit card company, or an electronic payment provider are accepted. Cash handed over in person leaves no record, so no deduction.
In short
If you send money home, claim your family as dependents. ¥380,000 each, ¥630,000 for ages 19–22, ¥480,000 for 70 and over. Your resident tax falls as well, by smaller amounts (¥330,000 for a general dependent, for example).
Since January 2023, relatives aged 30 to 69 are excluded by default — but sending that person ¥380,000 or more during the year keeps them eligible.
And the costliest mistake is sending one lump sum to one person. That only counts for one. Send separately to each person you want to claim.
Two documents: proof of relationship, proof of transfer. Attach a Japanese translation if they are in another language. The transfer records are handed in at year-end, so start saving them today. January is too late.
Official sources: National Tax Agency: Taxanswer No.1180 (dependent deduction) / National Tax Agency: deductions for relatives living abroad / National Tax Agency: Q&A on relatives living abroad (PDF) / National Tax Agency: leaflet for employees (PDF) (checked 26 September 2026)
Related guides
Found this useful? Share it
Send it to a friend who lives in Japan.
To claim the deduction you need a record of the transfer. Choose a method that leaves one.
Sending Money Home from Japan →WHO WROTE THIS
mori
Japanese. I read the ministries’ own notices, orders and Q&As in the original, and I start from what my Nepalese and Sri Lankan friends in Japan actually ran into. I do not write about what I have not checked or been told.
What this site can and cannot do →Looking for something else?
You may use the figures in this article, including commercially, if you credit this site with a link. How to use our figures