Checked on 16 September 2026 against the National Tax Agency’s Tax Answers No. 2665, 2668 and 1180 and its April 2026 outline of withholding-tax changes. The figures change from the December 2026 adjustment. Your company sets its own deadline.
In short
- Nenmatsu chosei is how the income tax withheld from your pay all year gets corrected in December – usually a refund. Your employer does it. You hand in forms.
- Three forms: the dependants declaration; the basic-deduction / spouse / specified-relative / income-adjustment declaration; the insurance-premium declaration.
- The numbers change from December 2026. Basic deduction 580,000 → 1,040,000 yen (income 1.32M or less); minimum employment-income deduction 650,000 → 740,000. Salary-only earners pay no income tax up to 1.78 million yen.
- Left your job mid-year? You are usually not covered – file your own tax return. Leaving Japan is the exception: the employer adjusts when you go.
- Family back home as dependants needs two sets of documents – relationship and remittance.
In November HR hands you three forms. Japanese, dozens of small boxes, a short deadline. Hand them back blank and money that should come back to you does not. Ask a Japanese colleague and you hear “just fill it in roughly” – they have done it every year and have never needed words for what is actually happening.
- What is nenmatsu chosei? Getting overpaid income tax back in December
- Who is covered? Anyone who has filed the dependants declaration
- What changes in the December 2026 adjustment?
- What do you hand in? Three forms
- Can you claim family back home as dependants?
- What if you quit mid-year, or leave Japan?
- What if you cannot work out the forms?
- Who files, and who goes to a tax return instead
- Frequently asked questions
- Summary
What is nenmatsu chosei? Getting overpaid income tax back in December
Nenmatsu chosei (year-end adjustment) is the procedure by which your employer, in December, settles the difference between the income tax withheld from your pay each month and the tax you actually owe for the year. That is the National Tax Agency’s definition in Tax Answer No. 2665.
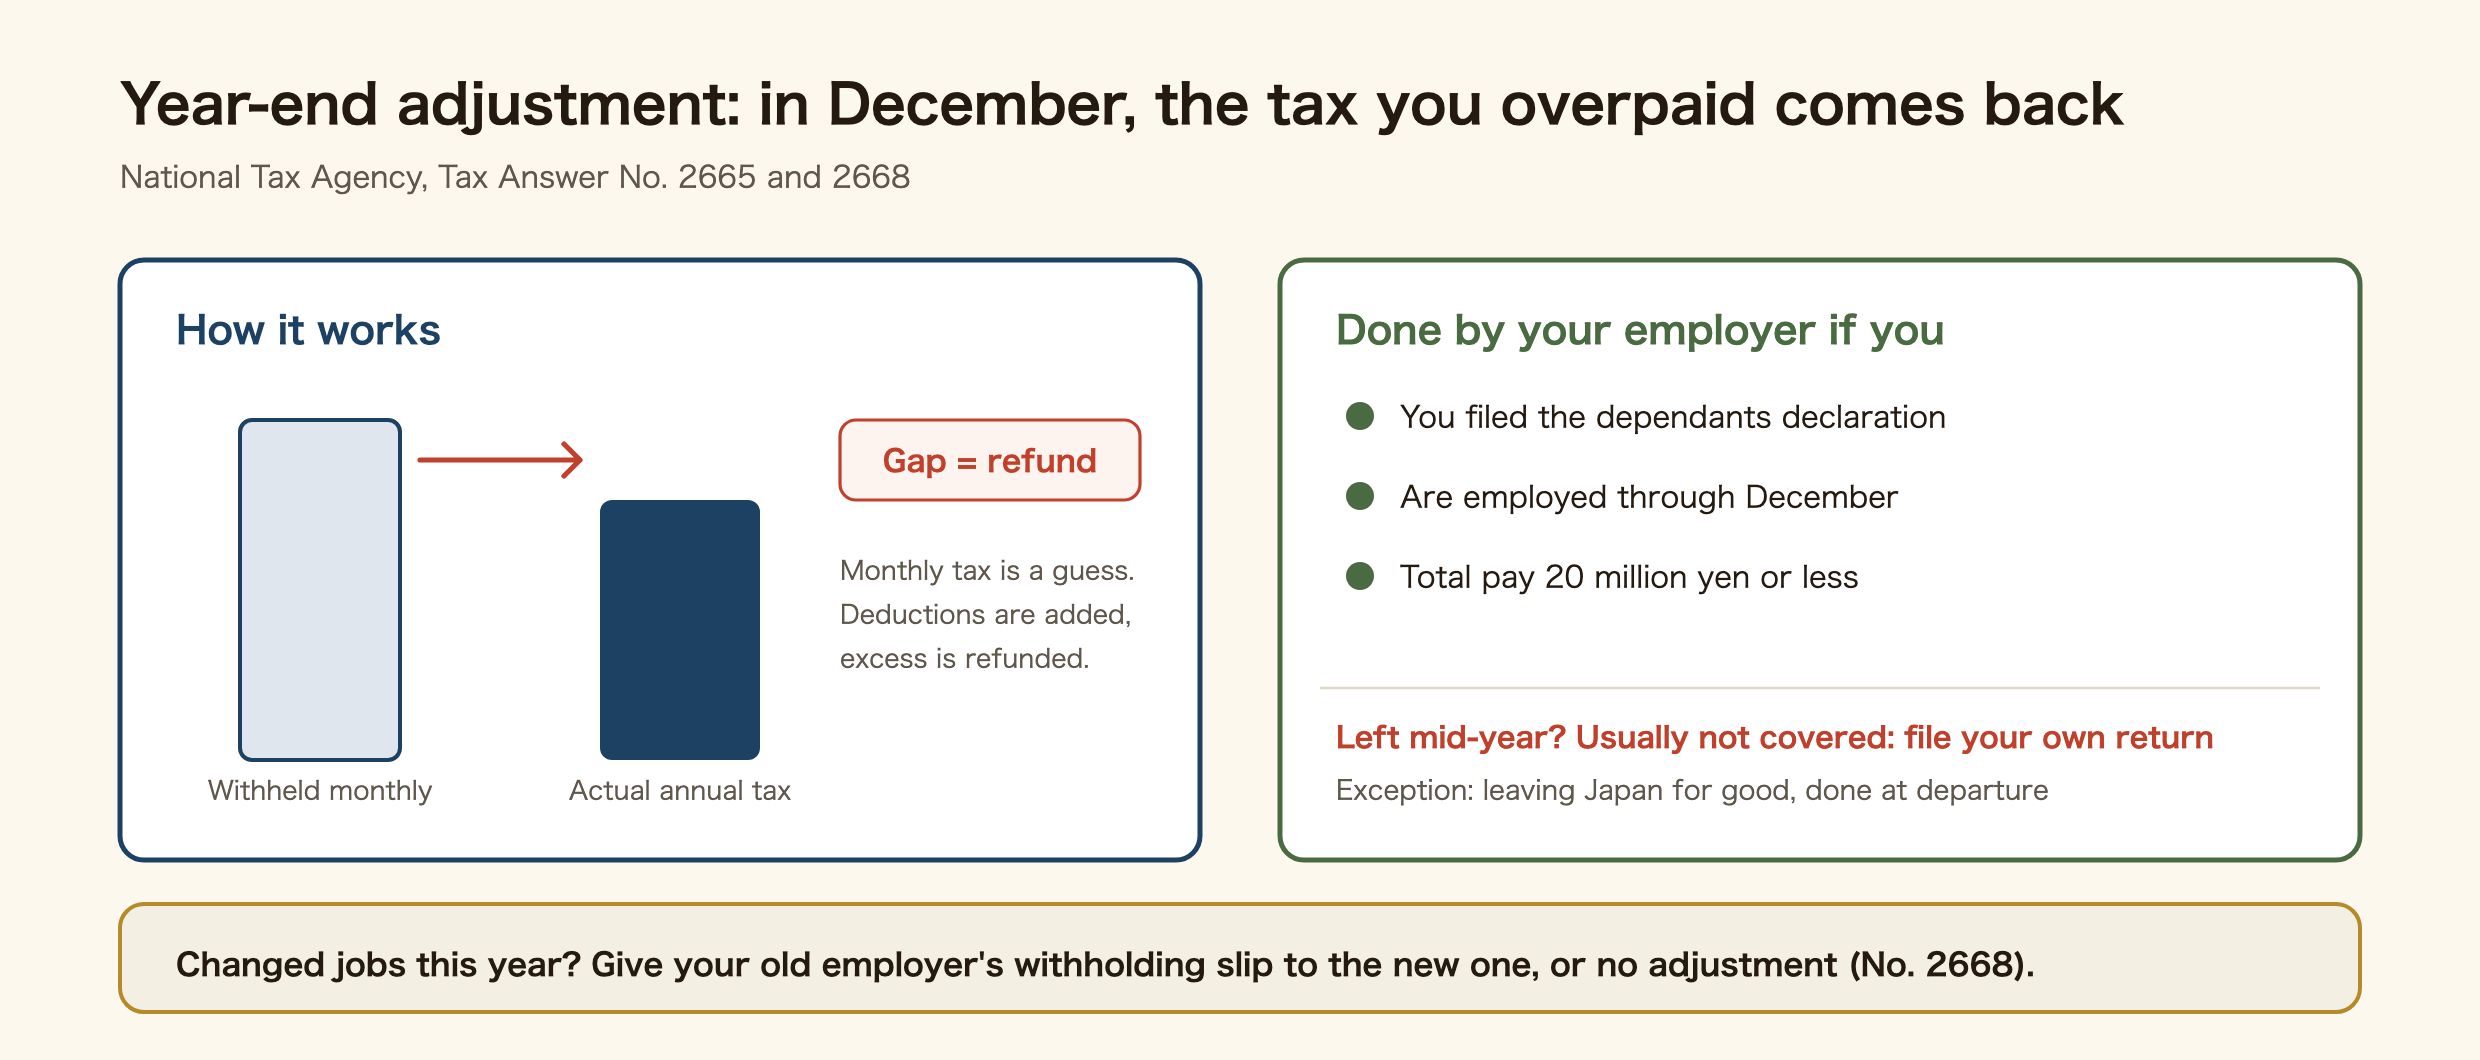
Why is there a difference? Because the tax taken from each monthly payslip is a provisional figure. It is calculated mechanically from that month’s pay and knows nothing about your dependants or insurance premiums. In December all of those deductions are applied to work out the real annual tax, and the result is usually that too much was taken. The difference comes back on top of your December or January pay.
Which is why not handing in the forms means the deductions never get applied, and the refund never arrives.
Who is covered? Anyone who has filed the dependants declaration
The December adjustment is done for (No. 2665):
- people who have filed the “dependants declaration” (fuyo kojo to shinkokusho) with the employer – the form with your family’s names that you filled in when you joined
- people employed all year, or who joined mid-year and are still employed in December
- but not people whose total pay exceeds 20 million yen (they file their own return)
If you joined mid-year, your previous employer’s pay is included. For that you must give your new employer the withholding slip (gensen choshu hyo) from the previous job. No. 2668 states plainly that without it the adjustment cannot be done. Ask the old employer for it – they must issue one.
What changes in the December 2026 adjustment?
This is the heart of this year. The 2026 tax reform takes effect on 1 December 2026 and applies to 2026 income. The agency’s outline says withholding through November is unchanged, and everything is settled in the December adjustment.
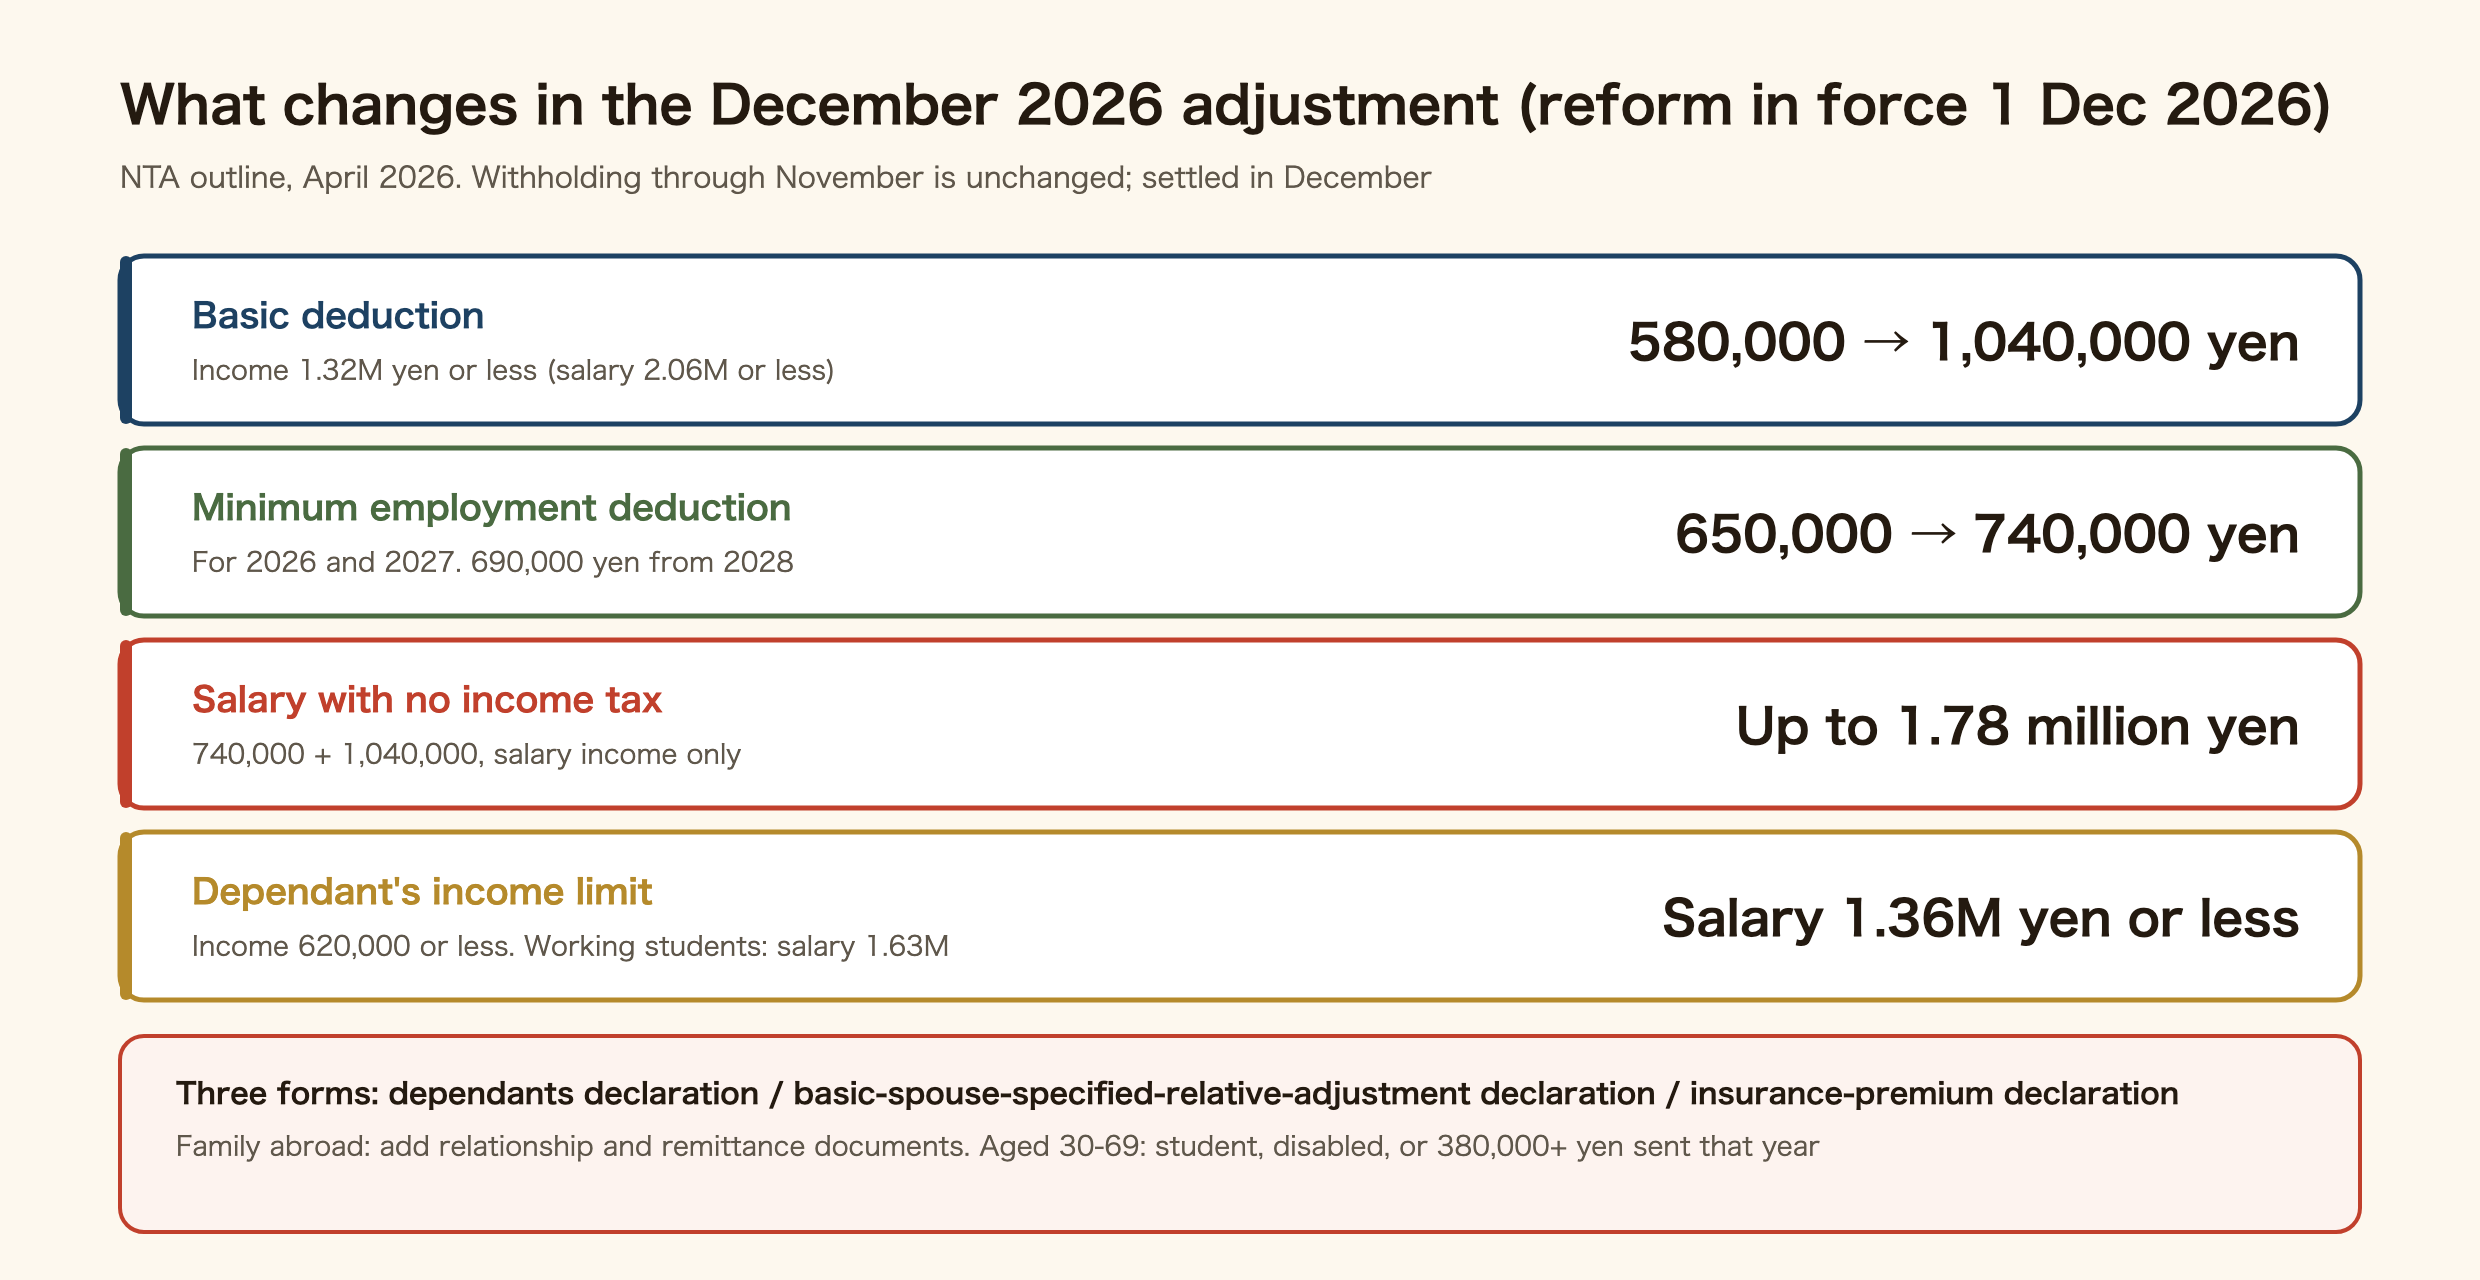
- Basic deduction: 580,000 → 1,040,000 yen for total income of 1.32 million yen or less (salary of 2.06 million or less), for 2026 and 2027. It steps down as income rises, to 620,000 yen above 6.55 million.
- Minimum employment-income deduction: 650,000 → 740,000 yen (2026 and 2027; 690,000 from 2028)
- Add the two together and a salary-only earner pays no income tax up to 1.78 million yen.
- Income limit for a dependant: 580,000 → 620,000 yen (salary 1.36 million or less). Working students: 890,000 yen (salary 1.63 million or less).
This lands directly on students with part-time jobs. The line you have heard as “1.03 million” or “1.23 million” is 1.78 million for 2026 income. Anything you can earn inside the 28-hour limit is now almost certainly income-tax-free. Residence tax and social insurance have their own thresholds – do not mix them up.
What do you hand in? Three forms
- The dependants declaration (kyuyo shotokusha no fuyo kojo to (ido) shinkokusho) – usually next year’s copy, handed in at year end. Spouse, children, parents back home go here
- The basic deduction / spouse deduction / specified-relative special deduction / income-adjustment deduction declaration – one form with a very long name. You need it to receive the basic deduction, so single people file it too
- The insurance-premium deduction declaration – for anyone paying life insurance, national pension or National Health Insurance premiums themselves. Write them here and they become deductions
The deadline is set by your company. The legal limit is the day before your last payday of the year, but employers collect earlier – often during November.
Can you claim family back home as dependants?
Yes, with two kinds of documents.
- Relationship documents – family register, birth certificate or similar showing the relationship (with Japanese translation)
- Remittance documents – records of money you sent to that person
And there is an age rule (No. 1180). Relatives aged 16-29 and 70 or over qualify with those two documents. Relatives aged 30-69 qualify only if they are studying abroad, disabled, or received 380,000 yen or more from you that year for living or education costs. Most parents back home fall in that age band, so a record of 380,000 yen or more sent in the year is the key. The document details are in the overseas-dependants article.
What if you quit mid-year, or leave Japan?
If you left a job during the year and are not employed in December, you are in principle not covered by the adjustment. Only the exceptions listed in No. 2665 are:
- people who become non-residents by leaving Japan – the employer does the adjustment at departure
- leaving through death, or through severe illness or disability
- leaving after receiving December’s pay
- part-timers whose pay for the year is 1.36 million yen or less with no further employment expected
Everyone else who left mid-year files their own tax return in February-March of the following year. Over-withheld tax comes back if you file. It does not if you do not.
If you are leaving Japan, tell your employer before you go so they can run the departure-time adjustment. It is on the leaving-Japan checklist.
What if you cannot work out the forms?
Do not hand them back blank. Fill in what you can, leave the rest, and take them to HR saying “I do not understand this part.” Completing your adjustment correctly is the employer’s legal duty too, so nobody minds being asked.
The agency publishes completed sample forms. Copying from the sample closest to your situation is the fastest route.
Who files, and who goes to a tax return instead
Everyone employed in December files. Even single with no dependants – without form 2 the basic deduction is not applied.
Two jobs? The adjustment happens at one of them only. The dependants declaration can be filed with one employer. The other job’s pay is combined in a tax return next year.
Left a job and not in a new one by December? Skip waiting for an adjustment and prepare the tax return. All you need is the withholding slip from the job you left.
Frequently asked questions
Q. What is nenmatsu chosei?
The employer’s December settlement of the difference between the income tax withheld from your pay each month and the tax you actually owe for the year. Too much is usually taken, so the difference comes back.
Q. What do I hand in?
Three forms: the dependants declaration; the basic / spouse / specified-relative / income-adjustment declaration; the insurance-premium declaration. Single people file the second one too.
Q. What changes in the 2026 adjustment?
The basic deduction rises from 580,000 to 1,040,000 yen (income 1.32M or less) and the minimum employment-income deduction from 650,000 to 740,000, so salary-only earners pay no income tax up to 1.78 million yen. In force 1 December 2026, used from the December adjustment.
Q. Can I claim my parents back home?
Yes, with relationship and remittance documents, and relatives aged 30-69 must be studying abroad, disabled, or have received 380,000 yen or more from you that year.
Q. I quit mid-year. What happens to the adjustment?
In principle you are not covered. File a tax return in February-March and the over-withheld tax comes back. If you join a new employer by December, give them your old withholding slip and they adjust there.
Q. I am leaving Japan this year.
The employer runs the adjustment when you depart. People becoming non-residents are covered by the mid-year adjustment. Tell your company before you go.
Summary
Nenmatsu chosei returns the income tax you overpaid, in December. Hand in three forms and the employer does the rest. Hand them in blank and the money stays where it is.
From December 2026: basic deduction 1,040,000, employment deduction 740,000, no income tax up to 1.78 million yen of salary. Quit mid-year: file a return. Leaving Japan: adjusted at departure. Family abroad: the remittance record is the key.
Sources (official): National Tax Agency, Tax Answer No. 2665, who is covered by the year-end adjustment / No. 2668, pay covered by the adjustment / No. 1180, dependant deduction (relatives abroad) / Outline of withholding-tax changes, April 2026 (PDF) / On the 2026 increase in the basic deduction / Forms and completed samples (all checked 16 September 2026)
Found this useful? Share it
Send it to a friend who lives in Japan.
WHO WROTE THIS

mori
Japanese. I read the ministries’ own notices, orders and Q&As in the original, and I start from what my Nepalese and Sri Lankan friends in Japan actually ran into. I do not write about what I have not checked or been told.
What this site can and cannot do →Looking for something else?