Checked on 7 October 2026. Sources: the Ministry of Health, Labour and Welfare, the Japan Health Insurance Association, the Japan Pension Service, the National Tax Agency, Japanese law on e-Gov, Tokyo’s National Health Insurance guide and the Japan Institute of Life Insurance.
The short answer
- Do you need life insurance in Japan? It mostly depends on one thing: does anyone live on your income here?
- Before buying, count three public benefits: the monthly cap on medical bills, sick pay while you cannot work, and the survivors’ pension for your family.
- Sick pay (the sickness and injury allowance) comes with employee health insurance. Most students and self-employed people are in National Health Insurance. There, the law only lets each city choose to pay it. Some cities do not.
- A survivors’ pension goes only to family who relied on your income. The basic survivors’ pension goes only to a spouse with a child, or to the child.
- Foreigners can buy private life insurance. But some insurers require the beneficiary to live in Japan too. Want family back home to get the money? Check that first.
With this, you can choose a policy based on your own family, not a sales pitch. You will not pay for cover you already have. And you will not miss the gap you really have.
You have just handed in your paperwork at a new job. A colleague asks, “You haven’t got life insurance yet?” A Japanese friend says it is safer to have some. The brochure is full of words you do not know. But your friend already knows what Japan’s health insurance and pension pay. They buy insurance only for what is left over. Use the same order, and the answer becomes clear.
- Do foreigners in Japan need life insurance?
- How much does a hospital stay cost? The monthly cap
- Who pays you if you are too sick to work?
- What does your family get if you die? The survivors’ pension
- Can foreigners get life insurance in Japan?
- If you buy, what kind — and how much does life insurance cost in Japan?
- Already insured, or leaving Japan?
- Which one are you?
- Frequently asked questions
- Summary
- Related reading
Do foreigners in Japan need life insurance?
In your country, buying life insurance as soon as you start work may be normal. In Japan, employees already have health insurance and employees’ pension. These cover part of illness, time off work and death. You pay for them from every pay slip. Students and the self-employed are on National Health Insurance and the National Pension. They also have some cover.
So split the risk into three, and count what the public system pays for each.
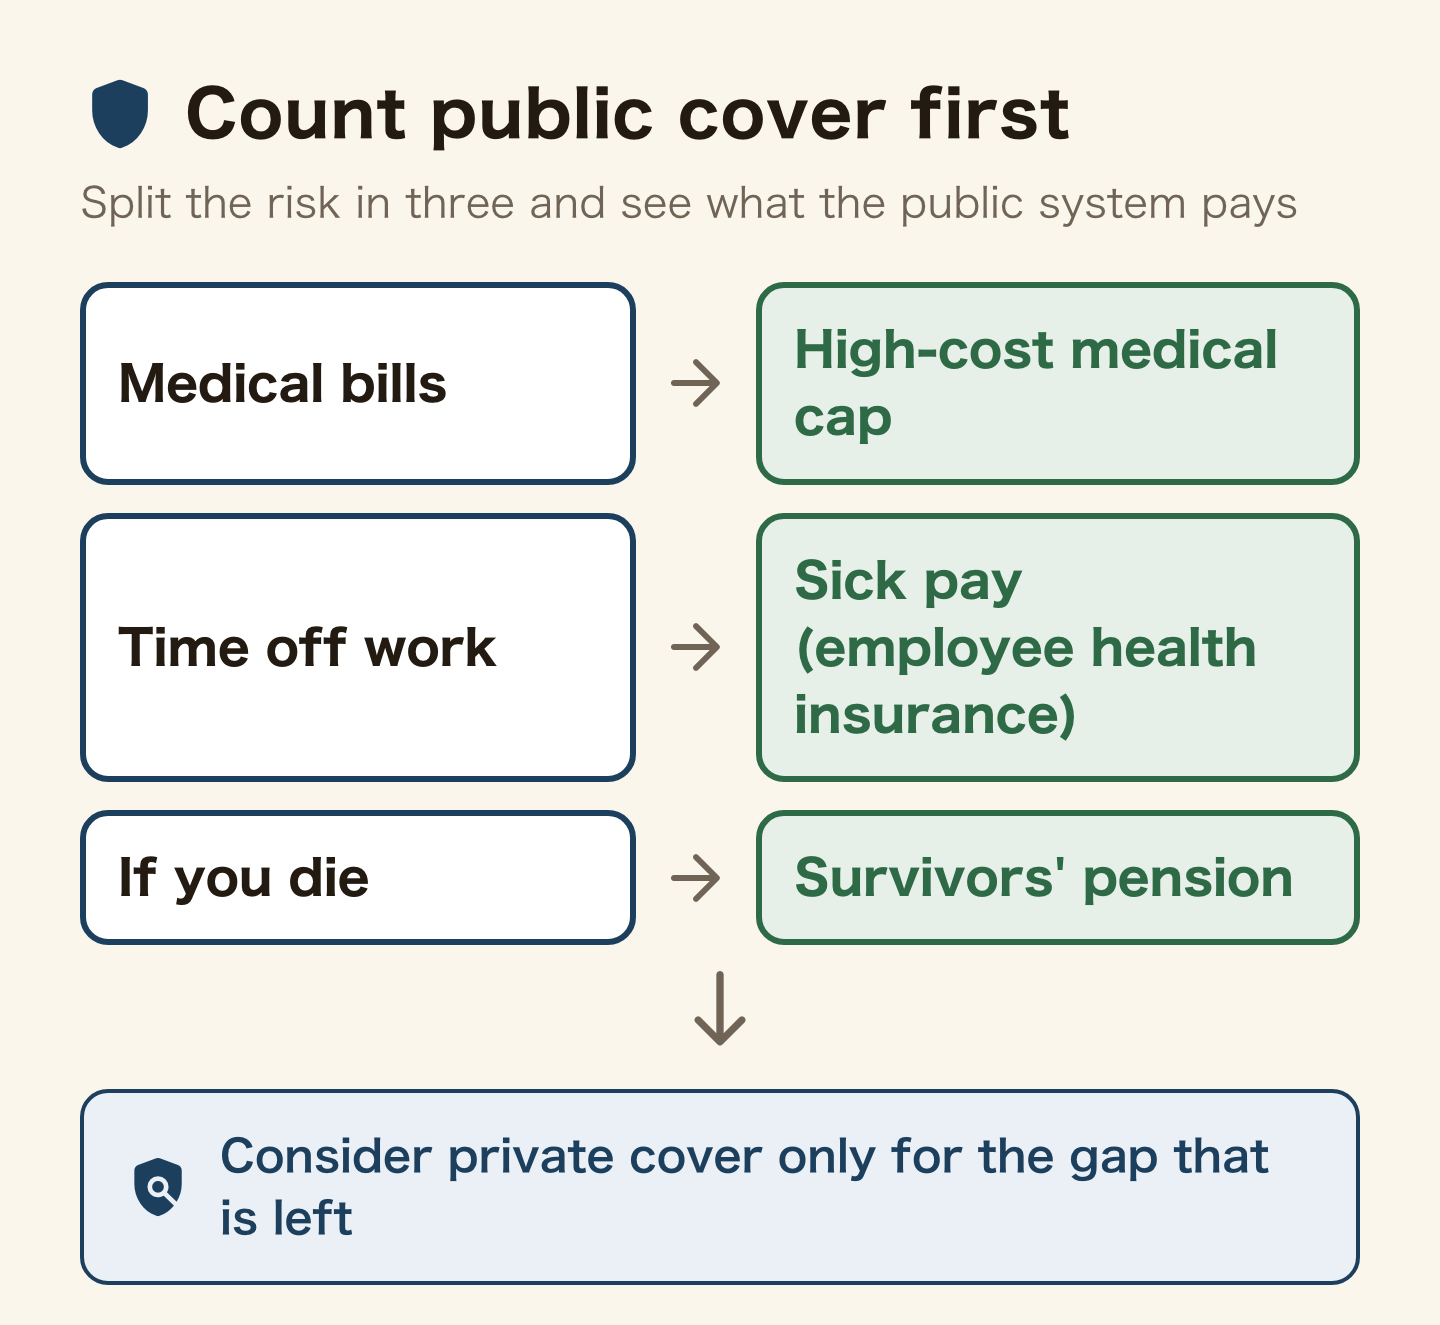
Life insurance is mainly about leaving money to your family if you die. If nobody in Japan lives on your income, fewer people would be in trouble if you died. If someone does, first count what the survivors’ pension pays. Then think about what is missing. Does your family live in your home country? Then both the public pension and private insurance add extra conditions for them to receive money.
Across Japan, 80.0% of people have life insurance. The average annual premium is 171,000 yen (Japan Institute of Life Insurance, 2025 survey, in Japanese). That figure includes cooperative cover from the post office, JA and prefectural mutual aid schemes. Many people around you may have it. That does not mean you need it.
How much does a hospital stay cost? The monthly cap
If you are in Japanese health insurance and under 70, you pay 30% of the medical bill at the counter. On top of that, there is a limit on what you pay in one month. This is the high-cost medical expense benefit. Both employee health insurance and National Health Insurance have it.
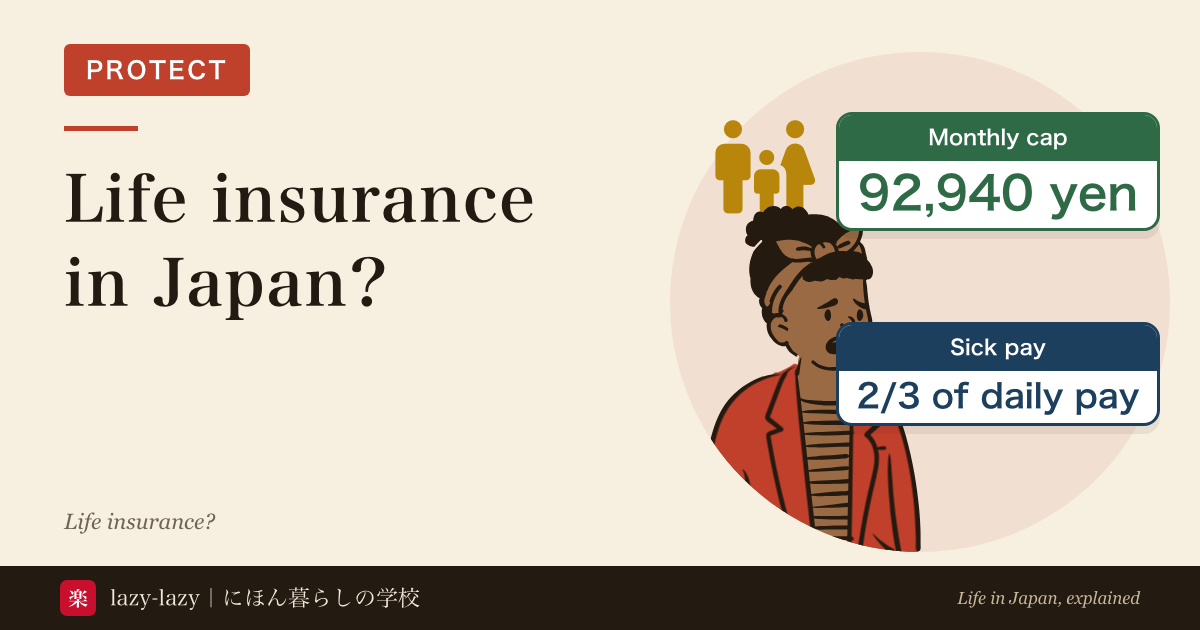
Take the rules from August 2026 to July 2027. Say you are under 70, with an annual income of about 3.7 to 7.7 million yen. Your cap is 85,800 yen + (medical bill − 286,000 yen) × 1%. Say the bill is 1,000,000 yen in one month. Your 30% share would be 300,000 yen, but the cap is 92,940 yen (Ministry of Health, Labour and Welfare reference document, in Japanese). With income up to about 3.7 million yen, the cap is 61,500 yen. If you are exempt from resident tax, it is 36,900 yen. From August 2027, the income bands become narrower.
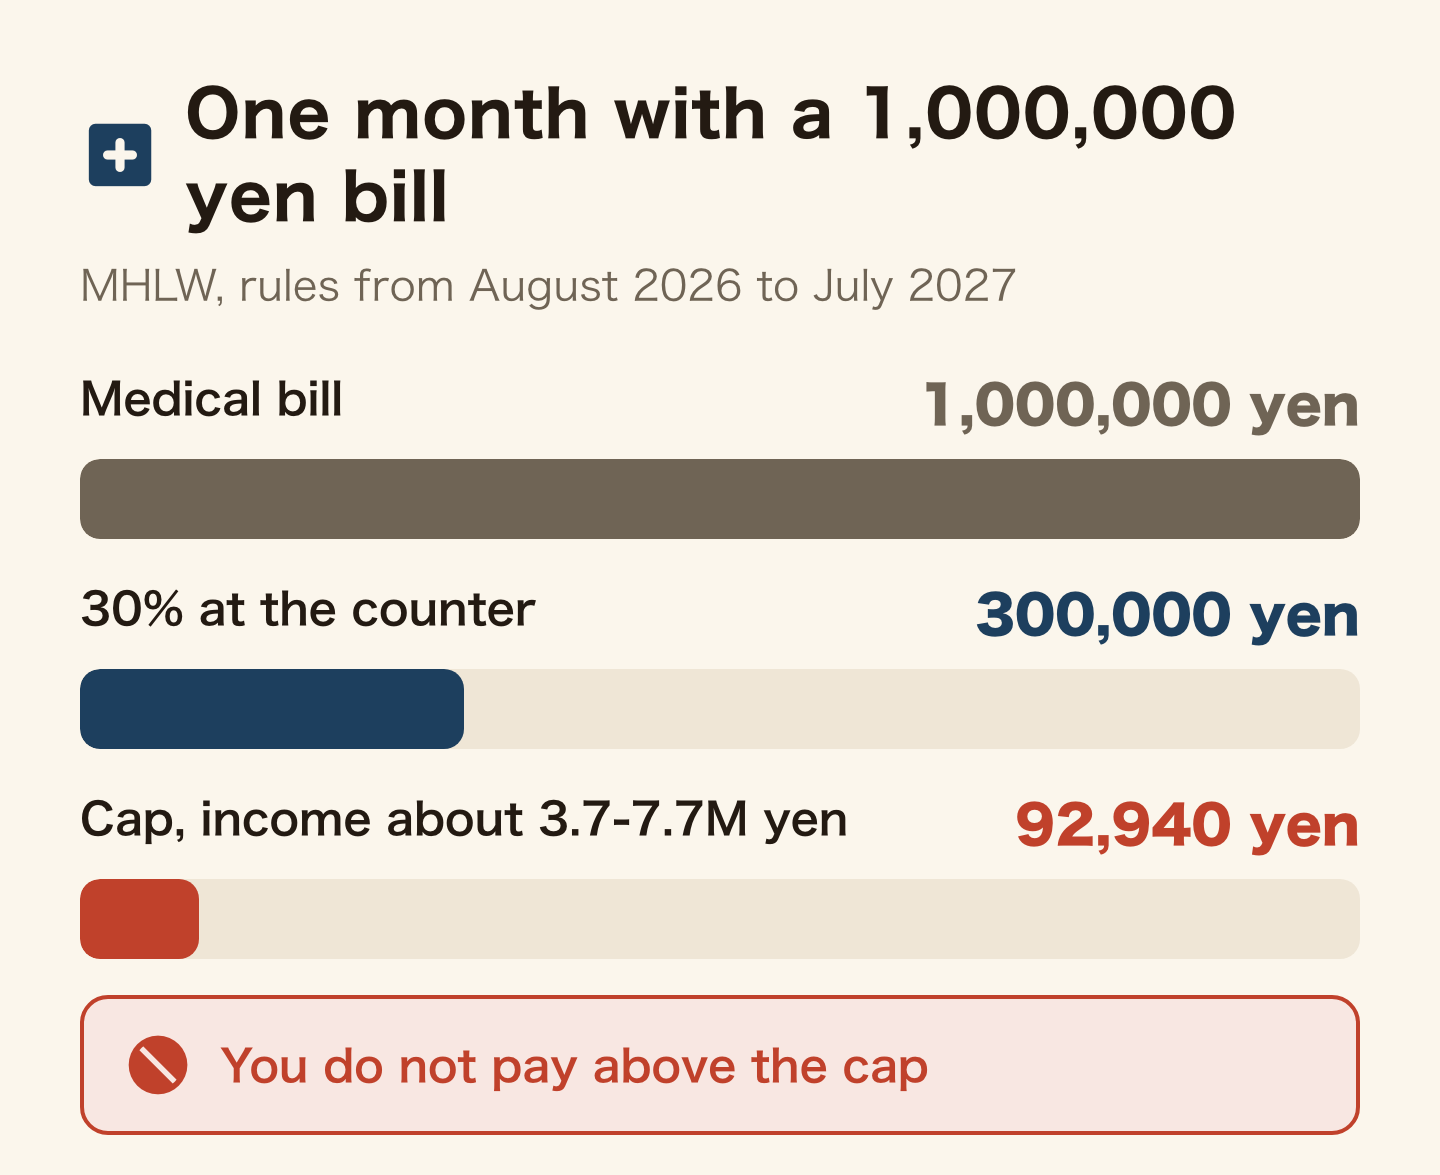
Did you hit the cap in three or more of the last 12 months? Then the cap drops further from the fourth month. From August 2026, there is also a yearly cap (MHLW, in Japanese). For the full table and how to claim, see our guide to the high-cost medical expense benefit.
The cap does not include hospital meals, or private-room charges that insurance does not cover (Tokyo Metropolitan Government, in Japanese). Thinking of private medical cover? First ask yourself: could your savings pay up to the cap, plus those extras?
Who pays you if you are too sick to work?
The bigger risk is usually not the bill. It is losing your pay. If you are in employee health insurance, you have the sickness and injury allowance.
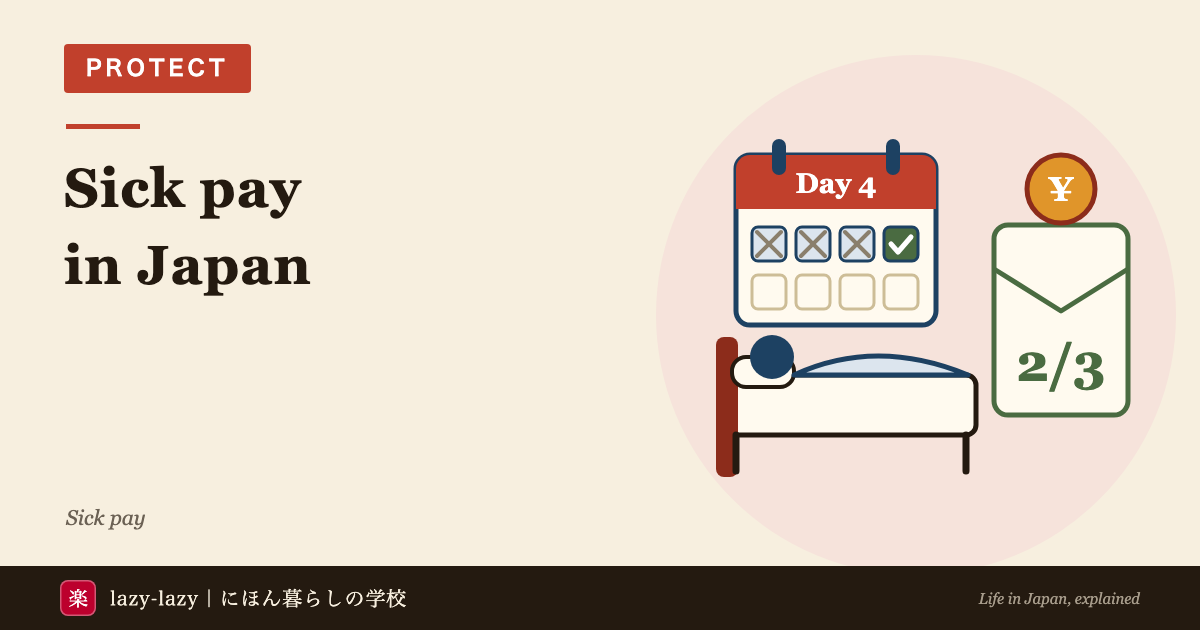
It pays when an illness or injury outside work stops you working. Your employer must also not be paying you. After three days off in a row (the waiting period), it starts on day 4. Take your average standard monthly remuneration over the previous 12 months. Divide it by 30. The daily amount is two-thirds of that. With an average of 170,000 yen, that is 5,670 × 2/3 = 3,780 yen a day. It is paid for up to 1 year and 6 months in total, from the first day paid (Japan Health Insurance Association, in Japanese).
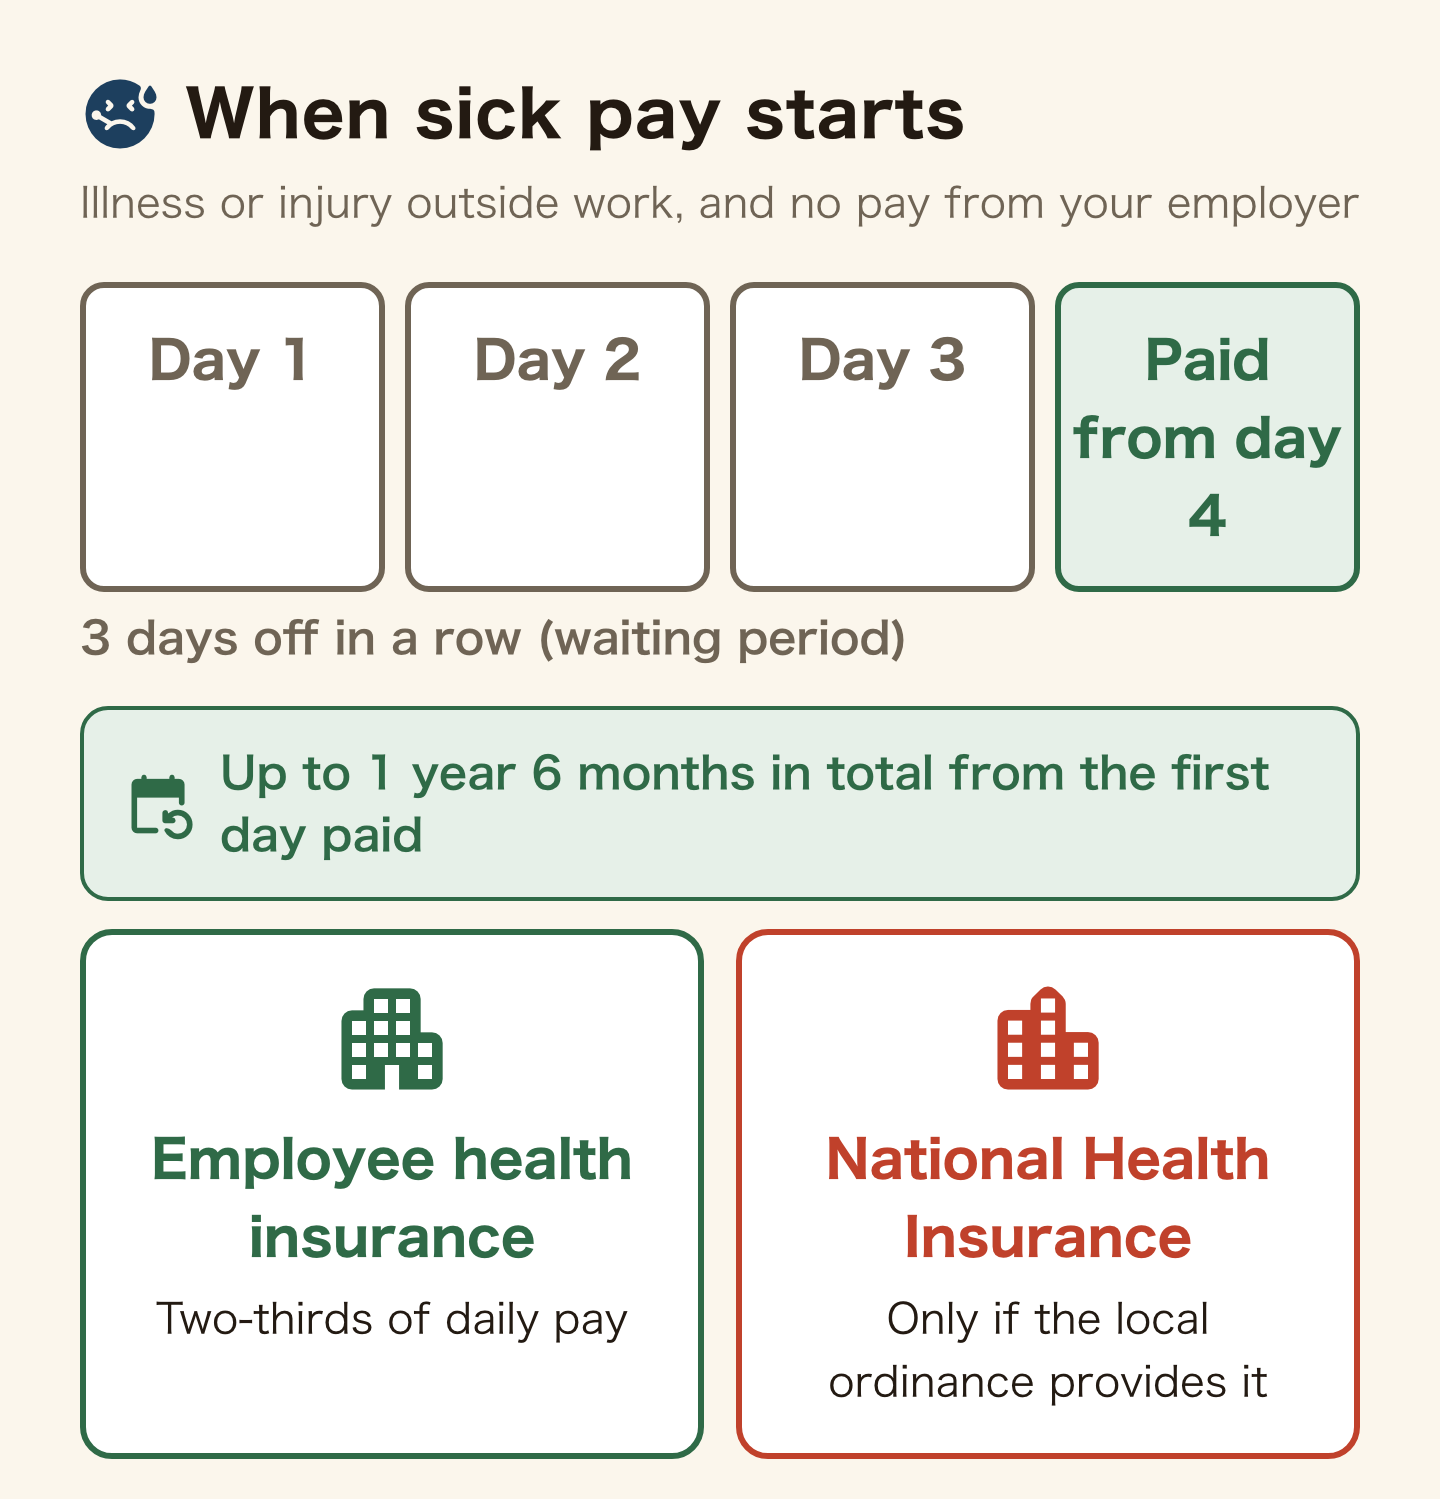
There are exceptions. Days when you get paid are not covered. (If your pay is lower than the allowance, you get the difference.) Injuries at work or on the way to work are covered by workers’ accident insurance instead. Some people stay on voluntary continued coverage after leaving a job. An illness that starts during that time is not covered. What if you leave a job while ill? Or you have been insured for under a year? See our full guide to the sickness allowance, including how working your last day stops it.
National Health Insurance may not have this benefit at all. The law says a municipality “may” pay a sickness allowance “as provided by ordinance or bylaws” (National Health Insurance Act, art. 58(2), in Japanese). So each city decides. For example, Tokyo’s list of National Health Insurance benefits does not include it (Tokyo Metropolitan Government, in Japanese).
For students and the self-employed, lost income while sick is the biggest hole in public cover. Students who work short part-time hours are not in employee social insurance (why social insurance does not apply to student part-time work). Does your own National Health Insurance pay it? Ask your city office. Our health insurance guide explains which scheme you are in.
What does your family get if you die? The survivors’ pension
A pension is not only for old age. If a member dies, the family may receive a survivors’ pension. Only family members whose livelihood the person maintained can receive it.
“Livelihood maintained” has two parts. You shared a livelihood with them. And their income in the previous year was under 8.5 million yen (or income after deductions under 6.555 million yen). Living apart can still count. For example, you sent them money, or they were your health insurance dependant (Japan Pension Service glossary, in Japanese). Want to add family in Japan to your employee health insurance? See our guide to dependent health insurance.
Survivors’ basic pension: a spouse with a child, or the child
The survivors’ basic pension comes from the National Pension. It goes only to a spouse with a child, or to the child. A “child” means someone up to 31 March after turning 18. It also means someone under 20 with a grade 1 or 2 disability. From April 2026, a spouse with a child gets 847,300 yen a year, plus a child addition. (This is for people born on or after 2 April 1956.) The addition is 243,800 yen each for the first and second child. So with one child, it is 847,300 + 243,800 = 1,091,100 yen (Japan Pension Service, in Japanese). A spouse without children, or parents back home, cannot receive it.
Payment history matters too. Say the member dies while insured. Then paid periods (including exempted ones) must cover at least two-thirds of the membership period. This is counted up to the day before death. There is an easier rule for deaths by the end of March 2036, if the person was under 65. Then it is enough to have no unpaid months in the last year. For this test, a student’s months under the student deferral count like paid months (Japan Pension Service, in Japanese). If you cannot pay, applying for the student deferral also protects your family.
Survivors’ employees’ pension: extra for employees’ families
Was the person in the employees’ pension? Then a survivors’ employees’ pension is also paid. It is three-quarters of the earnings-related part of their old-age employees’ pension. If they died while insured, fewer than 300 months (25 years) of membership is counted as 300 months (Japan Pension Service, in Japanese). Even a short time working in Japan counts as 25 years while you are a member.
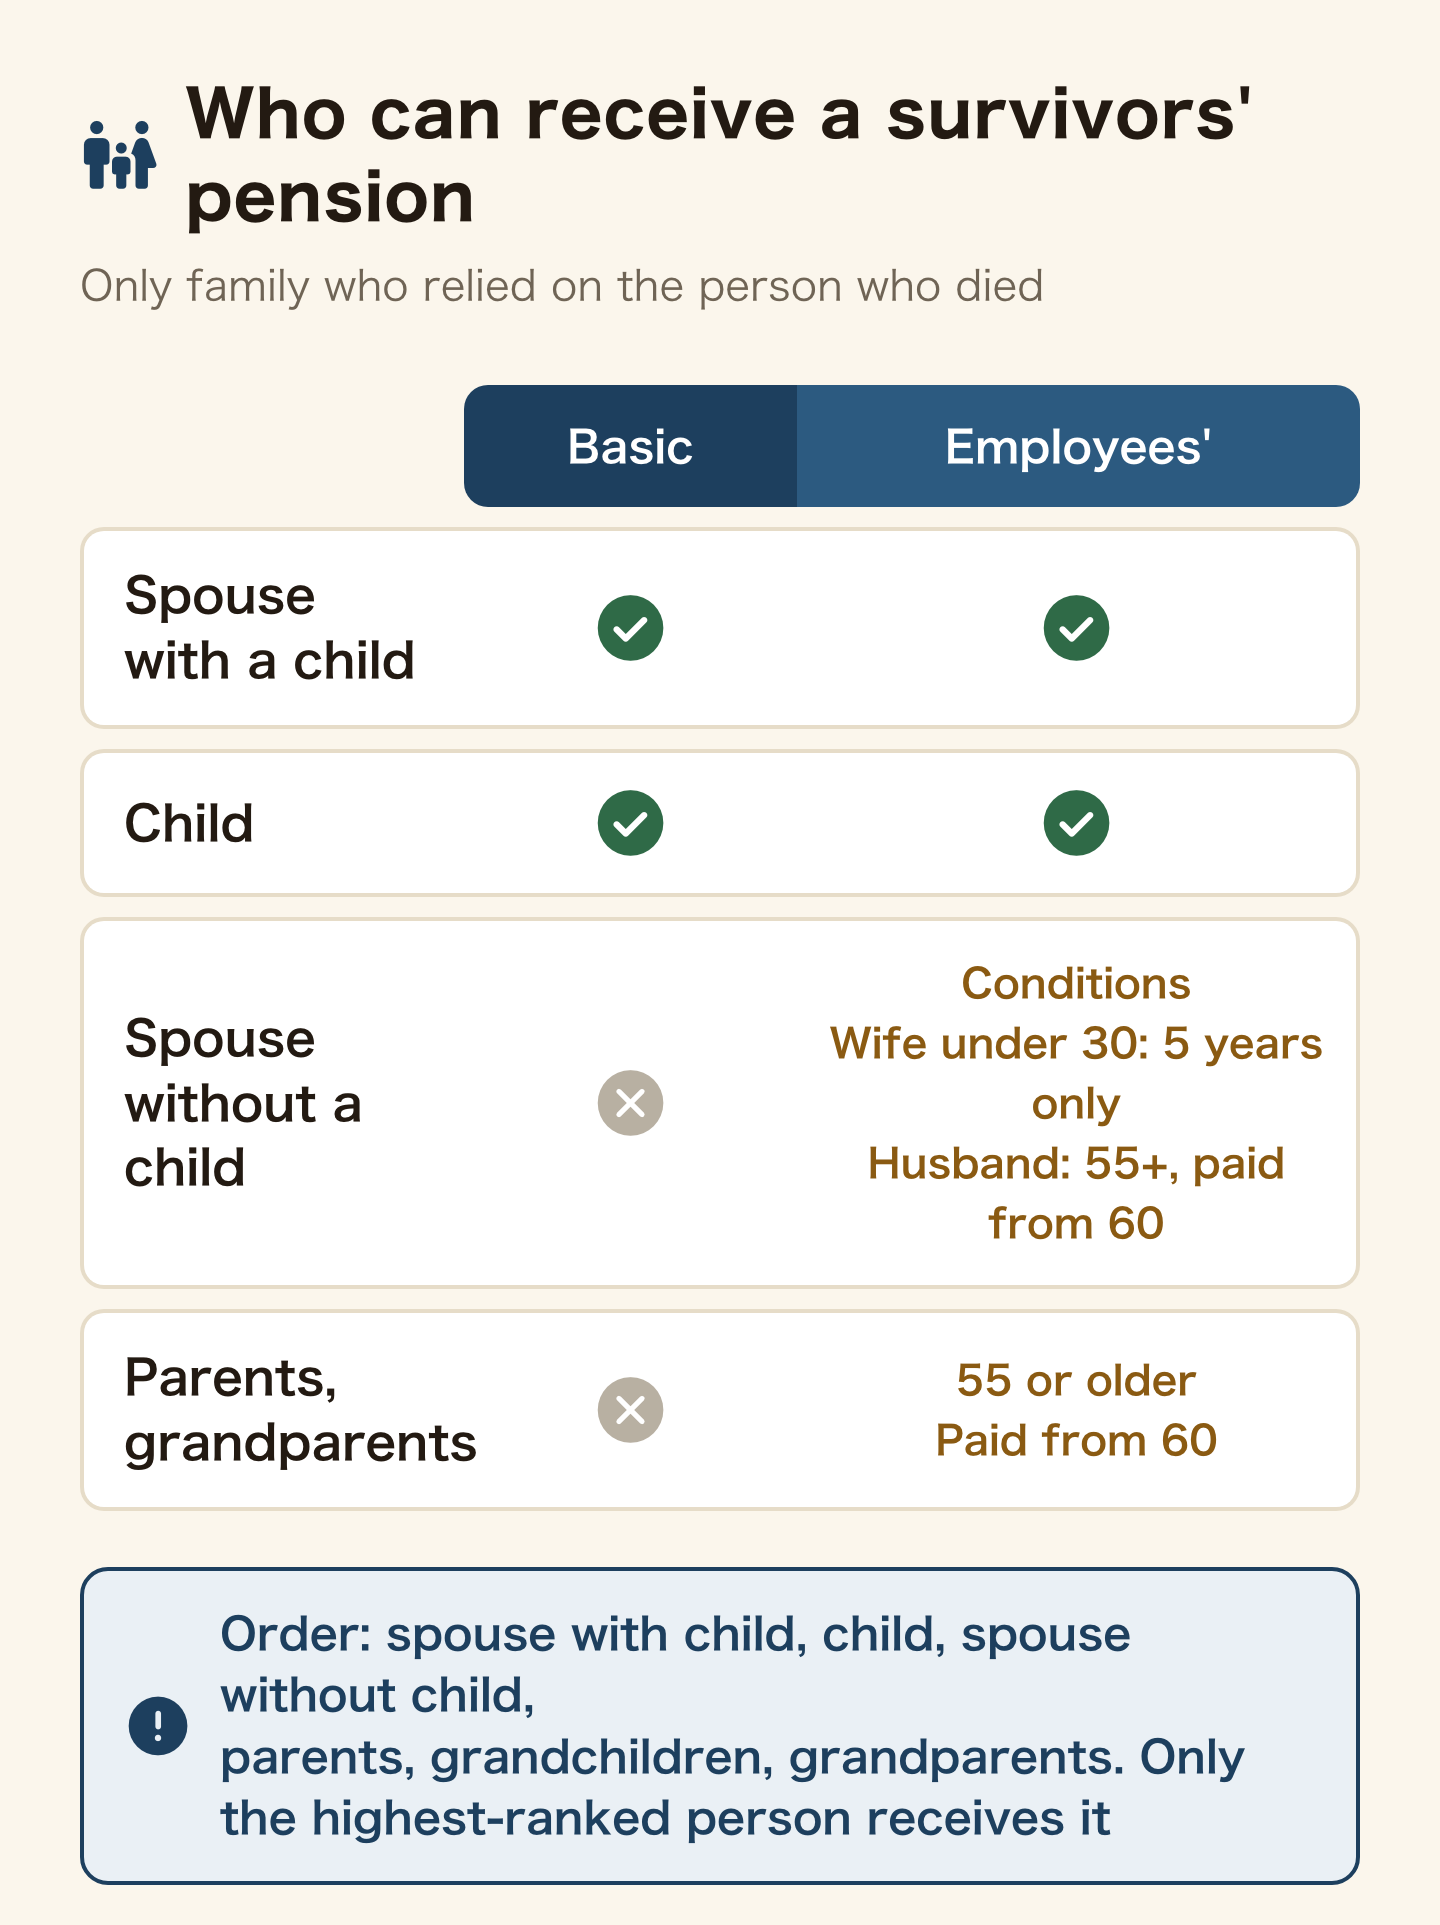
The order is: spouse with a child, child, spouse without a child, parents, grandchildren, grandparents. Only the person highest in this order receives it. The exceptions:
- A wife under 30 with no child receives it for five years only.
- A husband with no child must be 55 or older, and payment starts at 60.
- Parents and grandparents must also be 55 or older, with payment from 60.
The rules for spouses without children are due to change. A reform is set to start in April 2028. In principle, they will move to a fixed five-year benefit (MHLW, in Japanese).
Family in your home country, and the lump-sum withdrawal
People living overseas can claim some benefits. The Japan Pension Service lists the survivors’ basic and employees’ pensions among them (Japan Pension Service, in Japanese). Payments can go to an overseas bank account. But the currency is fixed for each country, and you cannot choose it (Japan Pension Service, in Japanese).
Can family back home receive it? That depends on whether you maintained their livelihood. Officially, living apart can still count if you send money. We could not find an official list of the proof used for family abroad. So keep records of the money you send, and ask a pension office. Parents back home cannot get the basic survivors’ pension. For the employees’ one, they come after any spouse or child. They must also be 55 or older.
One more point: if you take the lump-sum withdrawal payment, all your earlier membership periods stop counting (Japan Pension Service FAQ, in Japanese). Survivors’ pensions mostly depend on dying while insured. So once you have left Japan and taken the refund, do not count on a survivors’ pension from those years. For deadlines and steps, see our lump-sum withdrawal guide. For how the employees’ pension works, see Japan pension for foreigners.
The public cover to count before life insurance, at a glance
| Item | Details |
|---|---|
| Medical cost cap (kogaku ryoyohi) | For someone under 70 with income of about 3.7 to 7.7 million yen, the monthly cap is 85,800 yen + (medical bill – 286,000 yen) x 1% (August 2026 to July 2027). On a 1,000,000 yen bill, that is 92,940 yen. Up to about 3.7 million yen: 61,500 yen; residence-tax-exempt: 36,900 yen |
| Outside the cap | Hospital meals and uninsured private-room charges are not covered by the cap |
| Cap falls further | After three or more months at the cap in the past 12, the cap drops further from the fourth month. A yearly cap also exists from August 2026 |
| Income while sick | Sickness allowance (shobyo teate-kin) from an employer’s health insurance. Paid from day 4 after 3 consecutive days off: one day = the average standard monthly pay over the past 12 months / 30 x 2/3. For up to 1 year 6 months in total. Not paid for days you get a salary (the difference is paid if the salary is lower) |
| National Health Insurance | Tokyo’s list of benefits does not include the sickness allowance. Each municipality decides, so ask at its counter |
| Survivors’ basic pension | Goes only to a spouse with a child, or the child, who was supported by the person who died. From April 2026: 847,300 yen a year for a spouse with a child, plus a child addition (243,800 yen each for the first two children) |
| Payment condition | Contributions paid (exemptions included) must cover at least two-thirds of the enrolment period. For deaths up to the end of March 2036, no unpaid months in the last year is enough. Student special payment periods count as paid |
| Survivors’ employees’ pension | Three-quarters of the dead person’s old-age employees’ pension (earnings-related part). Counted as 300 months even if the record is shorter. Order: spouse with child, child, spouse without child, parents, grandchildren, grandparents. A wife under 30 with no child: 5 years. Husband, parents, grandparents: age 55 or over, payment from 60 |
| Japan-wide benchmark | 80.0% hold life insurance; the average premium is 171,000 yen a year (Japan Institute of Life Insurance, FY2025, ages 18 to 79 in Japan) |
Can foreigners get life insurance in Japan?
Some insurers accept foreign nationals who meet their conditions. Each company sets its own conditions. We checked three insurers that publish their conditions for foreign applicants in their FAQs.
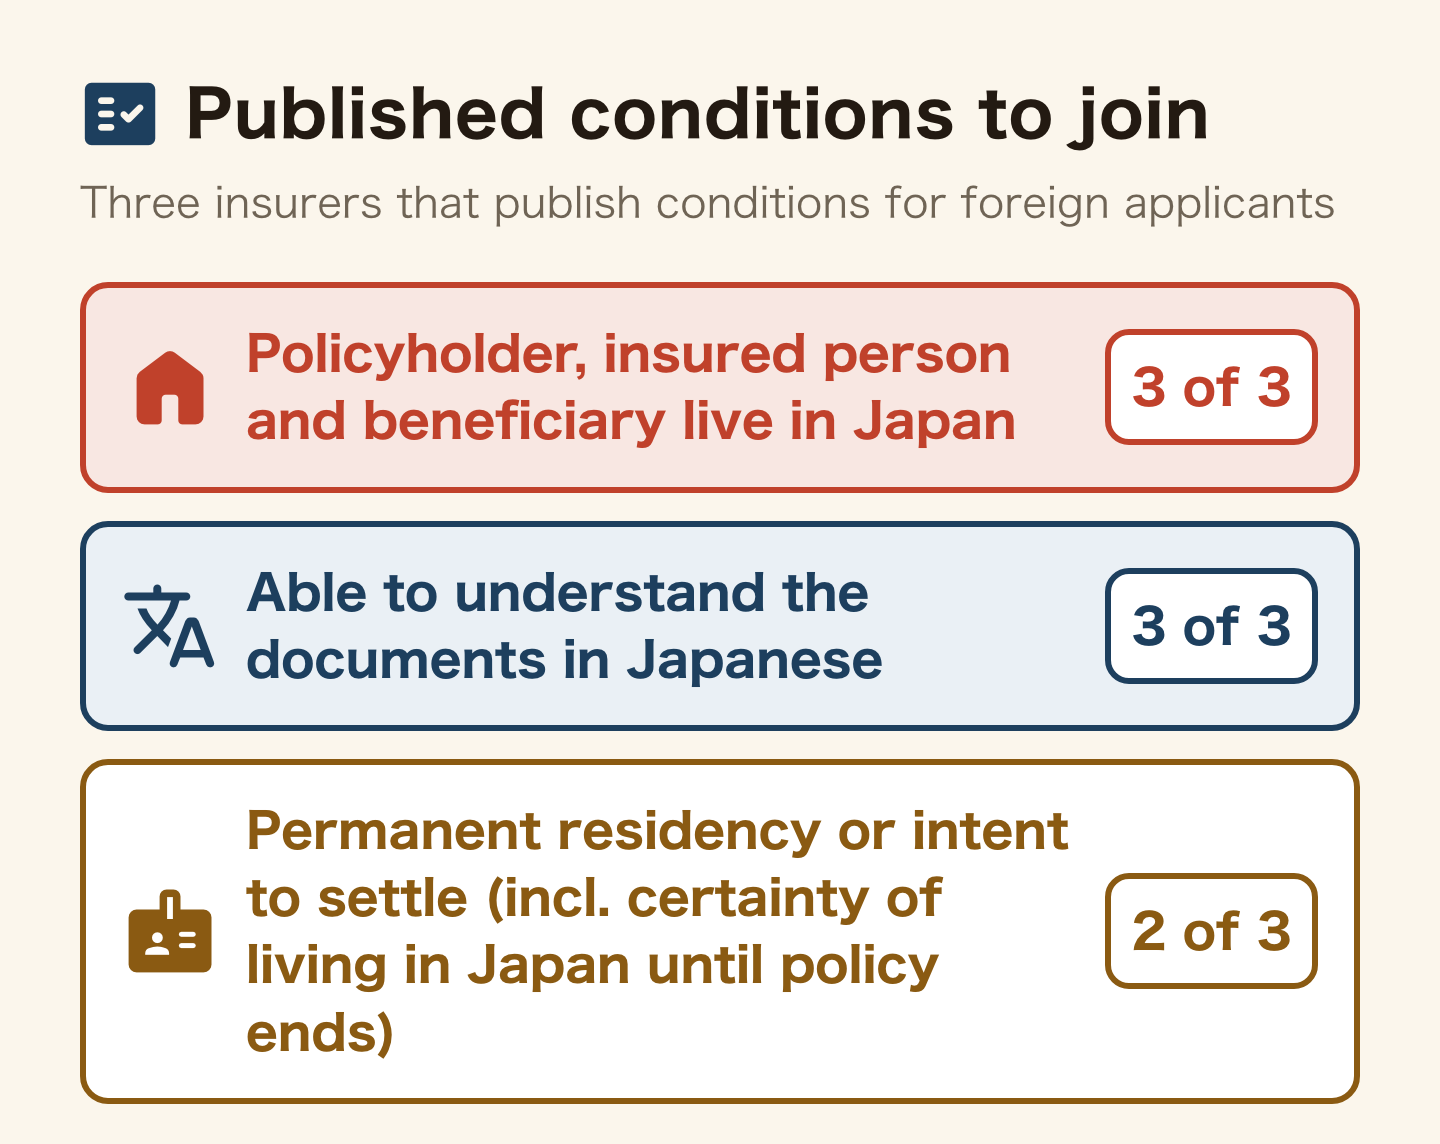
- The policyholder, the insured person and the beneficiary all live in Japan (all three).
- Enough Japanese to understand the application, the policy terms and other documents (all three).
- Permanent residency (one also requires two or more years living in Japan), or an intention to settle, or certainty of living in Japan until the policy ends (two of the three).
Three companies are not the whole market. Still, all three required two things. The beneficiary must live in Japan, and the applicant must read Japanese. Does your family live abroad, and do you want them as beneficiaries? Ask the insurer if a beneficiary overseas is allowed before you apply. And do not sign a contract you cannot read.
If you buy, what kind — and how much does life insurance cost in Japan?
Death cover comes in two main types. Term insurance covers a fixed period. Savings-type policies (whole life and endowment) pay something back at maturity or when you cancel.
Term insurance gives a large payout for a small premium. But nothing is left when the term ends. Whole life pays a surrender value if you cancel. Endowment pays the same amount as the death benefit at maturity. Neither is sure to give back more than you put in (Japan Institute of Life Insurance, in Japanese).
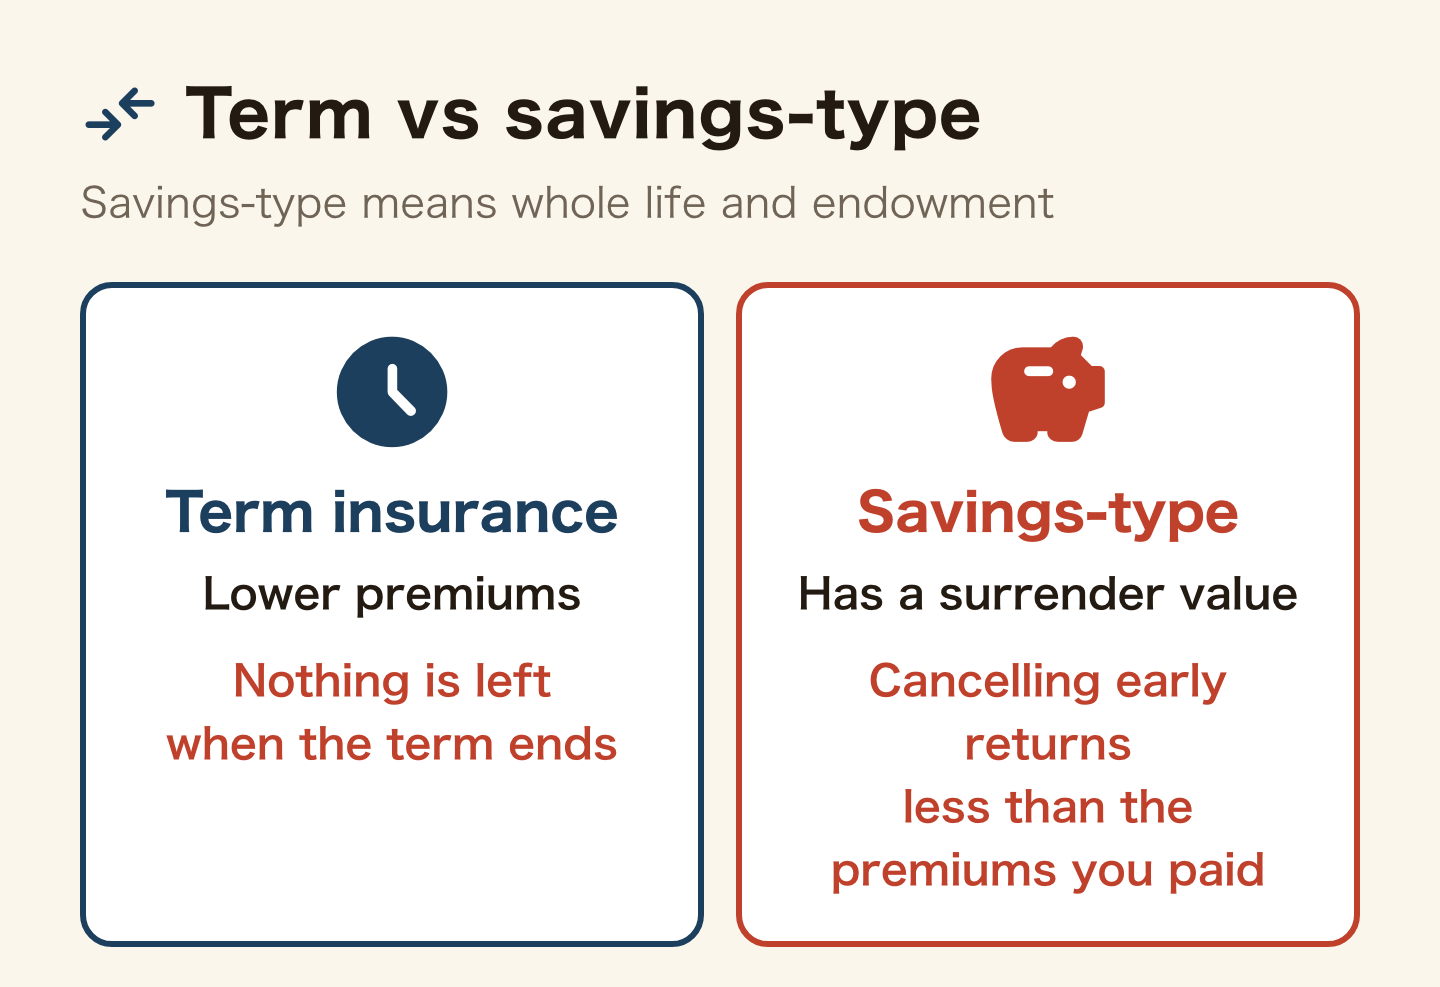
For foreigners, the key point is cancelling early. The surrender value is normally less than the total premiums you paid. If you cancel soon after starting, there may be very little, or none at all (Japan Institute of Life Insurance, in Japanese). Not sure when you will leave Japan? A contract that assumes decades of payments can lose you money if you cancel when you leave. Does a bank counter offer you a foreign-currency savings policy? Before you sign, check the exchange-rate costs and how cooling-off works. If your goal is to grow money, compare it with NISA and investing, including what happens when you leave.
How much do people pay? In the national survey, the average annual premium is 171,000 yen (including individual annuity insurance). For both men and women, the most common band is under 120,000 yen a year (Japan Institute of Life Insurance, 2025 survey, in Japanese). The survey covers people aged 18 to 79 in Japan (survey release, in Japanese). It is not a guide for a foreign household. To set an amount, first count what the survivors’ pension and your savings cover. Then insure only the gap.
Already insured, or leaving Japan?
Premiums lower your tax
Life insurance premiums paid in Japan qualify for the life insurance premium deduction. For contracts from January 2012, paying more than 80,000 yen a year gives a flat 40,000 yen deduction. With medical-care and annuity insurance added, the total limit is 120,000 yen. From the 2026 tax year, if you have a dependant under 23, the life insurance part goes up to 60,000 yen (National Tax Agency No.1140, in Japanese). Employees claim it in the year-end tax adjustment. Others claim it in a tax return.
Some people keep paying a policy bought in their home country. A contract signed abroad with a foreign insurer does not qualify. Also, all beneficiaries must be you, your spouse or other relatives (National Tax Agency No.1141, in Japanese).
When you leave: keep it or cancel it
Moving abroad does not always end a policy. You may be able to keep it by paying the premiums. Tell the insurer you are moving. Then arrange payment through a proxy in Japan or a Japanese account. But life insurers generally do not send payouts abroad (Japan Institute of Life Insurance, in Japanese). That guidance is for people whose employer sends them overseas. If you are leaving Japan for good, ask your insurer directly.
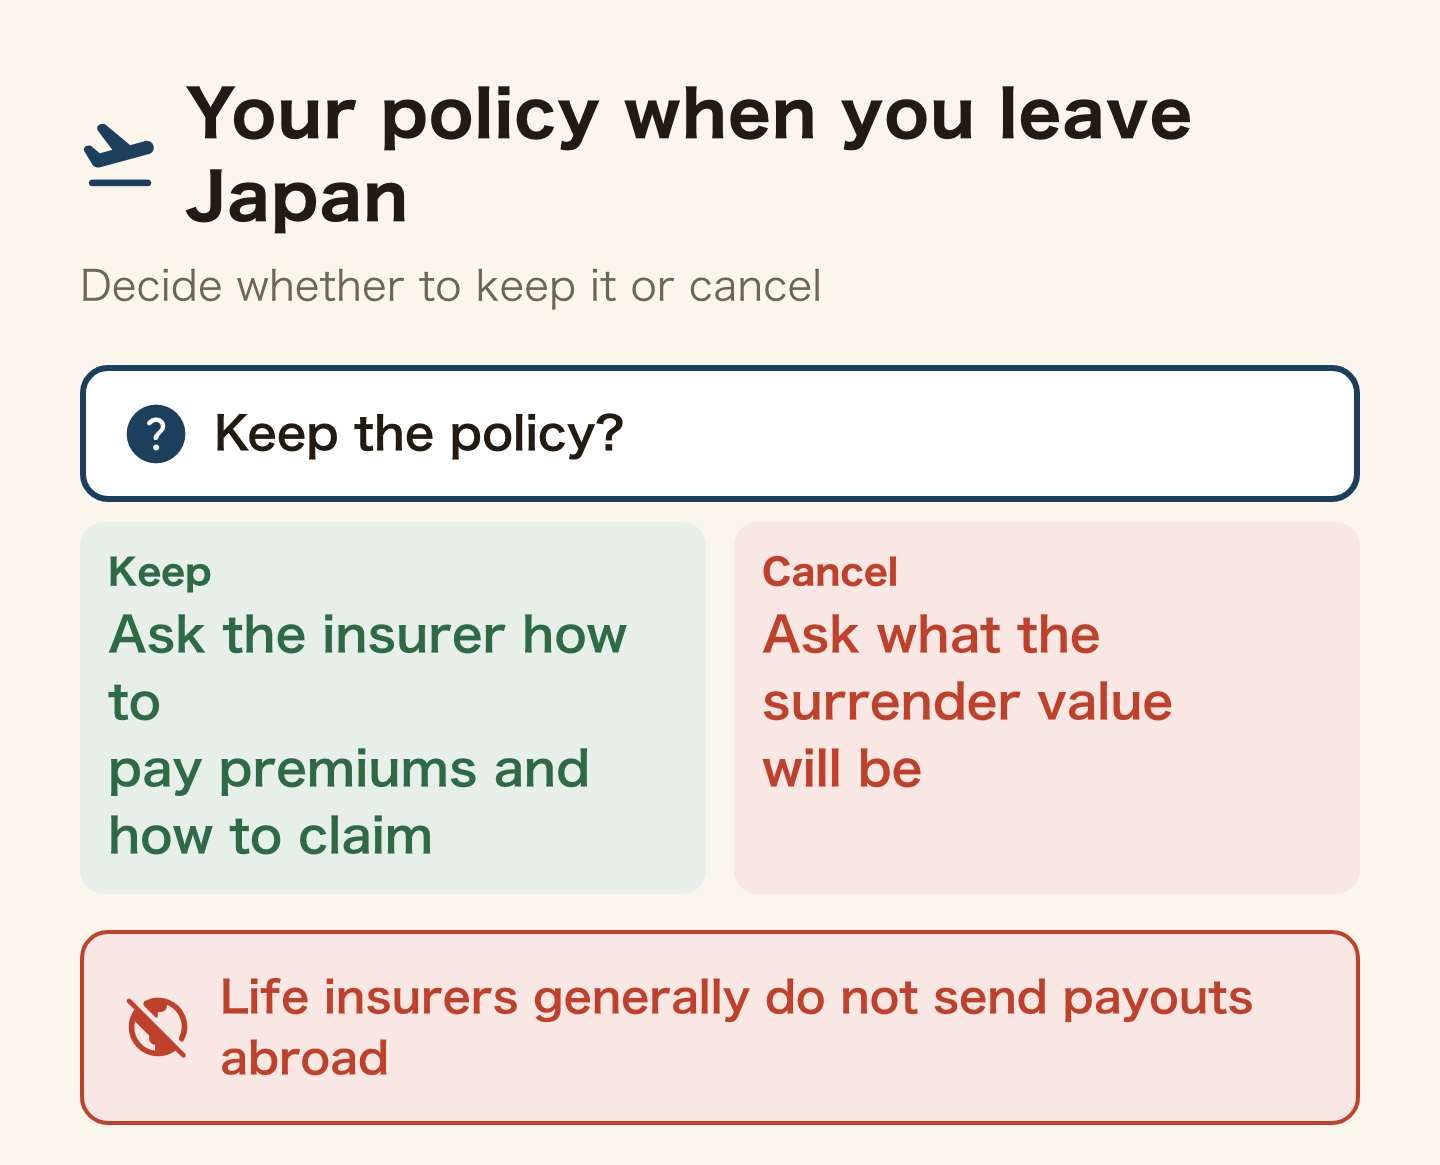
If you cancel, ask for the surrender value first. To cancel, you need a written form. Once cancelled, a policy cannot come back. For the order of everything else, see our leaving-Japan checklist. For health insurance and pension steps when you quit, see leaving a job in Japan. If you send a refund home, compare how much each transfer method delivers.
Which one are you?
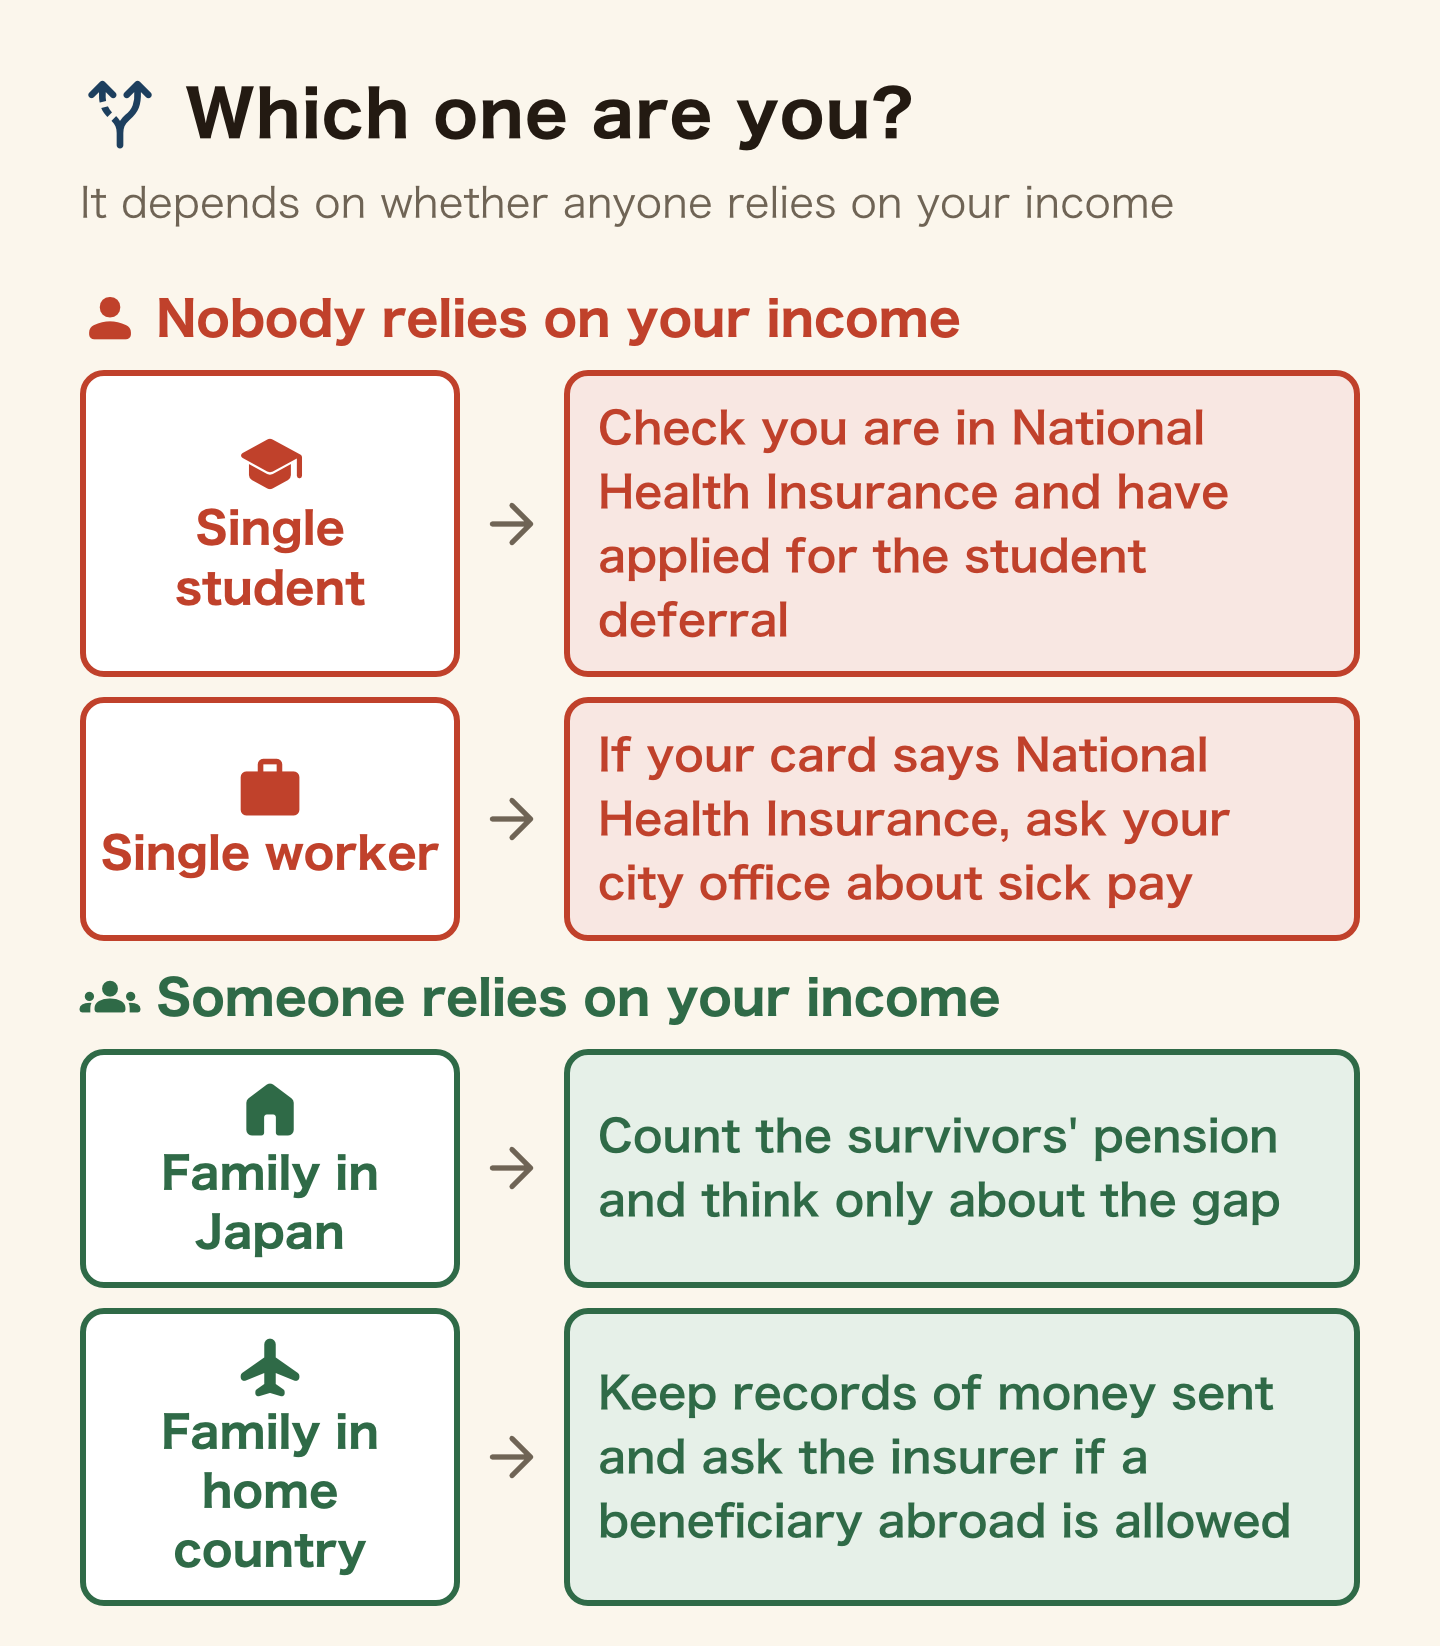
- A student with nobody living on your income — few people would be in trouble, and medical bills are capped. Today: check two things. Are you in National Health Insurance? Have you applied for the student pension deferral?
- Working and single — your biggest risk is lost pay while sick. Today: look at your health insurance card. If it says National Health Insurance, ask your city office if it pays a sickness allowance.
- Living with family in Japan — count the survivors’ pension, then think only about the gap. Today: look at your children’s ages and your pension membership. Write down which would be paid: the basic pension, the employees’ pension, or both.
- Family in your home country — both the public pension and private insurance attach conditions. Today: make sure you keep records of the money you send. Then ask your insurer (or the one you are considering) if a beneficiary abroad is allowed.
Frequently asked questions
Q. Can foreigners get life insurance in Japan?
Yes, but each company has its own conditions. We checked the published conditions of three insurers. All three required everyone, including the beneficiary, to live in Japan. All three also required enough Japanese to understand the contract. Some also required permanent residency or an intention to settle.
Q. Can my beneficiary be family living in my home country?
It depends on the insurer. All three insurers we checked required the beneficiary to live in Japan. Also, the Japan Institute of Life Insurance says life insurers generally do not send payouts abroad. Ask before you apply.
Q. Does National Health Insurance pay me if I am too sick to work?
It may not. Employee health insurance pays two-thirds of daily pay from day 4, for up to 1 year and 6 months in total. In National Health Insurance, the law lets each city choose to pay it by ordinance. Ask your city office.
Q. Can a foreigner’s family get a survivors’ pension in Japan?
Yes, if the conditions are met. The Japan Pension Service’s rules on who can receive it do not mention nationality. The basic survivors’ pension goes to a spouse with a child, or to the child. The employees’ one goes to a spouse, child, parents and others, in order. For family abroad, you must also show that they relied on your income.
Q. How much is life insurance in Japan?
In the Japan Institute of Life Insurance’s 2025 survey, the average annual premium was 171,000 yen (including individual annuities). And 80.0% of people were insured. The survey covers people aged 18 to 79 in Japan. So work out your own amount from what the survivors’ pension and your savings would not cover.
Q. What should I do with my policy when I leave Japan?
Decide whether to keep or cancel it. To keep it, ask how to pay premiums and how to claim. To cancel, ask for the surrender value first. Cancelling a savings-type policy early may return nothing, or very little.
Summary
Do you need life insurance as a foreigner in Japan? It mostly depends on whether anyone here lives on your income. Count three public benefits first. Medical bills have a monthly cap. For lost pay, employee health insurance has the sickness allowance. National Health Insurance may not pay it. After death, family who relied on your income can receive a survivors’ pension.
Private insurance is only for what those three do not cover. Foreigners can buy it. But some insurers require the beneficiary to live in Japan and the applicant to read Japanese. And savings-type policies return less than you paid if you cancel early. First think about when you might leave Japan and where your family lives. Then ask the insurer about its conditions.
Official sources: MHLW, high-cost medical expense benefit / MHLW reference document / Japan Health Insurance Association, sickness and injury allowance / e-Gov, National Health Insurance Act / Tokyo NHI benefits / Tokyo NHI high-cost medical expenses / Japan Pension Service, survivors’ basic pension / survivors’ employees’ pension / livelihood maintenance / claims from overseas / lump-sum withdrawal FAQ / student deferral / MHLW, survivors’ pension reform / National Tax Agency No.1140 / No.1141 / Japan Institute of Life Insurance 2025 survey (enrolment) / (premiums) / term, endowment and whole life / cancellation / moving abroad (all checked 7 October 2026, in Japanese). Insurers’ conditions are from their own FAQs (1, 2, 3) as of 7 October 2026. This article explains how the system works. It does not recommend any policy.
Related reading
Found this useful? Share it
Send it to a friend who lives in Japan.
WHO WROTE THIS
mori
Japanese. I read the ministries’ own notices, orders and Q&As in the original, and I start from what my Nepalese and Sri Lankan friends in Japan actually ran into. I do not write about what I have not checked or been told.
What this site can and cannot do →Looking for something else?
You may use the figures in this article, including commercially, if you credit this site with a link. How to use our figures