Figures, prices and terms were checked against the MHLW notice on the high-cost medical expense revision effective August 2026 on 6 August 2026, and the two-system comparison against Kyokai Kenpo’s FY2026 rates on 13 September 2026. They change – check the current terms yourself before you sign up or file anything.
In short
- Japan has two public health insurances, and you are in exactly one. Employees are enrolled by their company; everyone else joins National Health Insurance at the city office within 14 days.
- You pay 30 percent of medical costs: a 10,000 yen bill becomes 3,000 yen.
- Premiums depend on your city and income. If money is tight, apply for a reduction – do not ignore the bills.
- Unpaid premiums can hurt your visa renewal (as of July 2026).
If you live in Japan for more than three months, you must be in one of Japan’s two public health insurances. If a company employs you, it enrols you in Employee Health Insurance and you do nothing. Everyone else joins National Health Insurance (国民健康保険 / kokumin kenkō hoken, shortened to kokuho) at the city office.
This is not optional. It is a legal requirement. But it is also one of the best things about living in Japan: it turns a ¥10,000 hospital bill into a ¥3,000 bill.
This guide first tells you which of the two you are in, then explains kokuho in full – how to join, what it costs, and the mistakes that cause real problems, including one that can affect your visa renewal.
- Which health insurance are you in? Japan has two
- Why this matters: you pay only 30%
- Join within 14 days – this is important
- Where to go and what to bring
- What it costs
- If you cannot afford it, do not ignore it
- What happens if you fall behind on payments
- Unpaid premiums reach your visa
- Using your insurance card
- If your bill is very large: the high-cost medical system
- Things people get wrong
- Quick summary
- Related guides
- Frequently asked questions
Which health insurance are you in? Japan has two
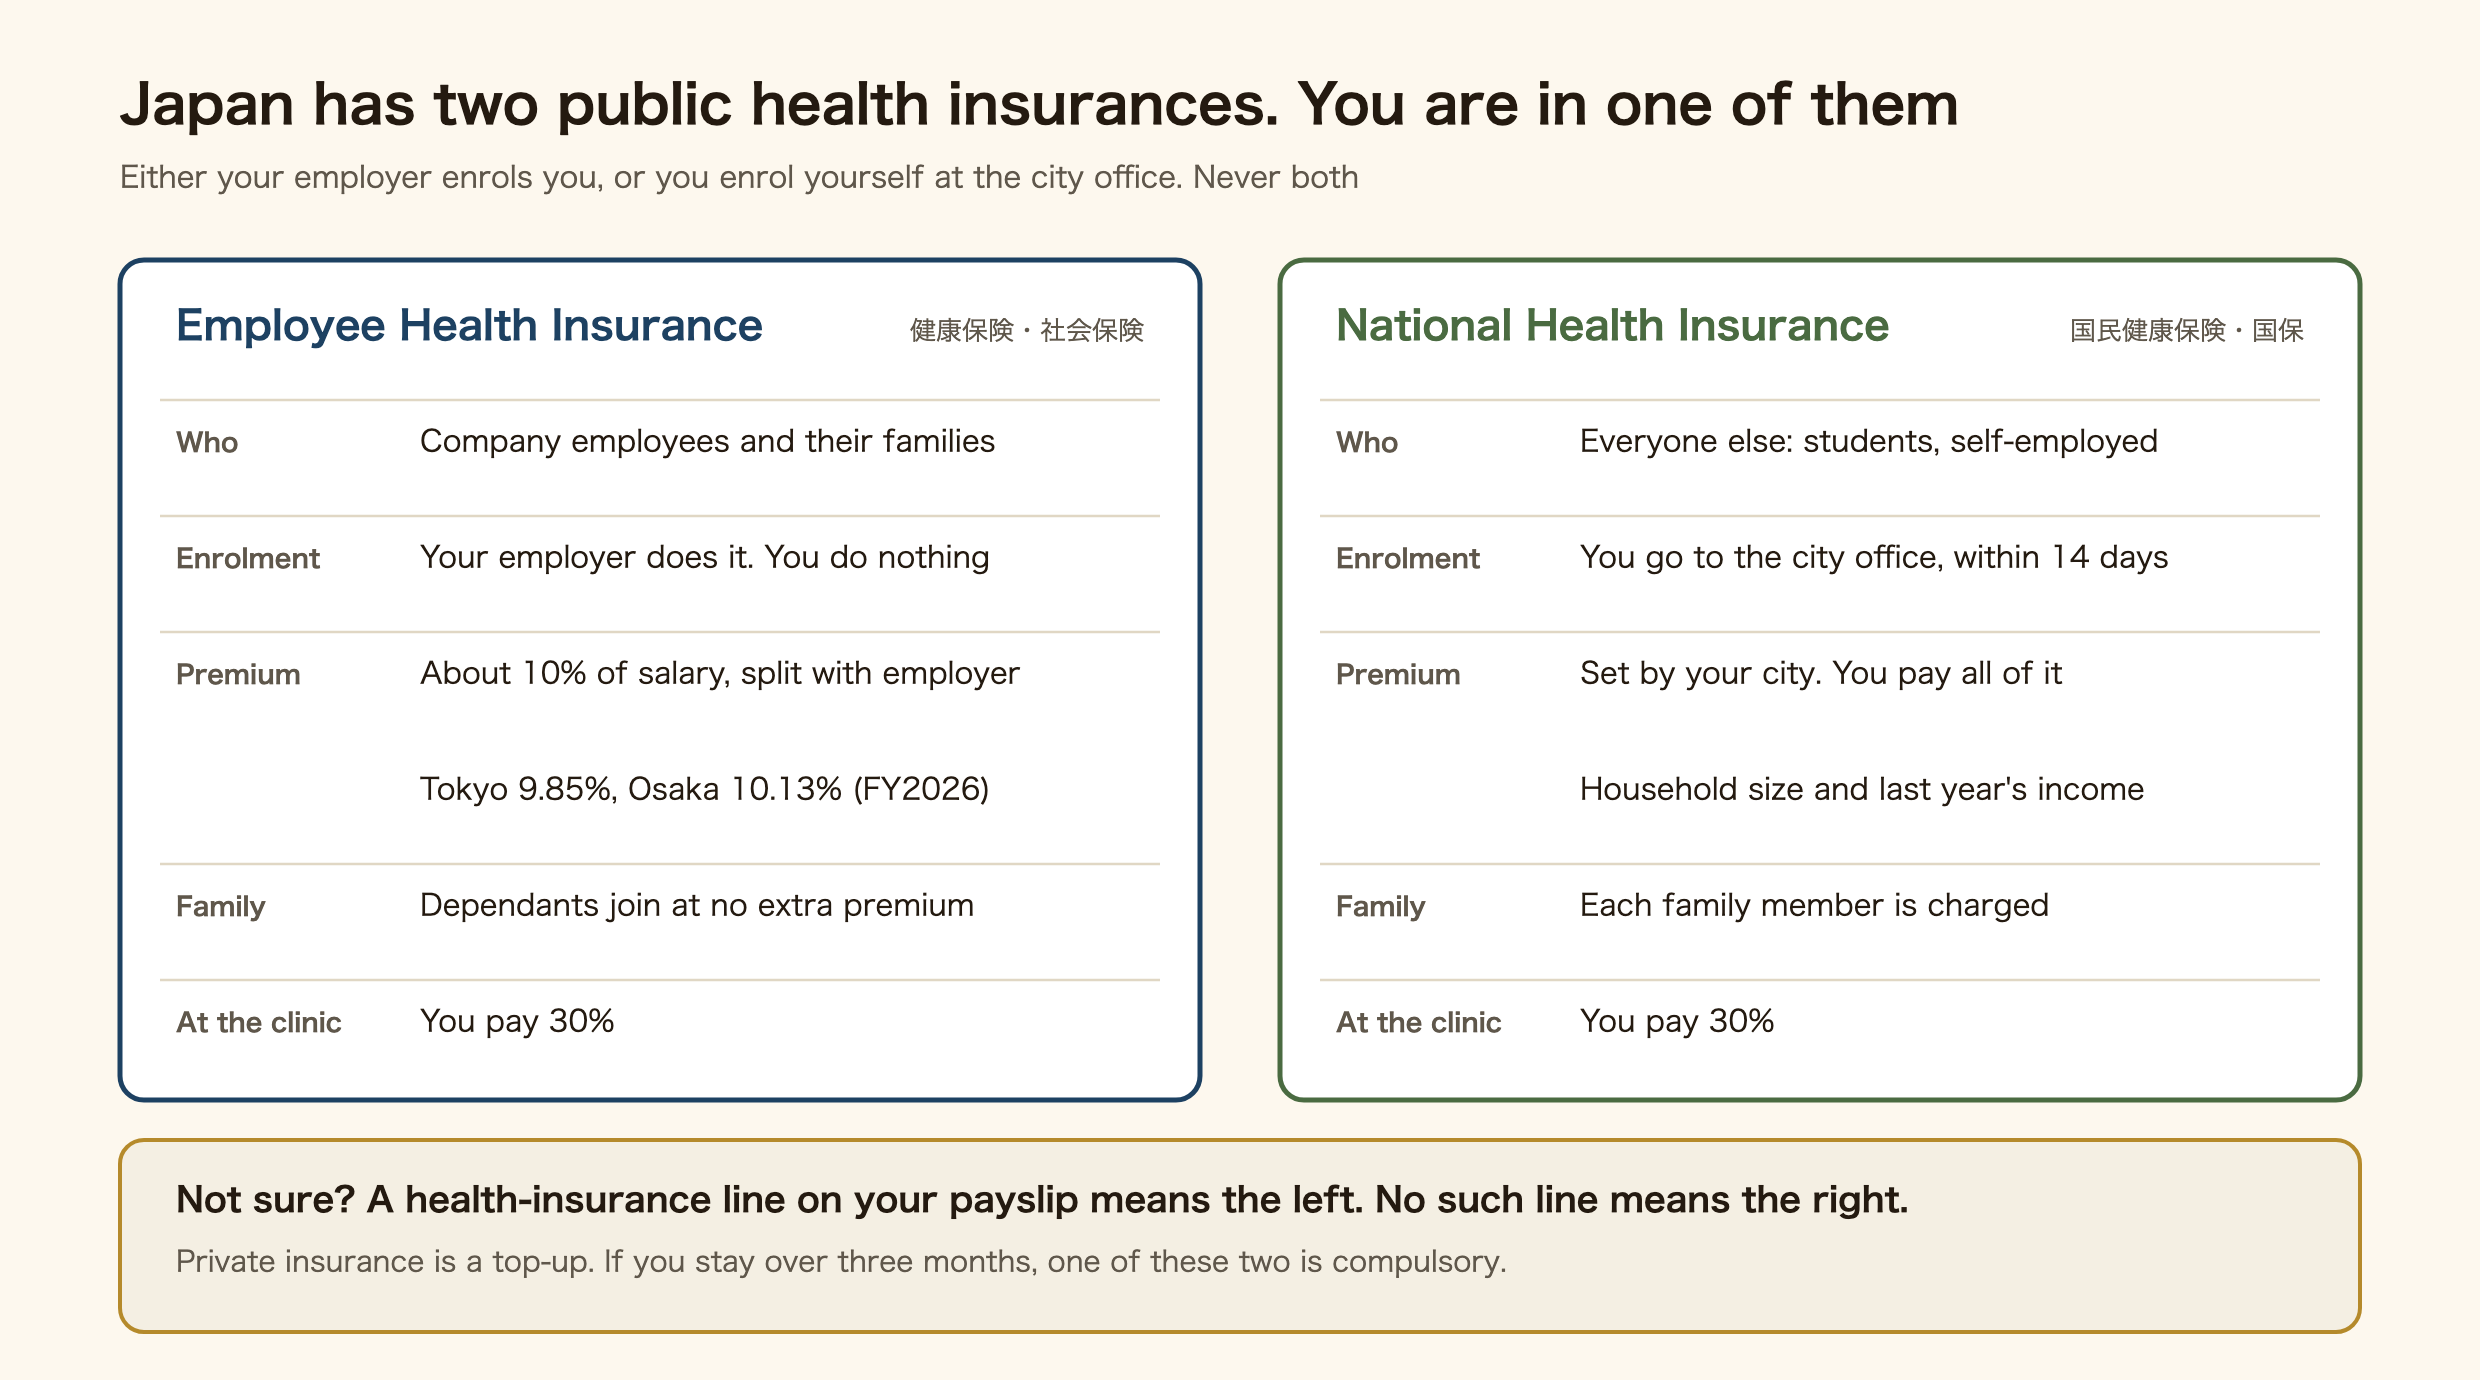
Employee Health Insurance (健康保険 / kenkō hoken, often called shakai hoken) is for people employed by a company. The company enrols you. The premium is roughly 10% of your salary, and the employer pays half of it – the law splits it evenly. The rate is set by prefecture each year: for fiscal 2026, Tokyo is 9.85%, Osaka 10.13%, Aichi 9.93%. Your spouse and children can join as dependants at no extra premium, as long as they live in Japan and earn under 1.3 million yen a year.
National Health Insurance (kokuho) is for everyone the first one does not cover: students, the self-employed, part-timers whose employer does not enrol them, and anyone between jobs. You enrol yourself at the city office. The premium is set by your municipality from your household size and last year’s income, and you pay all of it – there is no employer to share it. Each family member is charged, though children and low-income households get reductions.
Not sure which you are in? Look at your payslip. A line deducting health insurance (健康保険) means you are in Employee Health Insurance. No such line means you must be in kokuho – and if you are not, you need to go to the city office. You are never in both.
One more thing, because the top search results are mostly insurance companies: private and international health insurance is a top-up, not a replacement. Public insurance is compulsory for anyone staying more than three months. A private policy can add English-speaking support or cover abroad, but it does not free you from the public system.
The rest of this guide is about kokuho, because that is the one you have to handle yourself.
Why this matters: you pay only 30%
With kokuho, the government pays 70% of your medical costs. You pay the remaining 30% (20% for children before primary school).
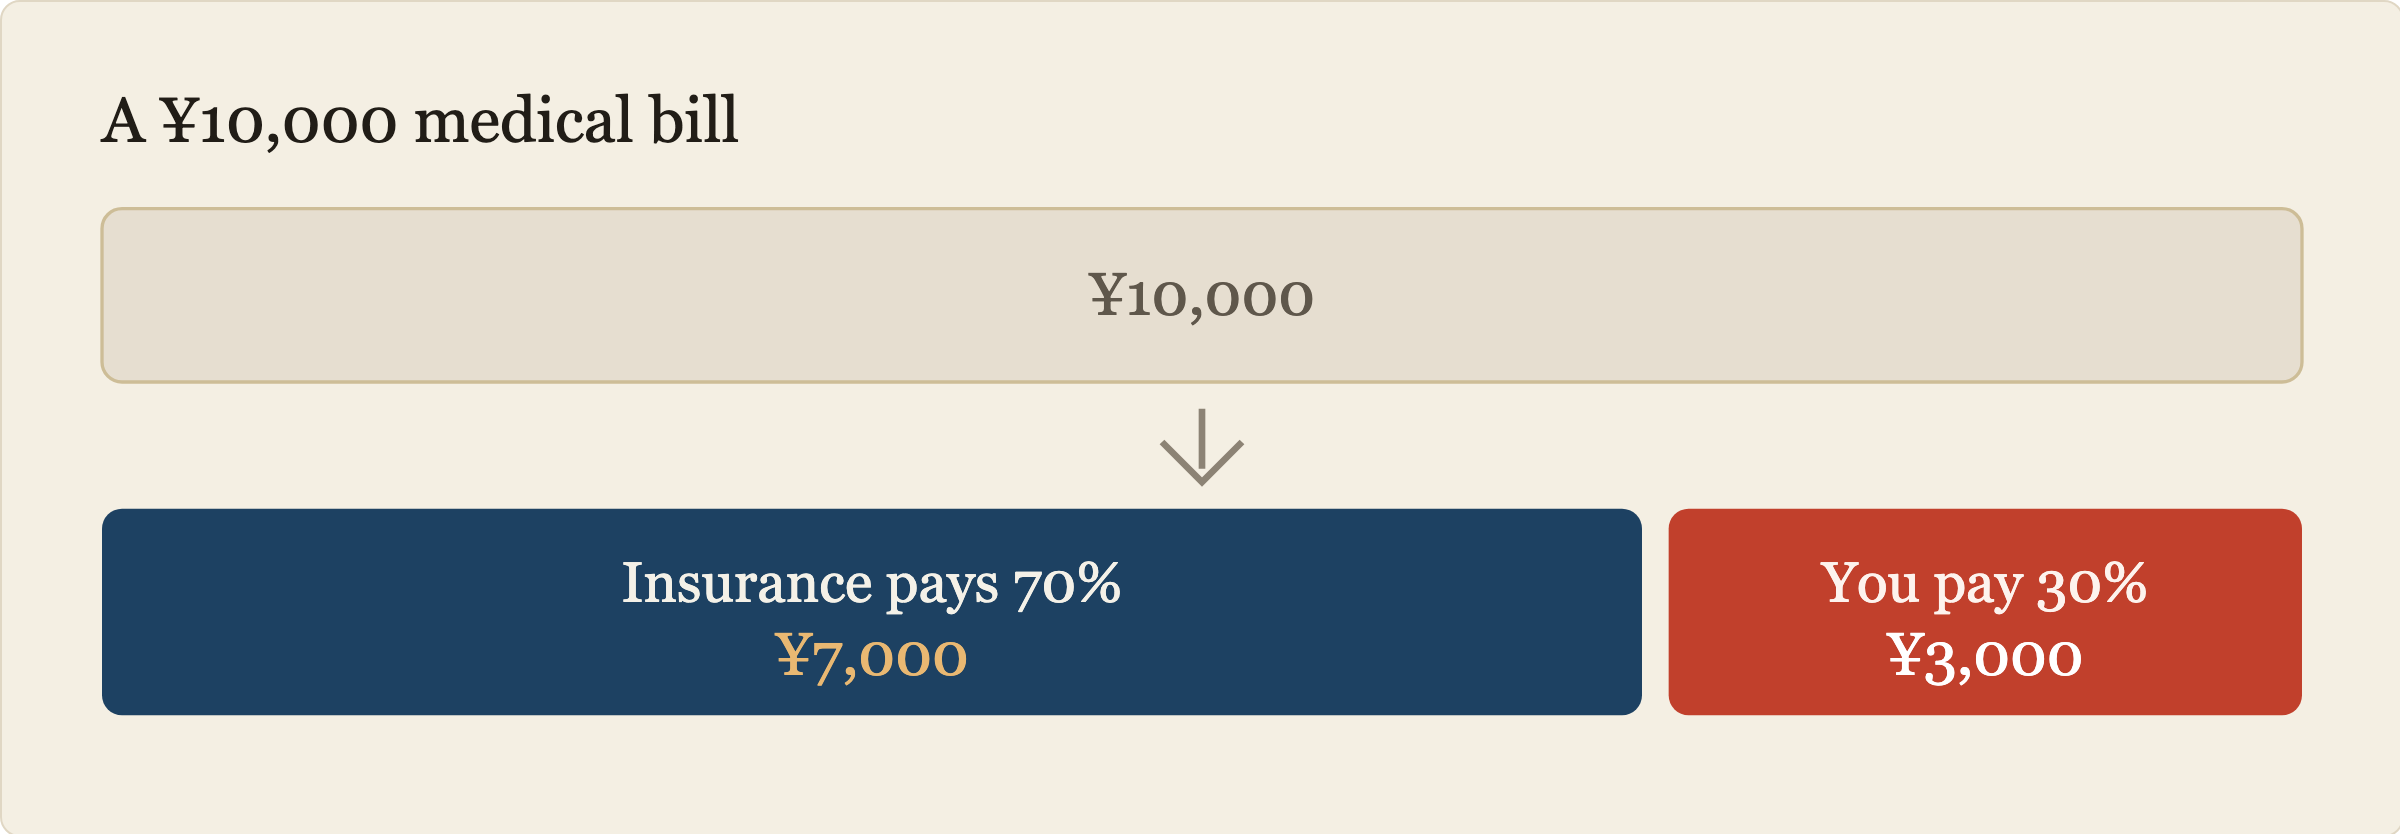
The same 30% rate applies to a ¥50,000 surgery – you would pay ¥15,000. It works at hospitals, clinics, pharmacies, and dentists (the one exception: an injury at work or on the commute goes through rosai insurance instead). (Cosmetic treatment such as teeth whitening is not covered.)
Join within 14 days – this is important
You must apply within 14 days of registering your address at the city office.
Why this matters: coverage does not start from the day you apply. It starts from the day you became a resident. So if you delay:
- You will be charged the back premiums for all the months you skipped
- Any hospital visit before you joined is 100% your cost, and cannot be refunded later
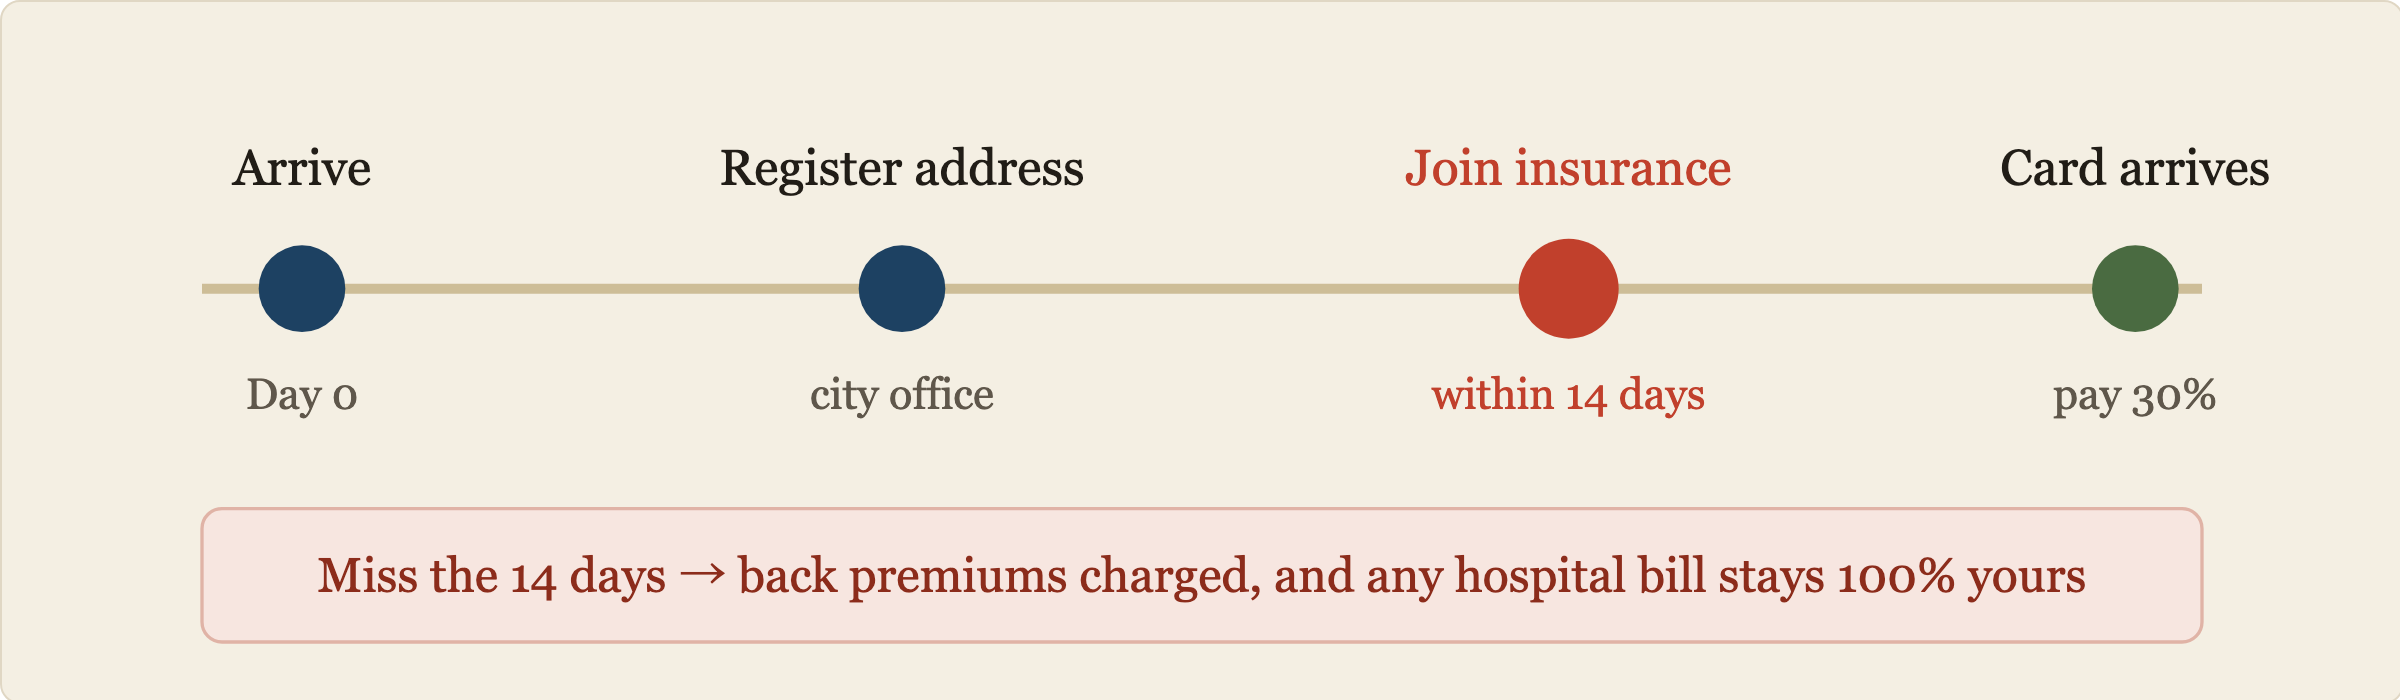
Example: you arrive on 1 April but join in May. Your April hospital bill stays 100% yours – and you still owe April’s premium.
Where to go and what to bring
Go to the city, ward, or town office (市役所・区役所・町役場) for the address where you actually live. You cannot do this at a different municipality’s office.
At the office, look for one of these counters:
- 国民健康保険課 (kokumin kenkō hoken ka) – National Health Insurance Division
- 保険年金課 (hoken nenkin ka) – Insurance and Pension Division
You can show that text on your phone at the information desk.
Bring these
- Residence card (在留カード / zairyū kādo) – essential
- Passport
- My Number card or notification slip (マイナンバーカード / 通知カード)
- Personal seal (印鑑 / inkan) – many offices now accept a signature instead
- Student ID (学生証) – sometimes requested
Requirements vary slightly by municipality, so check your city’s website first if you can. If you have already registered your address, see our guide to the residence certificate (juminhyo).
What it costs
Premiums are not the same everywhere. Each municipality sets its own rate, and the amount is based on last year’s income.
Because most students earned little or nothing in Japan last year, their premiums are usually low:
- Students with little income: roughly ¥1,000-2,000 per month
- Those working more part-time hours: roughly ¥3,000-5,000 per month
Your city office can tell you your exact amount. If you work part-time, our guide on tax for part-time workers explains how income is counted.
How to pay
- Payment slip (納付書 / nōfusho) at a convenience store or bank
- Automatic bank transfer (口座振替 / kōza furikae) – easiest, set it up once
Monthly is standard, but you can pay several months at once.
If you cannot afford it, do not ignore it
This is the most important paragraph in this article.
If you stop paying:
- Your insurance card can stop working – you pay 100% at the hospital
- Late fees (延滞金 / entaikin) are added
- It can affect your visa renewal. Immigration may check whether you have paid. Unpaid premiums can be treated as a sign that you are not meeting your obligations as a resident.
That last point surprises many people, and it is the reason ignoring the bills is dangerous.
Go to the city office and say you cannot pay. Reduction programmes (減免 / genmen) and instalment plans exist, and low-income residents often qualify. Staff will not report you or cancel your visa – their job is to arrange payment. Asking early is always cheaper than staying silent.
What happens if you fall behind on payments
Ignore it rather than talk to them, and it gets heavier in stages. First come reminders, then late charges. So far, the same as any unpaid tax.
The next stage is the problem. Prolonged non-payment switches you to something called “special medical expenses”. What you are issued then is a “qualification confirmation document (special medical treatment)”, and walking into a hospital with that means paying the full 100% at the counter. Not 30%. A 10,000 yen treatment costs you 10,000 yen instead of 3,000.
You can claim the difference back afterwards, but if you cannot produce the full amount on the day, that is the same as not being able to go.
The names are confusingly close, so read this part carefully. It is not the ordinary “qualification confirmation document”. That one, issued to people without a My Number health card, still gets you treated at 30%. The one that non-payment switches you to has “(special medical treatment)” attached.
Note also that the short-term insurance card and the qualification certificate were abolished on 2 December 2024. Articles written before that date explain this using those two old names; the system now works as described above.
Unpaid premiums reach your visa
Asking for help also protects permanent residence (August 2026 draft)
Draft operational guidelines were published for the revocation system starting in April 2027. The ground “wilfully failing to pay public dues” includes public health insurance and pension premiums.
The draft also spells out what does not count: “illness, disaster, unemployment and other unavoidable circumstances”, and “responding to demands, showing willingness to pay, and being granted instalments or a deferral”. Being unable to pay is not itself the problem. A record of going to the counter and arranging instalments is what protects your status. (Public comment runs to 4 September 2026; this is still a draft.)
This is the part that weighs most on foreign residents.
When you apply to extend your period of stay, the counter asks to see your health insurance card. Since 2 December 2024, anyone without a card shows the qualification screen in Mynaportal, the “qualification information notice”, or a qualification confirmation document instead. Whether you have been paying is visible on the spot.
The Immigration Services Agency guideline puts it this way: where premiums that the law requires you to pay, national health insurance among them, involve large unpaid sums or long periods of non-payment, the serious cases are weighed as a negative factor.
For permanent residence it is more explicit still. Properly fulfilling public obligations, meaning tax, public pension, and public health insurance premiums, is one of the requirements itself. If you are working toward permanent residence, unpaid premiums land directly on that.
Which is why the previous section bears repeating. When you cannot pay, the move is to talk to them, not to ignore it. The city office does not report you, and asking for help does not touch your visa. Ignoring it is what touches your visa.
Using your insurance card
After you join, you receive an insurance card (保険証 / hokenshō). Carry it in your wallet at all times.
- Show the card at the hospital reception
- Give your name and date of birth
- Pay only your 30% at the end
- At the pharmacy, show the card again to get medicine at 30%
If you forget your card
You pay 100% that day. Keep the receipt, take it to the city office, and you can claim the 70% back. You do not lose the money – it just takes extra work.
Card rules
- Update your address immediately if you move
- Check the expiry date and renew on time
- Never lend your card to anyone. This is a crime in Japan, and it can end your stay.
If your bill is very large: the high-cost medical system
If you need surgery or a hospital stay, costs can be high even at 30%. Japan has a safety net called the High-Cost Medical Expense Benefit (高額療養費制度 / kōgaku ryōyōhi seido).
It sets a monthly maximum based on your age and income. Anything above that limit is refunded. From treatment in August 2026, the monthly ceiling for under-70s is 36,900 yen for a resident-tax-exempt household (it was 35,400), 61,500 yen for income of roughly 2.6-3.7 million, and 85,800 yen + 1% for roughly 3.7-5.1 million. A yearly cap was added at the same time – 290,000 yen for a tax-exempt household, 530,000 for the bands above (MHLW, checked August 2026). If a hospital stay is planned, get a “limit certificate” (限度額適用認定証) from your city office first so you only ever pay up to the ceiling at the counter.
At the hospital counter, say: 「高額療養費制度について教えてください」 (“Please tell me about the high-cost medical expense system”). Ask before a planned hospital stay if possible – it is easier to apply in advance than to claim back later.
Things people get wrong
Going home for the holidays
Your Japanese insurance card does not work overseas. If you get treated in Nepal or Sri Lanka, you pay in full there. In some cases you can claim part of it back after returning to Japan – keep every receipt and ask your city office.
Also note: you still owe premiums while you are away, because you are still a registered resident of Japan.
Being sent to the wrong kind of hospital
For everyday problems – a cold, a fever, an injury – go to a small local clinic (クリニック / 医院), not a large hospital. Clinics have shorter waits. If you need more, they will refer you to a hospital.
Accepting treatment that insurance does not cover
Some treatment is “free treatment” (自由診療 / jiyū shinryō) and is not covered at all. If you do not understand what is being proposed, ask: 「これは保険が使えますか?」 (“Is this covered by insurance?”) before agreeing.
Quick summary
- Staying over 3 months and not on company insurance → you must join
- Apply at your city office within 14 days
- Bring your residence card, passport, and My Number
- You then pay only 30% of medical costs
- Cannot pay? Ask about genmen – never just ignore it
- Unpaid premiums can affect your visa renewal
Related guides
If this helped, please share it with a friend who has just arrived. Most people learn these rules only after they have already lost money.
This amount can also come down. Households with low income last year get 70, 50 or 20 percent off the flat part, but the reduction never arrives unless the city office knows your income. Zero income still has to be declared. See the National Health Insurance reduction.
Either public plan also pays a 500,000 yen lump sum when a baby is born.
Frequently asked questions
What is the difference between Employee Health Insurance and National Health Insurance?
Employee Health Insurance (shakai hoken) is arranged by your company, costs about 10% of salary with the employer paying half, and covers your dependants at no extra premium. National Health Insurance (kokuho) is for everyone else – students, the self-employed, people between jobs – you enrol yourself at the city office and pay the whole premium, and each family member is charged. Both leave you paying 30% at the clinic.
Do foreigners need private health insurance in Japan?
Not instead of public insurance. Anyone staying more than three months must be in one of the two public schemes. Private or international policies are optional top-ups for English-speaking support or coverage abroad.
Do I have to join National Health Insurance?
Yes. If you stay in Japan more than 3 months and have no employer insurance, joining is required by law. Register at your city office within 14 days of moving in.
How much of my medical bill does it cover?
You pay 30 percent. A 10,000 yen hospital bill becomes 3,000 yen, and it covers clinics, hospitals and prescribed medicine (as of July 2026).
What happens if I stop paying?
Unpaid premiums pile up and can hurt your visa renewal. If money is tight, apply for a reduction at the city office instead of ignoring the bills.
Official source: Ministry of Health, Labour and Welfare
Found this useful? Share it
Send it to a friend who lives in Japan.
WHO WROTE THIS

mori
Japanese. I read the ministries’ own notices, orders and Q&As in the original, and I start from what my Nepalese and Sri Lankan friends in Japan actually ran into. I do not write about what I have not checked or been told.
What this site can and cannot do →Looking for something else?